


EN
Shift4 Payments (FOUR) Stock Jumped, What Is Behind The Move?
Shift4 Payments (FOUR) has drawn fresh attention after announcing a share repurchase plan of up to US$1b, alongside new quarterly results and a partnership with Bilt centered on neighborhood-focused loyalty and payments integration.
The latest jump, with a 1-day share price return of 7.85% and a 30-day share price return of 17.87%, suggests investors are responding to the buyback and Bilt partnership. This is occurring even though the year-to-date share price return is down 28.56% and the 1-year total shareholder return has fallen 35.92%, which points to momentum rebuilding from a weak longer-term base.
Scan beyond Shift4 Payments and see how other payment and fintech players are setting up for the next leg of momentum with our hand picked 32 high quality undervalued stocks.
Shift4 Payments now trades only modestly below the average analyst target, yet far beneath some intrinsic value estimates. Is the recent rebound closing the gap to fair value, or is it only scratching the surface?
Most Popular Narrative: 11% Undervalued
Shift4 Payments last closed at $44.78, compared with an analyst consensus fair value of $50.18 from the analyst consensus Narrative on Simply Wall St. This builds that figure from Street forecasts for revenue, earnings and margins using a 10.15% discount rate.
Ongoing consolidation in the payments industry, together with Shift4 Payments three part capital allocation approach that includes tuck in M&A and a planned roughly US$300 million account to account payments acquisition that is not yet in guidance, supports further scale benefits in addition to a 46% adjusted EBITDA margin in Q2 2026 and a stated aim for roughly 60% incremental EBITDA to free cash flow conversion. This can increase free cash flow per share as integration progresses.
See why 69 investors see Shift4 Payments as 11% undervalued.
Result: Fair Value of $50.18 (UNDERVALUED)
Still, the narrative around Shift4 Payments could be challenged if travel related tax free shopping remains pressured, and higher leverage linked to new debt continues to weigh on earnings.
Find out about the key risks to this Shift4 Payments narrative.
Another View: Multiples Paint A Tougher Picture For Shift4 Payments
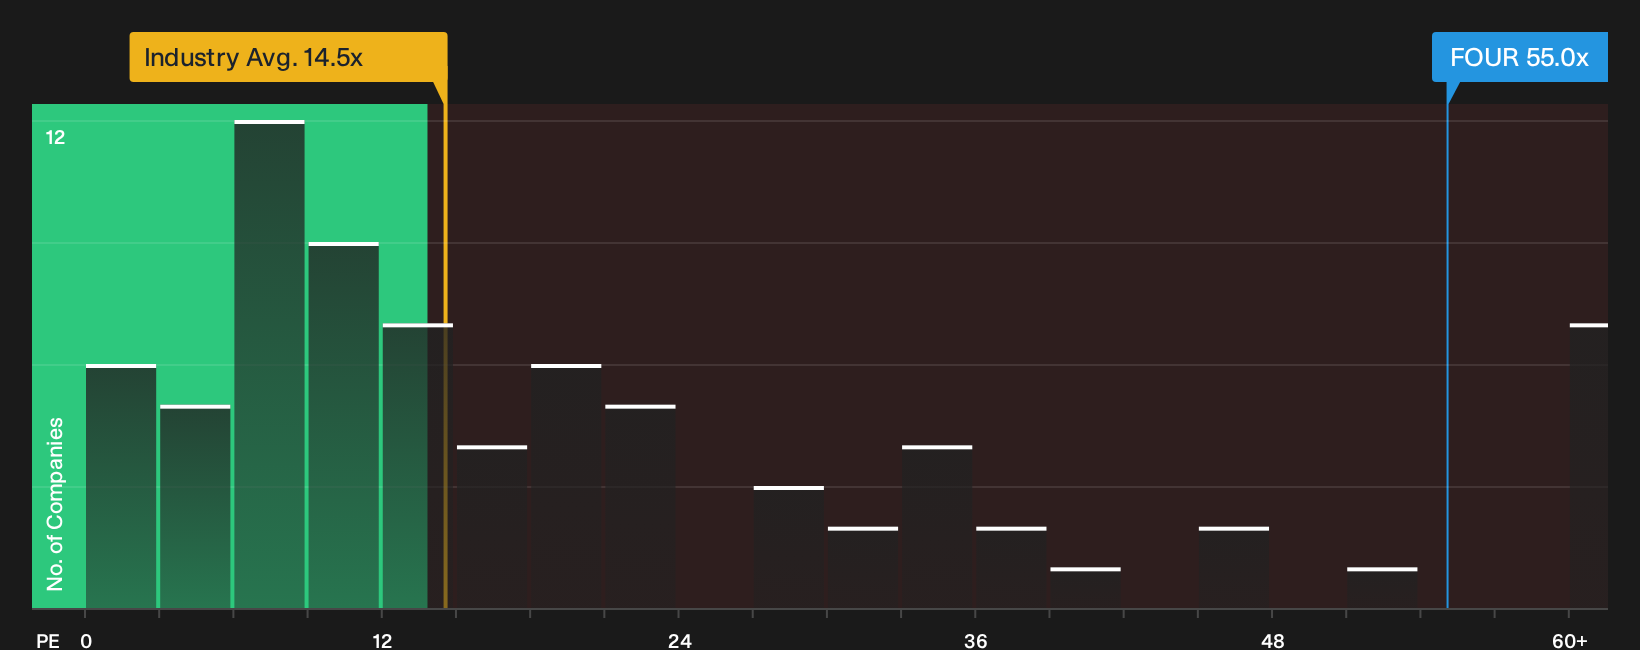
The analyst narrative frames Shift4 Payments as about 11% undervalued on a fair value of $50.18, yet the current P/E of 55x tells a different story. That ratio is far above the US Diversified Financial industry at 14.5x, the peer average at 27.9x and a fair ratio of 23x. For anyone weighing new money, does paying more than double the fair ratio feel like upside, or like valuation risk waiting to rebalance?
For a closer look at how those numbers stack up in practice, and where the market could move the ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Shift4 Payments so far, or starting to lean one way? Check the underlying data, weigh both sides, and anchor your own stance with the full picture in 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Shift4 Payments?
If Shift4 Payments has sharpened your thinking, do not stop there. Broader ideas help you compare, stress test, and upgrade your watchlist with stronger candidates.
- Target potential mispriced opportunities by scanning a curated 32 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their financial profile.
- Strengthen your defense by reviewing a 31 resilient stocks with low risk scores that focuses on businesses with more resilient balance sheets and lower overall risk scores.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlight fundamentally strong companies that many investors may still be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com