


EN
How AI Retail Testing At VF Has Changed Its Investment Story
- VF Corporation and SAP SE have opened S.Fashion, an AI enabled retail test store at SAP’s Walldorf headquarters. The store uses tools like RFID, robotics and smart mirrors to connect inventory, ordering and in store consumer journeys.
- The space gives VF Corporation a live environment to trial AI driven inventory planning, pricing and replenishment decisions. These trials could influence future cost efficiency and direct to consumer execution across brands such as The North Face, Vans and Timberland.
- We will now look at how VF Corporation’s investment narrative could be shaped by the S.Fashion AI powered retail testbed.
Scan where VF Corporation sits in this retail AI shift by comparing it with 53 AI infrastructure stocks, which could be powering similar data heavy store experiences and fulfillment networks.
V.F Investment Narrative Recap
To own V.F stock, you need to believe the portfolio reset, Vans recovery work and channel mix towards direct to consumer and e commerce can translate into sturdier earnings and free cash flow over time. The analyst consensus narrative on Simply Wall St reflects earnings growth forecasts of around 20% per year, which already build in better execution.
Right now, the key near term swing factor is whether Vans stops dragging on group results while APAC headwinds ease rather than deepen. The S.Fashion project appears helpful for refining inventory and markdown discipline, although on its own it does not change the main risk that Asia softness or a slower Vans repair could cap margin progress.
The SAP S.Fashion opening is the announcement that ties most directly into current catalysts. It connects to V.F’s supply chain and inventory overhaul, where AI enabled tools are already being used for planning and markdown calls. The live test store gives the company a way to pressure test these ideas in a controlled but real setting.
For you as an investor, the relevance is quite practical. Better forecasting and replenishment could support the aim of tighter discounting, healthier gross margins and stronger free cash flow if rolled out at scale. The flip side is execution risk. If the technology proves complex to deploy across brands or regions, the benefit to earnings and leverage targets may arrive more slowly than analysts expect.
V.F's current analyst narrative points to revenues of US$10.6 billion and earnings of US$829.9 million by 2029. That profile lines up with forecast revenue growth of 3.9% per year and an earnings increase of about 2.2x from US$369.7 million today.
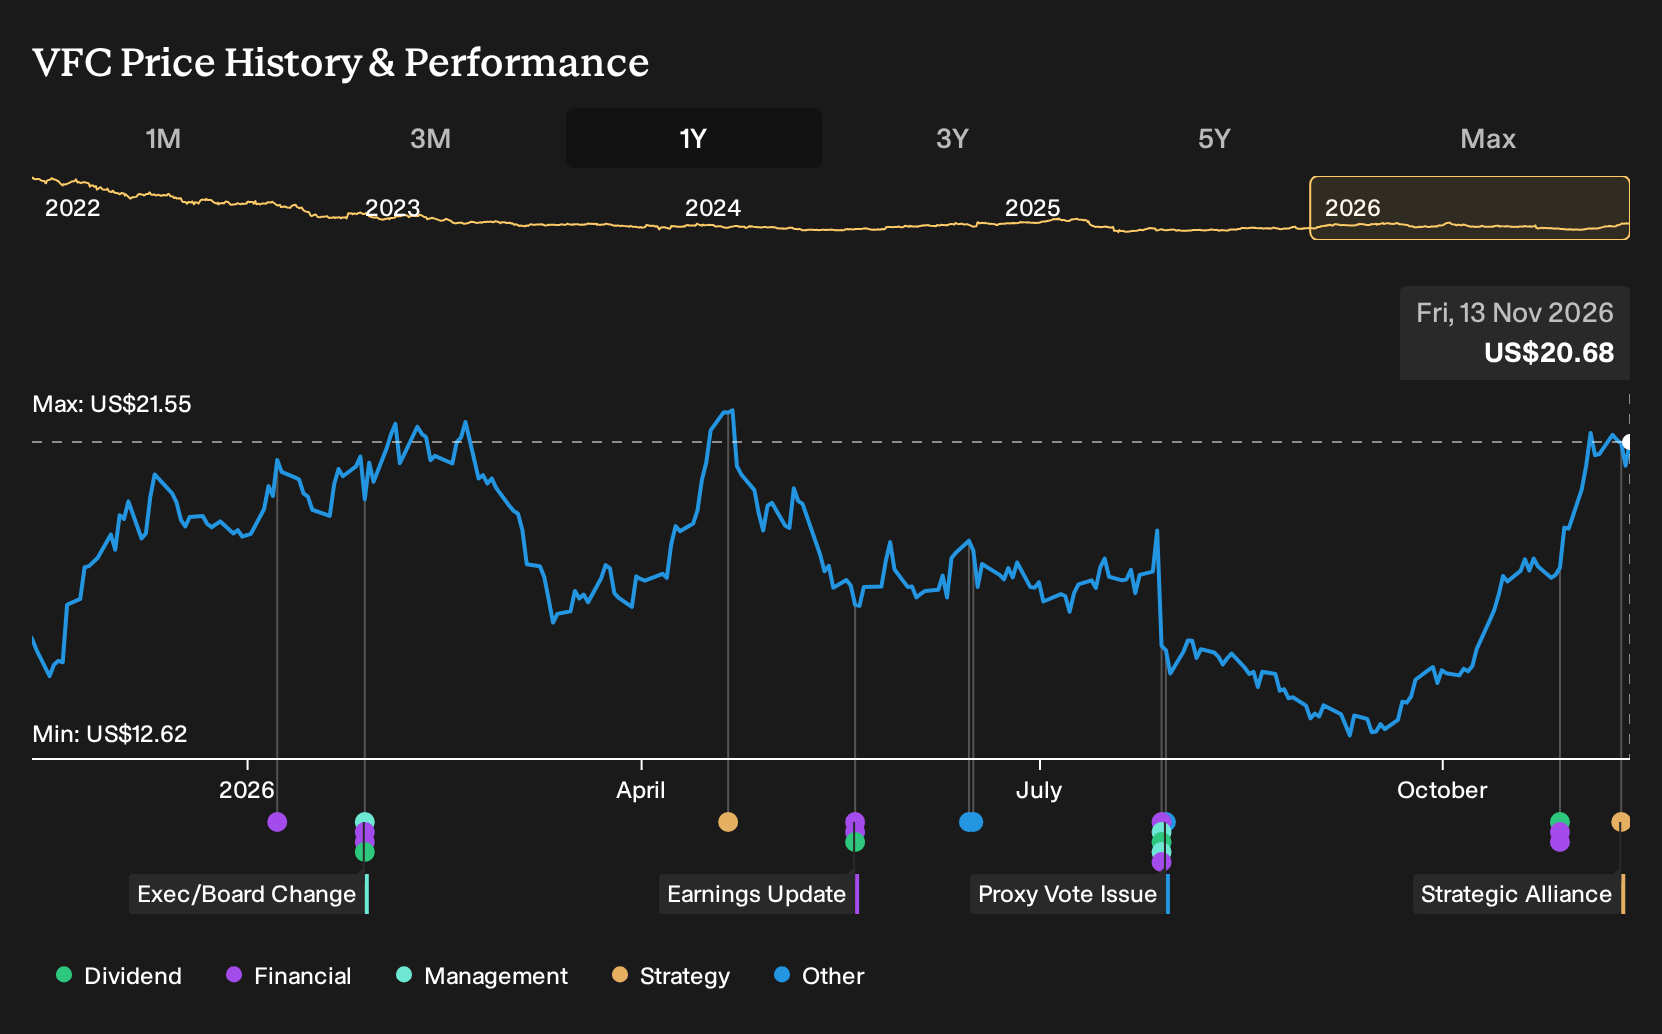
Uncover why V.F's fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view says the real swing factor for VF Corporation is tariff exposure rather than AI success. The most cautious analysts were working with roughly flat revenue around US$9.6b and earnings of about US$600.1 million by 2029 before this S.Fashion news. That gap shows how far opinions can differ, so explore both stories yourself.
Explore 2 other V.F fair value estimates, including one that suggests it could be worth just $20.05.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your V.F research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for V.F. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate V.F's overall financial health at a glance.
Looking for more investment ideas beyond V.F?
Once you have a view on V.F, it can help to cross check that thinking against other opportunities that fit different risk and income goals using the Simply Wall St Screener.
- If you want potential upside with a margin of safety, scan for companies trading on compelling valuations with the 32 high quality undervalued stocks.
- For steadier income, focus on consistent cash returns by filtering for higher yield payers using the 6 dividend fortresses.
- When capital preservation matters most, narrow your watchlist to sturdier balance sheets and lower risk profiles through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com