


EN
Frasers Logistics & Commercial Trust (SGX:BUOU) Earnings Put Fair Value Back In Focus
What the latest earnings mean for Frasers Logistics & Commercial Trust investors
Frasers Logistics & Commercial Trust (SGX:BUOU) just posted full year results to 30 September 2026 that showed higher sales of S$494.07 million but a sharp drop in net income to S$23.81 million.
These results come after a mixed run for Frasers Logistics & Commercial Trust. The share price is down 11.88% year to date and 7.77% over three months, while the 1-year total shareholder return has declined by 2.40% and the 5-year total shareholder return has declined by 19.84%. This points to fading momentum as investors reassess earnings risk around the SGD0.89 level.
Compare how Frasers Logistics & Commercial Trust stacks up against other real estate plays by scanning a curated set of list of solid balance sheet and fundamentals (198 results) for potential alternatives after this earnings reset.
Frasers Logistics & Commercial Trust still owns a sizeable portfolio across developed markets, yet the recent profit slump and weaker unit price put a sharper question on the table. Are you paying a fair price for that scale today?
Price-to-earnings of 142.4x for Frasers Logistics & Commercial Trust: Is it justified?
On a simple snapshot, Frasers Logistics & Commercial Trust trades on a P/E of 142.4x, which sits against a last close of S$0.89 and points to a rich tag being placed on each dollar of reported profit relative to peers.
The P/E ratio compares the unit price to earnings per unit and is often used for REITs as a quick sense check on how the market is valuing current income. For Frasers Logistics & Commercial Trust, a triple digit P/E suggests investors are paying a high multiple of recent earnings, even though the trust has faced a sharp earnings decline over the past year and a profit margin that sits at 4.8% compared to 43.5% previously.
That premium looks stretched when stacked against the Asian Industrial REITs industry average P/E of 16.5x and the peer average of 40.1x. It also contrasts strongly with the estimated fair P/E of 22.7x, which is the level the multiple could gravitate towards if pricing moved closer to what the fair ratio implies for this earnings profile.
Explore the SWS fair ratio for Frasers Logistics & Commercial Trust.
Result: Price-to-earnings of 142.4x (OVERVALUED)
Still, the sharp profit slump and rich P/E leave Frasers Logistics & Commercial Trust exposed if rental cash flows or property valuations face further pressure.
Find out about the key risks to this Frasers Logistics & Commercial Trust narrative.
Another view on Frasers Logistics & Commercial Trust’s value
The steep P/E for Frasers Logistics & Commercial Trust puts a lot of weight on depressed earnings, yet the SWS DCF model points in the opposite direction. At S$0.89, the unit price sits about 39.1% below an estimated future cash flow value of S$1.46. On that metric, the trust appears undervalued.
These two methods tell very different stories. The question for you is which one better reflects how you think cash flows and one-off hits should be treated.
Look into how the SWS DCF model arrives at its fair value.
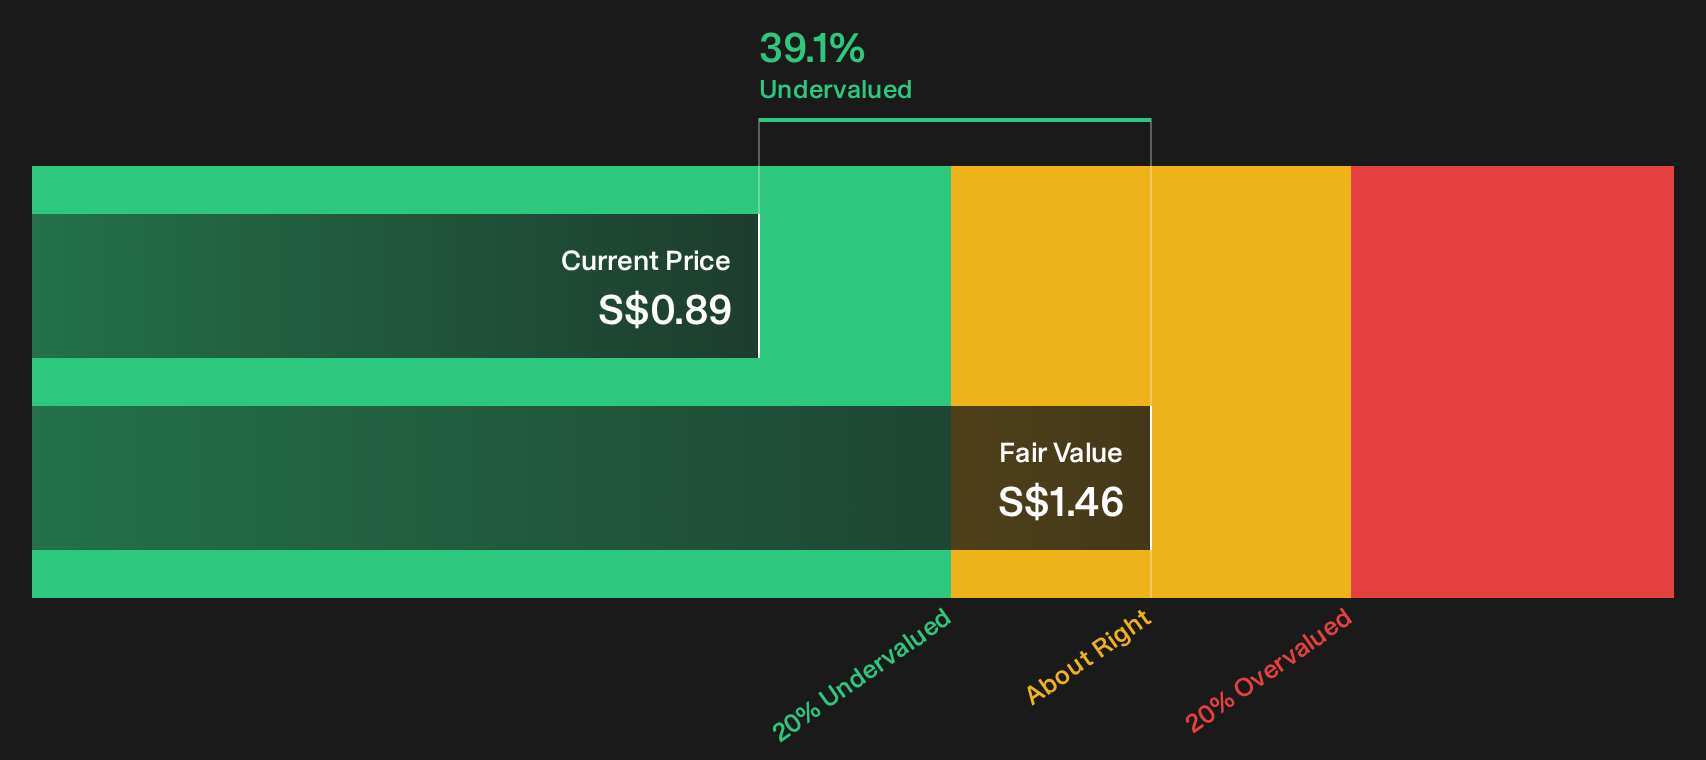
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Frasers Logistics & Commercial Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big valuation swings and conflicting signals can cut both ways, so move quickly, review the full picture, and evaluate Frasers Logistics & Commercial Trust on its own terms with the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Frasers Logistics & Commercial Trust?
If Frasers Logistics & Commercial Trust has you reassessing your options, broaden your watchlist and stress test your thesis across other high quality opportunities.
- Pinpoint steady compounders by scanning a curated set of 210 resilient stocks with low risk scores that aim to keep volatility in check while you focus on the long game.
- Hunt for mispriced quality through the 560 high quality undiscovered gems and get ahead of the crowd before attention and liquidity catch up.
- Target resilient income payers using the 220 dividend fortresses to spot yield opportunities that can complement or contrast your REIT exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com