


EN
Should Earnings Results Require Action From Essential Utilities Stock Investors?
- Essential Utilities reported third quarter 2026 sales of US$508.26 million and net income of US$103.84 million, with basic earnings per share from continuing operations of US$0.37.
- The nine month 2026 figures show sales of US$1.90b, while net income was US$433.95 million and basic earnings per share were US$1.53, which sit below the prior year despite the stronger third quarter snapshot.
- We will look at how Essential Utilities' investment narrative lines up with third quarter earnings growth in sales and net income.
Compare Essential Utilities' earnings profile with other regulated utilities by scanning our hand picked 31 resilient stocks with low risk scores that aim to balance steadier operations with controlled risk.
Essential Utilities Investment Narrative Recap
To own Essential Utilities, you need to be comfortable with a regulated utility that leans heavily on large, ongoing infrastructure projects and the proposed American Water merger to justify that capital spend. The third quarter showed higher sales and net income than a year ago, yet nine month earnings per share remain below the prior period. That mix keeps the near term story balanced between operational progress and earnings pressure.
The key short term catalyst is continued execution on rate cases and project delivery that can support returns on the US$1.4b to US$1.7b yearly investment plan. The biggest current risk sits in the combination of regulatory scrutiny on pricing and funding needs, where interest coverage is already flagged as tight and equity issuance or higher financing costs could weigh on per share outcomes.
The most relevant recent update is the third quarter and nine month 2026 earnings release itself. Essential Utilities reported third quarter sales of US$508.26 million and net income of US$103.84 million, with basic earnings per share from continuing operations of US$0.37. Over the first nine months, sales reached US$1.90b and net income came in at US$433.95 million, while basic earnings per share was US$1.53.
That pattern, where year to date earnings per share and net income are below the prior year despite a stronger recent quarter, ties directly into the catalysts in the analyst consensus Narrative on Simply Wall St. A business planning US$1.4b of infrastructure spend in 2025 and US$1.7b in 2026, alongside the American Water merger, needs consistent earnings support, solid rate decisions and manageable financing costs for the story to stay intact.
What Analysts Are Building Into The Essential Utilities Story
Analyst models around Essential Utilities lean heavily on steady top line expansion, wider profit margins and the American Water merger coming together cleanly enough to support those targets. Revenue is assumed to grow by 4.1% a year over the next three years, which is a measured pace rather than a high growth profile, and profit margins are expected to widen from 21.6% today to 25.9% over the same stretch.
On earnings, the consensus points to net income of US$554.9 million today and a move to US$751.1 million by 2029, paired with forecast earnings per share of US$2.62. That implies an earnings increase of about US$196 million over the next few years, which matters for investors because a larger profit pool is what would help absorb ongoing capital spending, extra financing costs and any share issuance linked to the merger or infrastructure build.
Bringing those assumptions together, Essential Utilities' narrative projects US$2.9b revenue and US$751.1 million earnings by 2029. This relies on 4.1% yearly revenue growth and about US$196 million earnings increase from US$554.9 million today.
The valuation work in the Simply Wall St report translates those operating targets into a share price framework. Analysts collectively sit on a US$41.20 consensus price target, with views spread between US$38.00 on the cautious side and US$47.00 at the upper end. That band reflects differing confidence levels around the same building blocks, including whether 4.1% annual revenue growth is realistic, whether margins can reach 25.9%, and whether the American Water merger lands on time and on the terms currently expected.
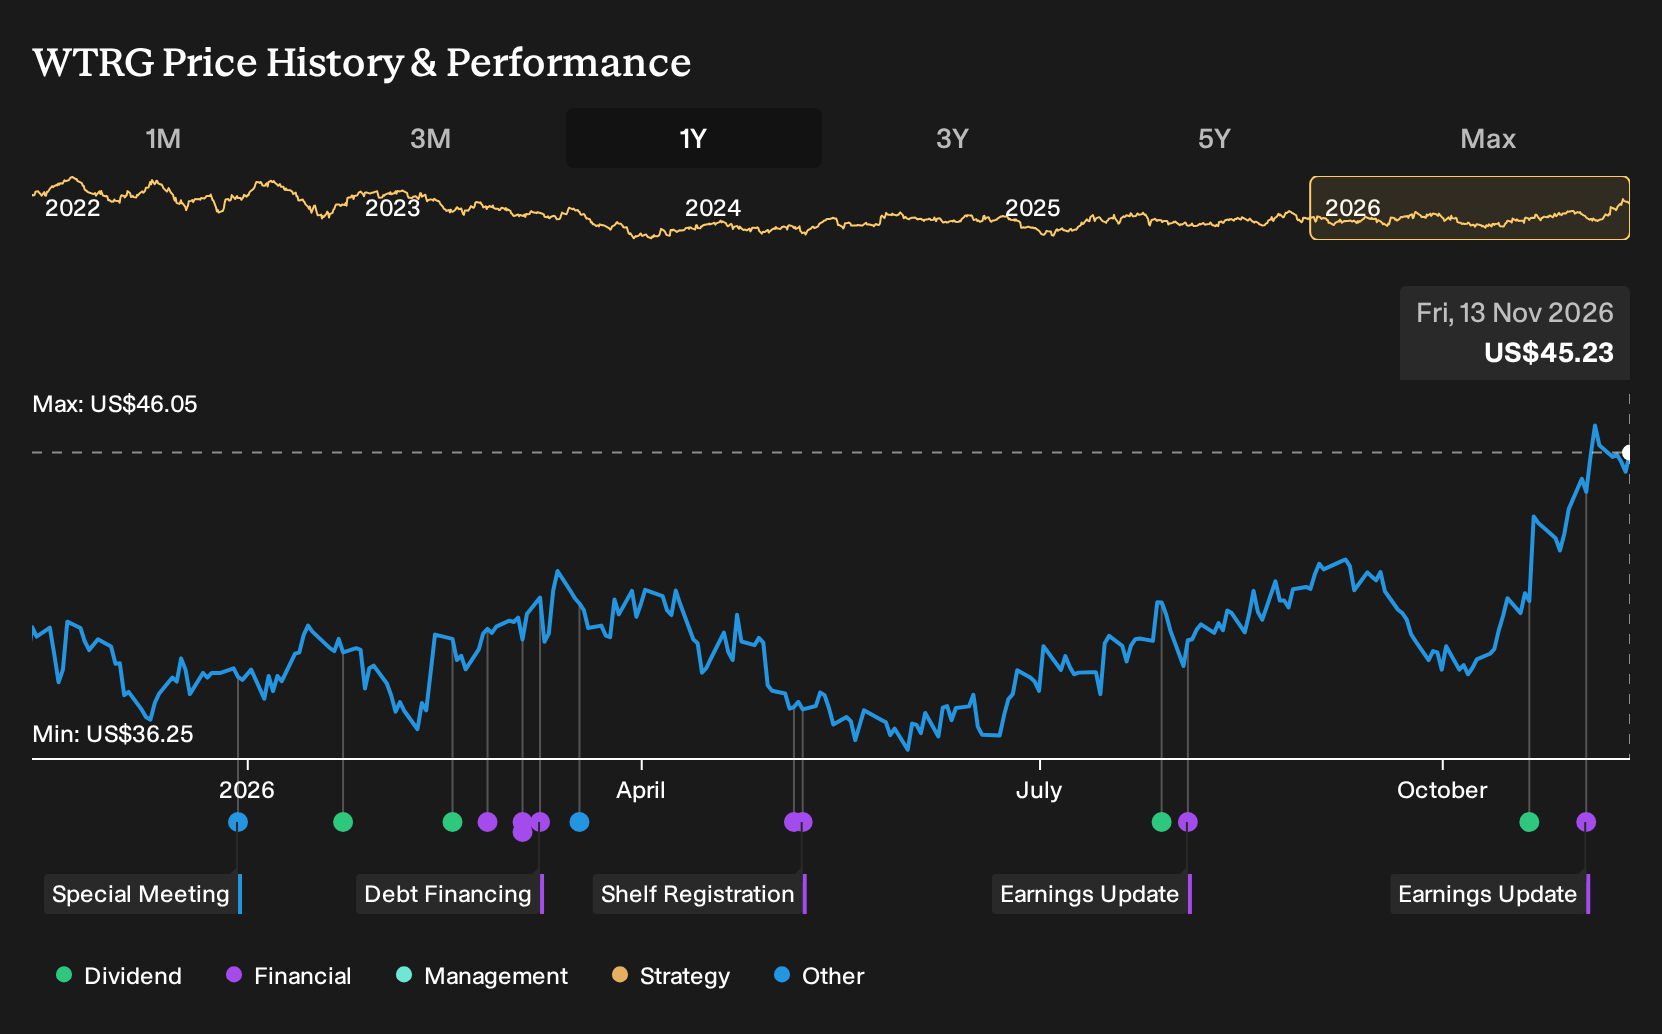
At a forecast P/E of 19.4x on 2029 earnings, compared with 21.8x on current numbers and 22.2x for the broader US water utilities peer group, the analytical framework assumes investors are willing to pay slightly less for each dollar of future earnings than the wider sector commands today. That matters because it keeps the story firmly tied to execution. If Essential Utilities delivers the projected US$2.9b of revenue, US$751.1 million of earnings and the higher margin profile, the current share price near US$42.64 lines up reasonably closely with consensus views. If any of those levers shift, the fair value logic shifts with them.
Uncover why Essential Utilities' fair value indicates a 9% potential downside to its current price, suggesting a premium that may not be sustainable.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between US$41.20 and about US$43.91, so retail forecasts currently hug the analyst consensus on Essential Utilities. Before factoring in the latest earnings release, you still need to weigh regulatory pushback on rates and heavy infrastructure funding needs, then decide which camp you lean toward.
Explore another Essential Utilities fair value estimate, including one that suggests up to 9% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Essential Utilities research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Essential Utilities. The report includes a comprehensive fundamental analysis summarized in a single visual (the Snowflake), making it easy to evaluate Essential Utilities' overall financial health at a glance.
Looking For More Investment Ideas Beyond Essential Utilities?
If the Essential Utilities story has sharpened your view on regulated utilities, broaden your watchlist by scanning other opportunities through the Simply Wall St Screener. Each tool focuses on a different angle so you can match potential investments to your own risk tolerance and return goals.
- For investors who care most about resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can help you prioritise financial strength.
- If value is your priority and you want candidates trading below their estimated worth, filter for companies in the 32 high quality undervalued stocks and see which ones merit a closer look.
- When income is front of mind and you want higher yields with an emphasis on stability, shortlist ideas using our 6 dividend fortresses to focus on stronger cash return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com