


EN
Should Dividend Increase Require Action From Aflac (AFL) Investors?
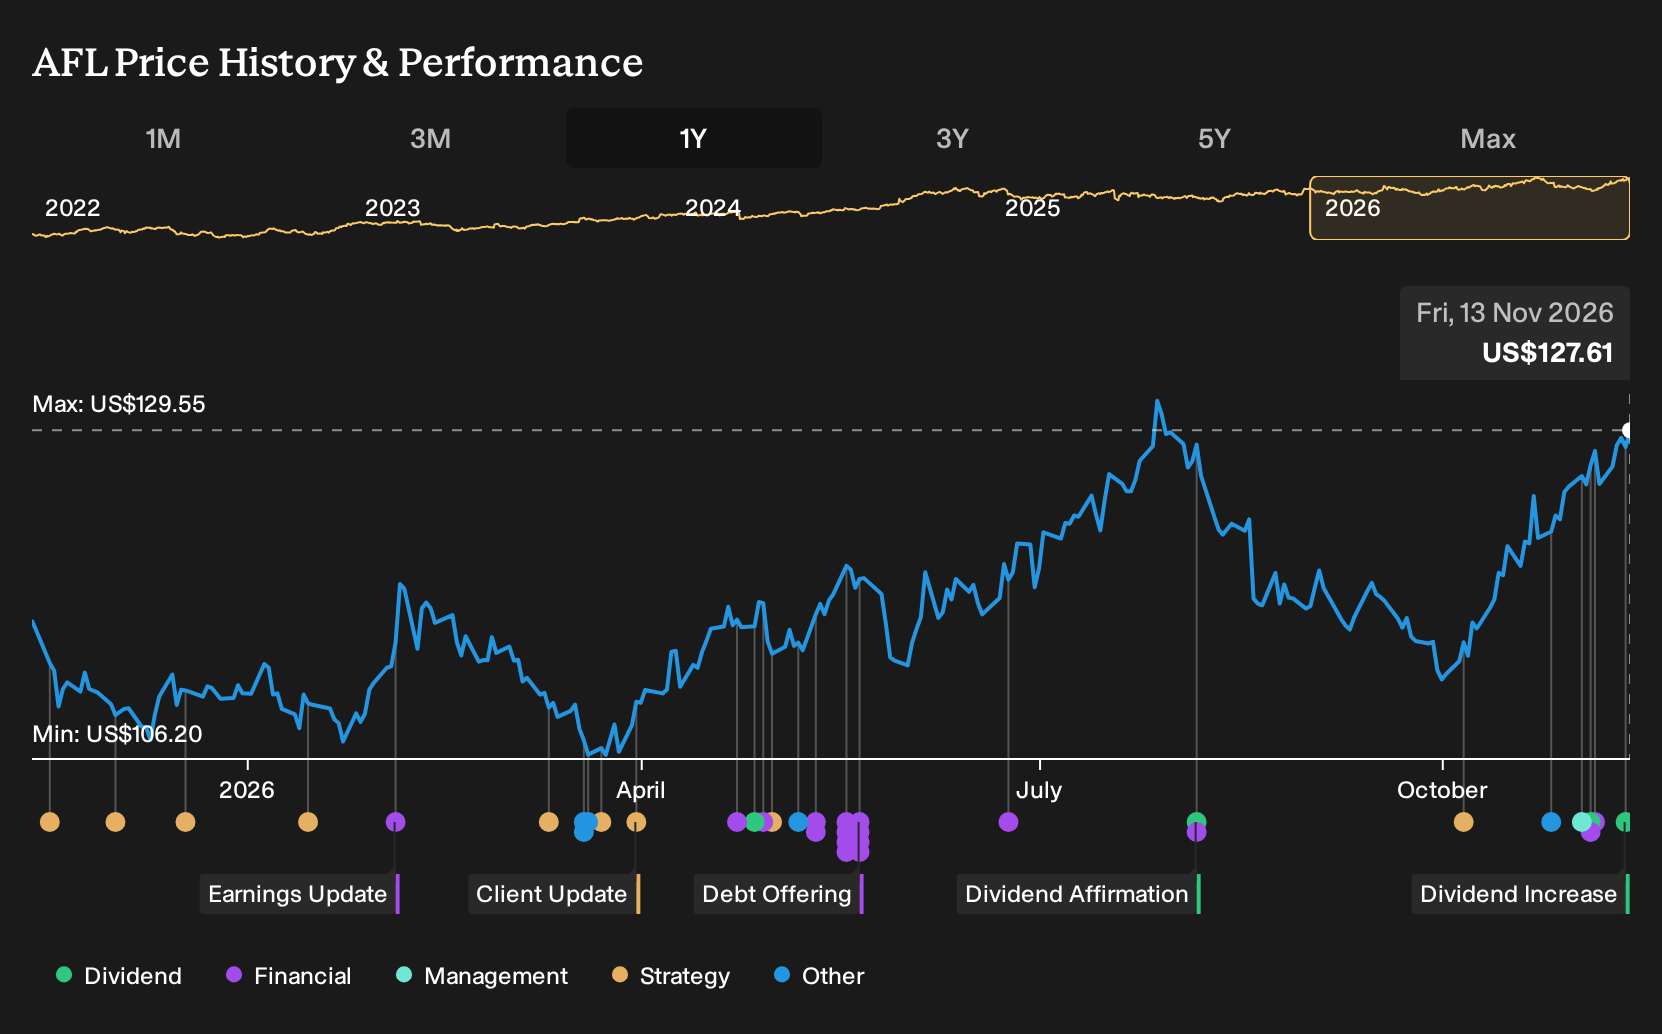
- Aflac raised its first quarter 2027 dividend to US$0.64 per share, a 4.9% uplift from the fourth quarter 2026 payout of US$0.61, with payment scheduled for March 1, 2027 to holders on record as of February 17, 2027.
- This higher cash return builds on Aflac's long track record of annual dividend increases and indicates management's focus on disciplined capital deployment alongside ongoing operations in Japan and the U.S.
- We will now look at how Aflac's 4.9% dividend increase could influence the existing investment narrative around capital returns.
Scan other dividend focused insurers moving on capital return stories like Aflac by reviewing the hand picked 6 dividend fortresses that investors are watching after payout updates.
Aflac Investment Narrative Recap
To own Aflac, you generally need to believe the Japan and U.S. insurance franchises can keep generating steady cash, even while premium trends and benefit ratios in Japan remain under pressure. The analyst consensus Narrative on Simply Wall St expects modest earnings growth, so the investment case leans heavily on consistent profitability and measured product growth rather than rapid expansion.
The 4.9% dividend uplift supports the idea that capital levels and cash flows remain comfortable in the near term, even after a quarter where revenue and net income were lower than the prior year. It does not change the key short term swing factors, which still appear tied to Japan premium trends, benefit ratios, and any fallout from the prior cybersecurity incident.
The most relevant recent update here is the third quarter 2026 earnings release. Revenue for the quarter was US$3,271 million compared to US$4,740 million a year earlier, with net income at US$303 million compared to US$1,639 million. Basic and diluted earnings per share from continuing operations were US$0.61 compared to just over US$3 a year before.
That step down in reported profit sits in the background as you weigh the dividend increase. The key question is whether portfolio repositioning, new savings products in Japan, and U.S. group benefits growth can offset pressure on Japan premiums and higher benefit ratios, as outlined in the analyst consensus Narrative on Simply Wall St. If those business levers do not deliver as expected, the main risk is that earnings and future capital return capacity come under strain.
Aflac's narrative projects US$17.4b revenue and US$3.6b earnings by 2029. This assumes revenue declines by 1.2% per year and earnings decrease by about US$1.3b from the current US$4.9b level.
Uncover why Aflac's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$118.5 to US$182.4 per share, which suggests that Aflac can appear either stretched or attractive depending on whose model you read. Consider this in the context of Japan premium and benefit ratio risks, as well as U.S. product expansion efforts, and it becomes clear why opinions diverge. Explore the full range of community views before deciding how this dividend story aligns with your own expectations.
Explore another Aflac fair value estimate, including one that suggests as much as 43% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aflac research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aflac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aflac's overall financial health at a glance.
Looking for more Aflac style investment ideas?
If this Aflac dividend update has you thinking more broadly about income, quality and risk, the Simply Wall St Screener can help you widen the field without losing focus on what matters to you.
- For investors who want a mix of quality and potential mispricing, start with a curated set of 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If balance sheet strength sits at the top of your checklist, filter for companies in the list of solid balance sheet and fundamentals (24 results) and see which ones match your risk comfort level.
- When you want fresh ideas that are not yet widely followed, scan the 20 high quality undiscovered gems to spot lesser known businesses with robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com