


EN
How Investors May Respond To Douglas Emmett Stock After Narrower Quarterly Loss
- Douglas Emmett reported third quarter 2026 results, with sales of US$224.14 million, revenue of US$260.86 million, and a net loss of US$8.79 million, which was a smaller loss than the same quarter a year earlier.
- Across the first nine months of 2026, Douglas Emmett generated higher sales and revenue than a year ago but moved from net income of US$23.11 million to a net loss of US$13.96 million, highlighting pressure on profitability even as top line figures increased.
- This article examines how Douglas Emmett's investment narrative aligns with higher revenue alongside a continued net loss in 2026.
Compare Douglas Emmett's latest loss-making quarter with other real estate stocks by reviewing list of solid balance sheet and fundamentals (24 results) for potential alternatives with stronger financial footing.
Douglas Emmett Investment Narrative Recap
To hold Douglas Emmett, you need to believe its coastal office and multifamily portfolio can convert higher leasing and redevelopment activity into consistent cash flow while absorbing higher interest costs. The latest quarter showed slightly higher sales and revenue alongside a smaller quarterly loss, so the operational story is not breaking, but profitability is still tight.
The clearest short term catalyst is execution on office leasing and the multifamily pipeline described in the analyst consensus Narrative on Simply Wall St. Stronger occupancy could support cash NOI and help offset funding costs. The biggest risk remains interest expense and refinancing at higher rates, which the continued net loss and 2026 loss guidance keep front and center.
The third quarter 2026 earnings update is the key reference point for you here. Douglas Emmett reported sales of US$224.14 million and revenue of US$260.86 million, with a quarterly net loss of US$8.79 million and a basic loss per share from continuing operations of US$0.05. These figures show how funding costs and office softness still weigh on results.
Across the first nine months of 2026, sales of US$659.25 million and revenue of US$768.37 million sat alongside a net loss of US$13.96 million and a basic loss per share from continuing operations of US$0.09. That mix keeps the focus firmly on execution of redevelopment projects, lease up of signed office deals, and interest coverage, since those areas link most directly to the catalysts and risks highlighted around occupancy, NOI and refinancing pressure.
Douglas Emmett's narrative projects US$1.1b revenue and US$74.6 million earnings by 2029, based on analyst estimates that assume 2.7% yearly revenue growth and an earnings increase of about US$99.1 million from current earnings of a US$24.5 million loss today.
Uncover why Douglas Emmett's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
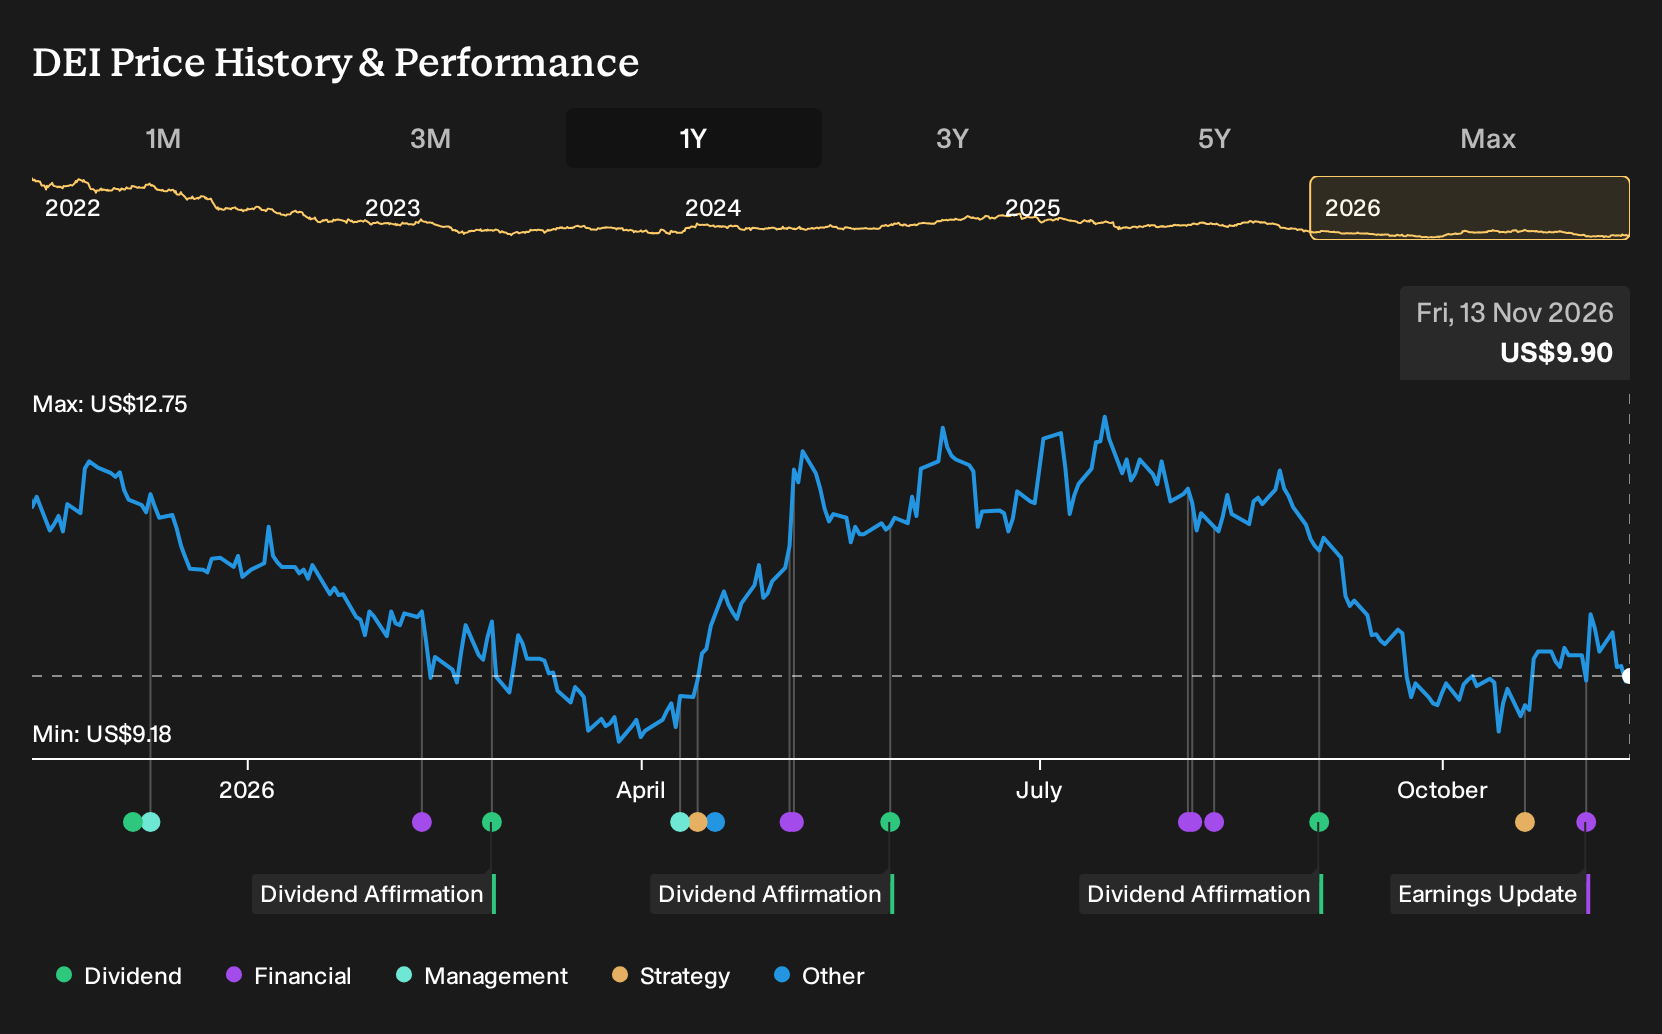
Exploring Other Perspectives
You just saw Douglas Emmett report a net loss, yet the lowest analysts were already focused on higher interest costs as the key risk before these numbers. They were only assuming about 2.2% yearly revenue growth and earnings of roughly US$99.0 million by 2029. That is a more cautious story than consensus, so treat this quarter as fresh input that could shift those views.
Explore 3 other Douglas Emmett fair value estimates, including one that suggests it could be worth just $10.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Douglas Emmett research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Douglas Emmett. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Douglas Emmett's overall financial health at a glance.
Looking for more Douglas Emmett style investment ideas?
If Douglas Emmett's mix of income potential, balance sheet questions, and forecast upside has you thinking more broadly about your portfolio, the Simply Wall St Screener can help you scan the market using a similar fundamentals driven lens.
- If capital preservation is near the top of your list, you can focus on steadier businesses by filtering for 31 resilient stocks with low risk scores that may better match your comfort with volatility.
- For readers looking for quality at a sensible entry point, you can target opportunities that combine fundamentals with pricing support by zeroing in on 32 high quality undervalued stocks that meet your own criteria.
- Income focused investors can look beyond Douglas Emmett and test different yield and payout profiles by reviewing 6 dividend fortresses that align with their cash flow goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com