


EN
CCL Industries (TSX:CCL.B) Could Be 7% Below Fair Value Following Record Q3 Results
CCL Industries (TSX:CCL.B) has just paired record third quarter results with a fresh board appointment, giving investors new information on both current financial performance and longer term leadership depth.
At a share price of CA$101.76, CCL Industries has enjoyed a 16.1% year to date share price return, alongside a 17.9% total shareholder return over the past year and an 83.3% total shareholder return over three years. This points to firm momentum that recent record results and the board refresh are helping to sustain.
Scan how CCL Industries compares with other industrials showing strong execution and resilient balance sheets by reviewing the hand-picked list of solid balance sheet and fundamentals (6 results) in the same spirit.
CCL Industries now blends strong execution, fresh board talent, and a powerful share price run. The open question is whether that quality story is already fully reflected in today’s valuation.
Most Popular Narrative: 7% Undervalued
On the analyst consensus Narrative on Simply Wall St, CCL Industries screens as modestly undervalued, with a fair value of CA$109.90 against the recent CA$101.76 close. That gap is tied directly to how analysts see earnings, margins, and future valuation multiples playing out from here.
The company's disciplined capital allocation, including a strong balance sheet, healthy free cash flow, regular share buybacks, and an increasing dividend, points to increasing returns to shareholders and bolsters EPS growth, supporting improved long-term valuation.
Strategic acquisitions and global footprint expansion continue to diversify CCL's customer base and geographic exposure, fostering operating leverage and risk mitigation while enabling them to penetrate higher-growth, higher-margin specialty end markets, driving earnings growth.
See why 15 investors see CCL Industries as 7% undervalued.
The narrative fair value of CA$109.90 implies around a mid single digit discount to the current share price, using a 6.44% discount rate to bring those future earnings assumptions back to today. That view also leans on consensus forecasts for revenue growth of about 4.7% a year and earnings moving to CA$963.1m by around 2029, as well as a future P/E of 21.6x that sits above the current 12.8x level for the Canadian packaging industry.
For you as an investor, the key judgment is whether those building blocks feel realistic. The assumptions bake in mid single digit top line growth, a slight lift in profit margins from roughly 10.3% to 10.6%, and ongoing share count reduction of about 2.4% a year, helped by large buybacks already reported. If you think CCL Industries can at least meet those hurdles, the narrative suggests there is some valuation cushion, but if you see slower earnings progress or lower future multiples, that perceived discount could narrow quickly.
Result: Fair Value of CA$109.90 (UNDERVALUED)
Still, CCL Industries faces two clear swing factors: tougher plastic regulations that could pressure returns on new plants, and slower RFID demand if apparel volumes stay weak.
Find out about the key risks to this CCL Industries narrative.
Another View: CCL Industries Looks Expensive On Earnings
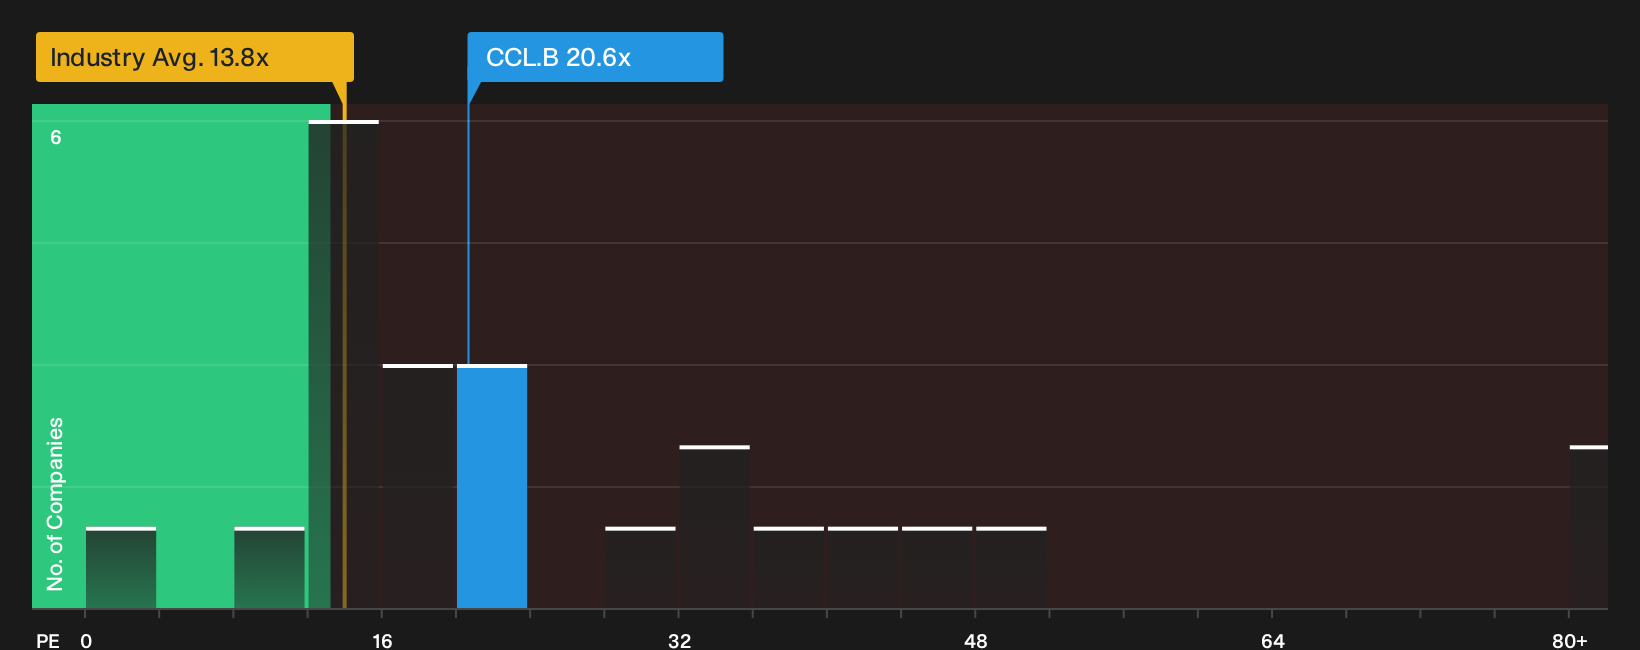
On the flip side of the fair value story, CCL Industries trades on a P/E of 20.6x, while the Canadian packaging group averages about 12.8x and close peers sit near 10.7x. The fair ratio points closer to 14.1x, which suggests meaningful valuation risk if sentiment cools.
That sizeable gap means investors are paying a premium earnings multiple despite forecasts that revenue and profit expansion sit below the broader Canadian market. The question is whether CCL Industries has enough earnings quality and balance sheet strength to justify that kind of premium over time, or whether the market could drift back toward the fair ratio.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on CCL Industries is clearly mixed, with both upside potential and real concerns on the table, so move quickly and interrogate the data yourself. To weigh those competing signals side by side, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CCL Industries?
If you stop with CCL Industries, you risk missing other opportunities that might fit your goals even better. Broaden the search before you commit.
- Target potential mispricings by scanning a curated 6 high quality undervalued stocks that highlights businesses combining solid fundamentals with prices that lag their underlying financial strength.
- Collect reliable income ideas by reviewing a focused 3 dividend fortresses built around companies offering higher yields with an emphasis on balance sheet support.
- Prioritise staying power in tougher markets by using a carefully filtered 9 resilient stocks with low risk scores that spotlights resilient operations and more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com