


EN
What SUSS MicroTec Holders Got Right
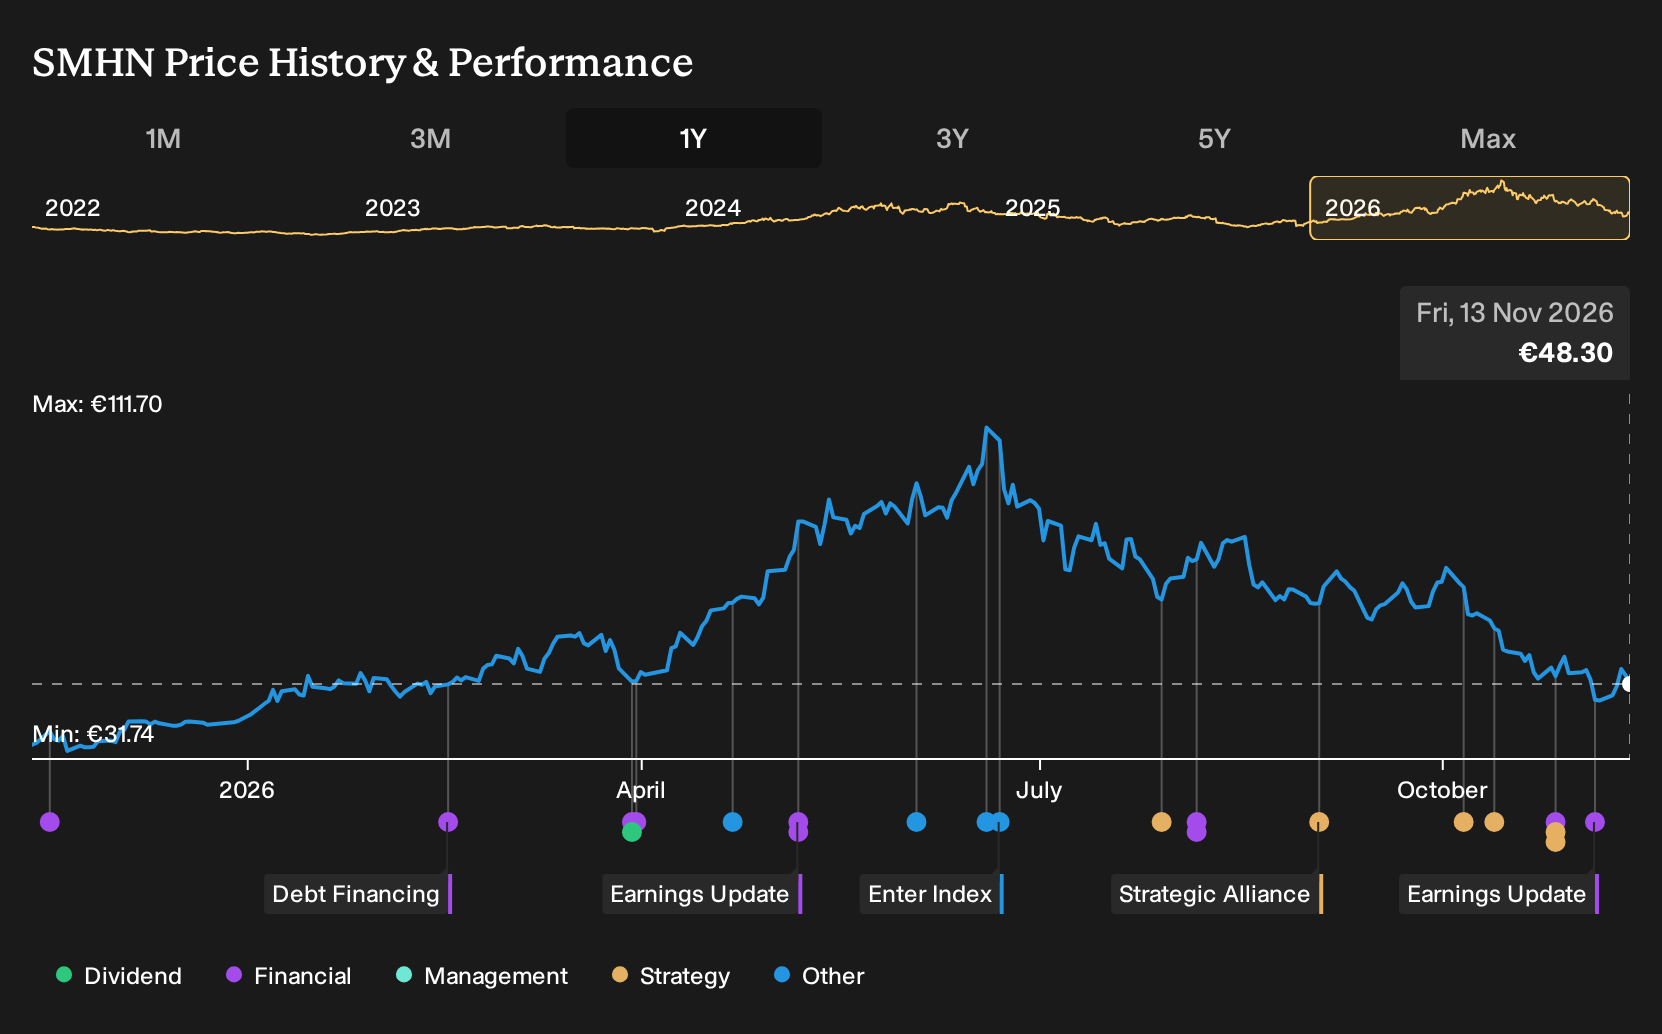
If you only skimmed the headlines, the eye catcher was SUSS MicroTec clearing the bar for MDAX inclusion while tightening its global production footprint in Taiwan and Germany. Investors who held SUSS MicroTec over the past year are up 43.0%, including dividends. If you were deciding on 13 November 2025 whether to buy, what would you have needed to believe about future margins, order momentum, and index status for that payoff to feel reasonable?
SUSS MicroTec has already moved. Pinpoint other ways to investigate the theme among 33 best rare earth metal stocks.
The Two Stories Investors Had To Choose Between On SUSS MicroTec
The shares cost €33.28 at the start of the period, and anyone looking at SUSS MicroTec then was really choosing between two very different futures.
On the optimistic side, the October 2025 bull Narrative saw a Fair Value of €44.91, a price implied by assumptions such as revenue growth of 1.2% a year and profit margins settling at 9.4%, with a future P/E of 21.3x.
The July 2025 bear Narrative pointed to a Fair Value of €30, based on expectations that revenue would decline 1.7% a year and margins would compress toward 7.9%, alongside an 18.6x P/E assumption.
What The Results Changed For The SUSS MicroTec Thesis
The clearest development was SUSS MicroTec joining the MDAX in June 2026, which supported the optimistic case that index status and scale could matter. The more challenging update came from the Q3 2026 report. Revenue declined from €118.968m to €97.041m and net margin moved from 9.2% to 1.5%. Taken together, these updates had mixed implications for the original narratives.
The whole episode turned on one assumption: that margins would remain close to the high single digits. When you evaluate a similar situation elsewhere, track net margin trends against any stated cost savings or footprint changes and compare guidance directly with reported profitability.
What SUSS MicroTec’s Recent Run Now Asks You To Believe
With SUSS MicroTec at €48.3 today, the analyst consensus Narrative on Simply Wall St sees Fair Value above that level. It is anchored on what happens next with its record order book and production reshuffle rather than on the recent one year gain of 43.0%.
The crux for any buyer now is whether SUSS MicroTec can turn that backlog and new tools into stronger margins after the current transition. The key assumption to test is that product refresh and manufacturing consolidation will lift profitability enough to outweigh near term cost pressure.
"The main thing that has to go right is that SUSS MicroTec executes on its product refresh and manufacturing consolidation while keeping R&D and capacity investments productive enough to offset near term margin pressure and restructuring costs."
One Narrative disagrees with today's price. → See where this Narrative says SUSS MicroTec should trade
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 46% below our estimate - uses a digital platform to win small business relationships and cross sell services.
- Company 2 - 38% below our estimate - converts a long contract backlog in secure systems into higher margin project delivery.
- Company 3 - 42% below our estimate - manages payment volumes for large merchants expanding into more local methods and channels.
Three companies from the same screener. Open all 197 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com