


EN
What Veeco Instruments (VECO) Earnings Guidance Means For Shareholders
- Veeco Instruments reported third quarter 2026 sales of US$209.38 million and net income of US$13.64 million, with earnings per share from continuing operations above the prior year on both a basic and diluted basis.
- The company paired these results with full year 2026 guidance that outlines specific revenue, operating income and net income ranges, giving investors clearer visibility into how current demand and cost decisions could flow through to reported earnings.
- We will now look at how Veeco Instruments' investment narrative is affected by this guidance after reporting higher quarterly earnings metrics.
Scan how Veeco Instruments' earnings guidance compares with other hardware and semiconductor players by looking through the hand picked 53 AI infrastructure stocks that are likely to experience similar spending trends.
Veeco Instruments Investment Narrative Recap
To own Veeco Instruments, you need to be comfortable with a story where AI, high performance computing and silicon photonics equipment remain key growth arenas, while near term earnings stay sensitive to mix and cost. The third quarter showed higher quarterly sales and income, but nine month net income and earnings per share from continuing operations were below the prior year, which keeps margin quality in focus.
The analyst consensus Narrative on Simply Wall St leans heavily on future earnings expansion, yet current profitability reflects extra operating expense, gross margin pressure from capacity plans and past one off items. The new full year guidance frames the short term catalyst as execution on that revenue range and earnings per share band, with the biggest immediate risk still tied to margins, export controls and whether added capacity is used efficiently.
The most relevant new disclosure is Veeco Instruments' updated outlook for the fourth quarter and full year 2026. Management is guiding to US$230 million to US$260 million of fourth quarter revenue, GAAP diluted earnings per share of US$0.34 to US$0.53 and operating income of US$24 million to US$39 million, with net income of US$23 million to US$36 million.
For the full year, guidance of US$790 million to US$820 million in revenue and GAAP diluted earnings per share of US$0.72 to US$0.92 sets a clearer bar for how the expansion in advanced packaging and photonics, Axcelis integration work and export constraints translate into reported profit. This range also matters for investors tracking whether forecast margin and earnings growth in the analyst consensus Narrative on Simply Wall St stays realistic against actual execution.
Veeco Instruments' current earnings of US$26.3 million are set against analyst expectations for revenue to grow 31.0% per year, with forecasts calling for US$1.6b of revenue and US$477.3 million of earnings by 2029. This would represent roughly an 18x increase in profit from today.
Uncover why Veeco Instruments' fair value indicates a 50% potential upside to its current price, which could narrow quickly.
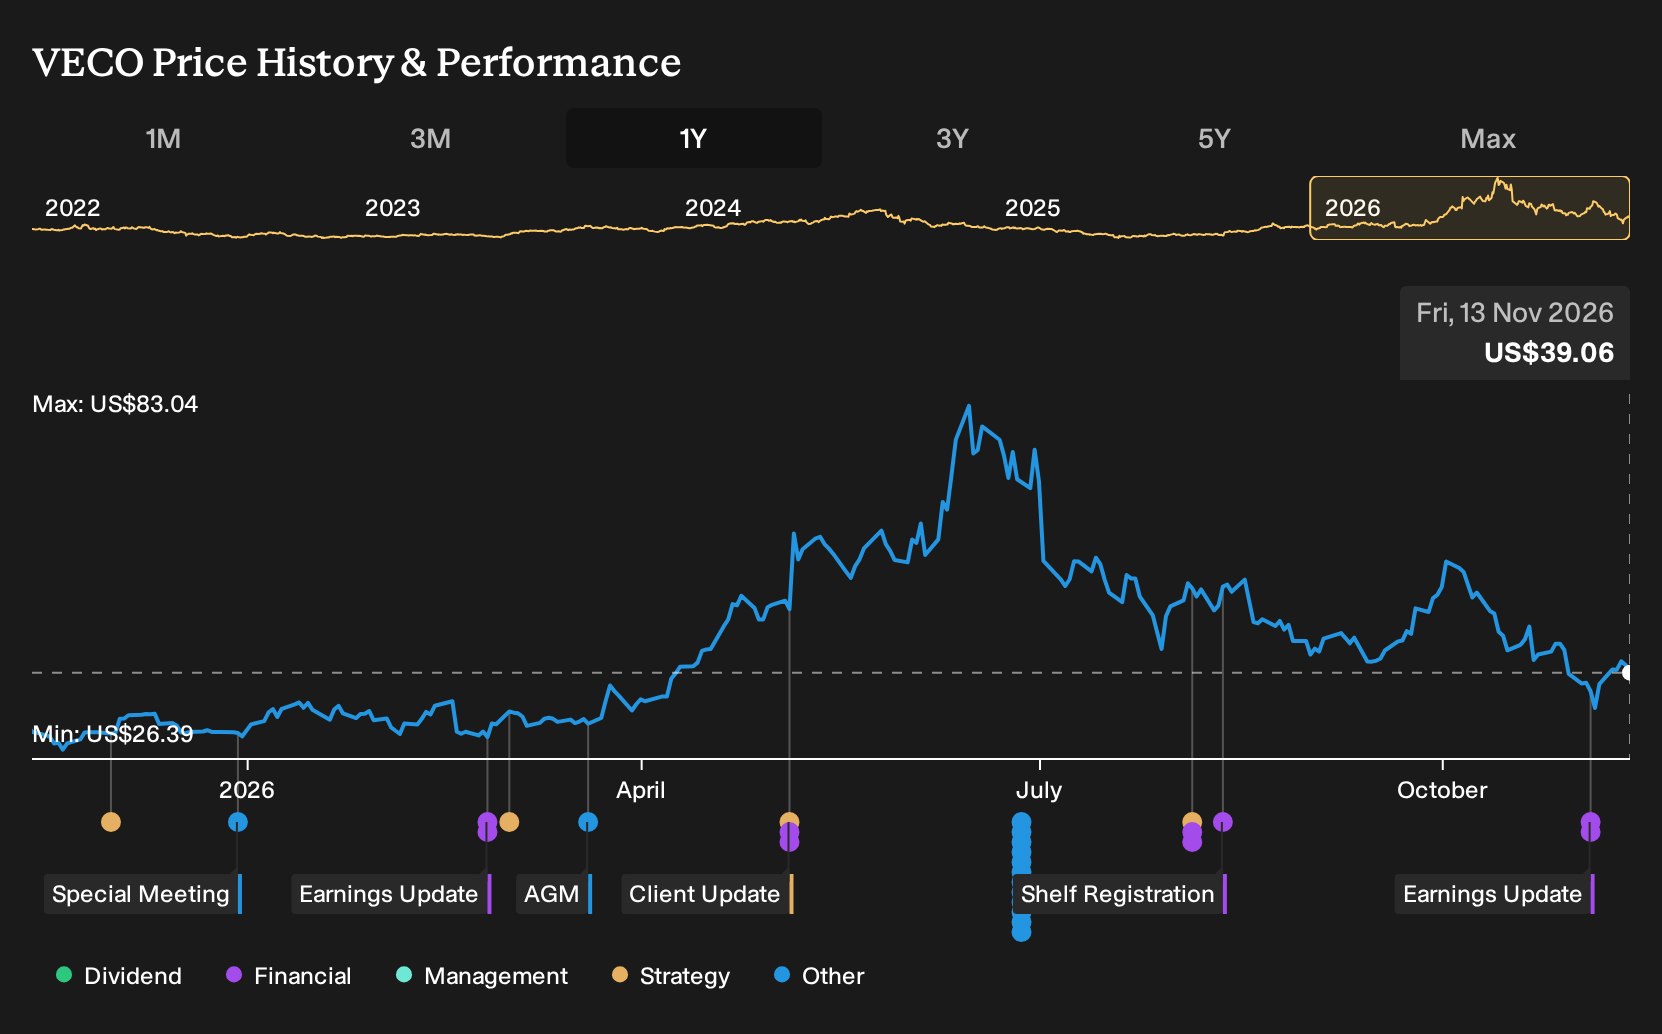
Exploring Other Perspectives
Bullish analysts frame Veeco Instruments as a backlog story rather than just a quarterly earnings story. Before this update, the most optimistic forecasts pointed to roughly US$1.7b of revenue and US$580.9 million of earnings by 2029, far above consensus. You can treat this new guidance as a fresh test of those higher expectations and compare several viewpoints.
Explore 4 other Veeco Instruments fair value estimates, including one that suggests as much as 69% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Veeco Instruments research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Veeco Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Veeco Instruments' overall financial health at a glance.
Looking for more Veeco Instruments style investment ideas?
Once you have formed a view on Veeco Instruments, it can help to compare that thesis with other opportunities that share similar quality signals or risk profiles. The Simply Wall St Screener lets you quickly filter for these kinds of traits instead of trawling through individual filings one by one.
- If you care most about resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (24 results) to see which businesses might offer a similar financial footing.
- If potential mispricing is what interests you, scan through a 32 high quality undervalued stocks that flags companies where quality metrics and market price appear out of sync.
- If you prefer to focus on opportunities the market pays less attention to, use a 20 high quality undiscovered gems to surface quieter stories that still show solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com