


EN
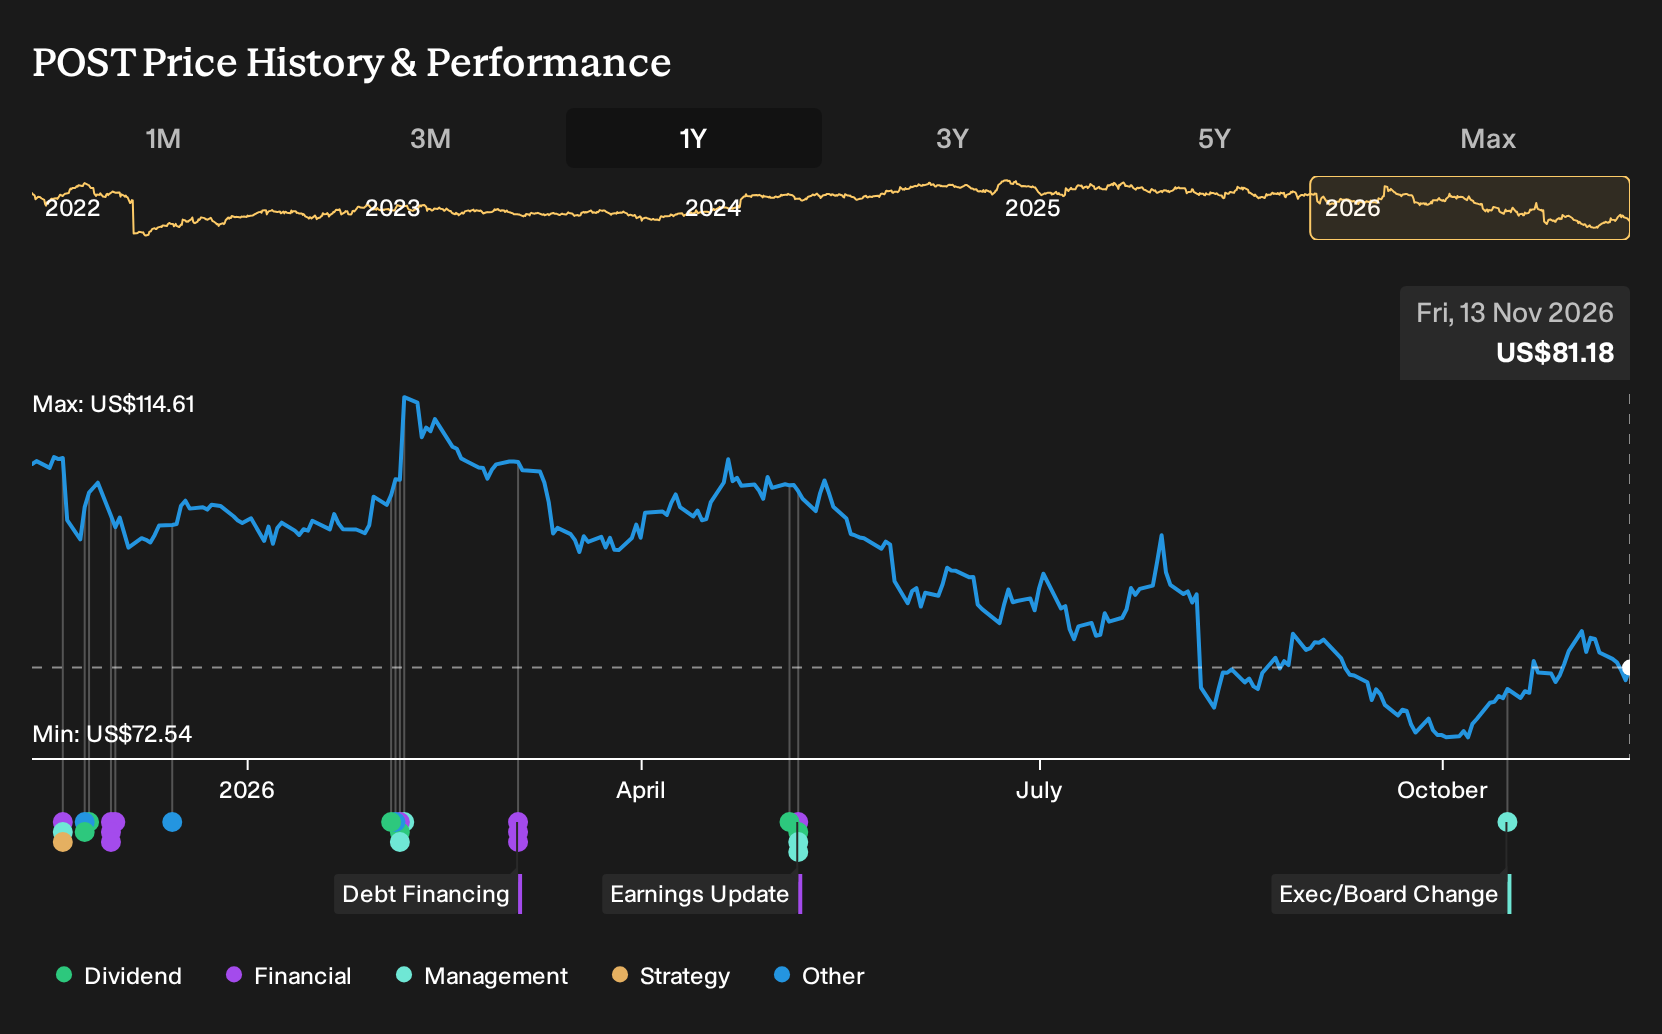
How Lower Earnings Expectations At Post Holdings (POST) Have Changed Its Investment Story
- Post Holdings is heading into its September 2026 quarter with analysts expecting earnings of $1.66 per share and lower year over year revenue, pointing to pressure on parts of its packaged food portfolio.
- Options activity has surged, with the December 18, 2026 $50 call showing high implied volatility. This signals that traders are bracing for a sharp move around this earnings update.
- We will now look at how Post Holdings' investment narrative could be influenced by the weaker earnings outlook flagged in recent estimates.
Balance potential downside in Post Holdings with a curated set of sturdier ideas by reviewing our 31 resilient stocks with low risk scores that have been filtered for resilience and lower risk scores.
Post Holdings Investment Narrative Recap
For a shareholder in Post Holdings, the core belief is that the mix of Foodservice eggs, refrigerated sides and cereals can keep generating steady cash even while some categories, like value pet food, stay under strain. The expected drop in September 2026 earnings and revenue highlights how fragile that balance is in the near term.
The key short term catalyst is whether Foodservice and cost savings from past plant closures can offset weaker categories and higher interest costs flagged in the analyst consensus narrative on Simply Wall St. The biggest risk is prolonged volume pressure and a flat adjusted EBITDA profile that makes the current cost and pet food turnaround work harder just to stand still.
The most relevant recent development is the weaker earnings outlook into the September 2026 quarter, with projected EPS of US$1.66 and year over year revenue pressure. That aligns with the risk that volumes stay soft while leverage remains in the mid 4x area and interest payments are not well covered by earnings.
Options pricing around the December 18, 2026 US$50 call points to expectations of a sharp price move. For investors, the practical question is whether the Foodservice egg run rate near US$500 million of adjusted EBITDA and ongoing portfolio and pet food work can reassert themselves as the dominant story, or whether the next few quarters are defined more by balance sheet and refinancing risk than by operational progress.
Post Holdings' current earnings are US$293.1 million, with analysts forecasting earnings of US$424.5 million on US$7.8b of revenue by 2029. This implies revenue declining 2.3% per year and an earnings increase of about US$131 million from today's level.
Uncover why Post Holdings' fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For a very different angle on Post Holdings, the lowest analysts focus heavily on pricing risk. They worry that inflation catching up to pricing later in fiscal 2027 could keep pressure on earnings, even while still modeling US$7.8b of revenue and about US$423.4 million of profit by 2029. Their view before the news is more cautious and worth comparing with the consensus before forming your own stance.
Explore another Post Holdings fair value estimate, including one that suggests it could be worth just $99.83!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Post Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Post Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Post Holdings' overall financial health at a glance.
Looking for more Post Holdings investment ideas?
If you want to balance your view on Post Holdings with other opportunities, the Simply Wall St Screener can help you quickly surface stocks that match different priorities, from resilience to income to valuation.
- For investors who care most about capital preservation and steadier risk profiles, review a 31 resilient stocks with low risk scores that have been filtered using a low risk score framework.
- If income is a priority and you want to focus on cash returns, scan a curated group of 6 dividend fortresses that have been selected for their higher yields.
- When you want to balance quality with the potential for a more attractive entry price, sort through a focused set of 32 high quality undervalued stocks that score well on both fundamentals and valuation checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com