


EN
Is CAVA Group (CAVA) Undervalued After Its Raised Sales Outlook And Restaurant Growth?
CAVA Group (CAVA) just paired its third quarter 2026 earnings release with fresh expansion news, reporting higher sales alongside an updated full-year outlook that leans heavily on new restaurant openings.
Against that backdrop, CAVA Group’s 1 month share price return of 12.87% suggests investors have been reacting positively to the latest earnings and expansion update, even though the 90 day share price return declined 21.75% and the year-to-date share price return is slightly lower at 3.83% down.
Compare CAVA Group’s expansion story with other fast-growing consumer stocks by scanning our hand-picked list of 20 high quality undiscovered gems before you decide where fresh capital should go next.
Bulls point to CAVA Group’s rapid restaurant rollout and raised sales outlook, while bears highlight the recent share price pullback and flat per share earnings. Which side does the current valuation support?
Most Popular Narrative: 27% Undervalued
CAVA Group’s last close at $58.23 sits below the analyst consensus Narrative fair value of $80.08, which reflects ambitious expansion and margin assumptions according to the analyst consensus Narrative on Simply Wall St.
Rapid geographic expansion into new and underserved markets, supported by strong new unit performance such as 2025 and 2026 cohorts tracking at or above 100% productivity and a public target of at least 1,000 restaurants by 2032, can continue to increase systemwide sales and support higher revenue and restaurant level profit dollars.
See why 73 investors see CAVA Group as 27% undervalued.
Result: Fair Value of $80.08 (UNDERVALUED)
Still, CAVA Group’s story can change quickly if food safety headlines resurface or if rapid unit growth stretches restaurant level execution too far.
Find out about the key risks to this CAVA Group narrative.
Another View: CAVA Group Looks Expensive On Earnings
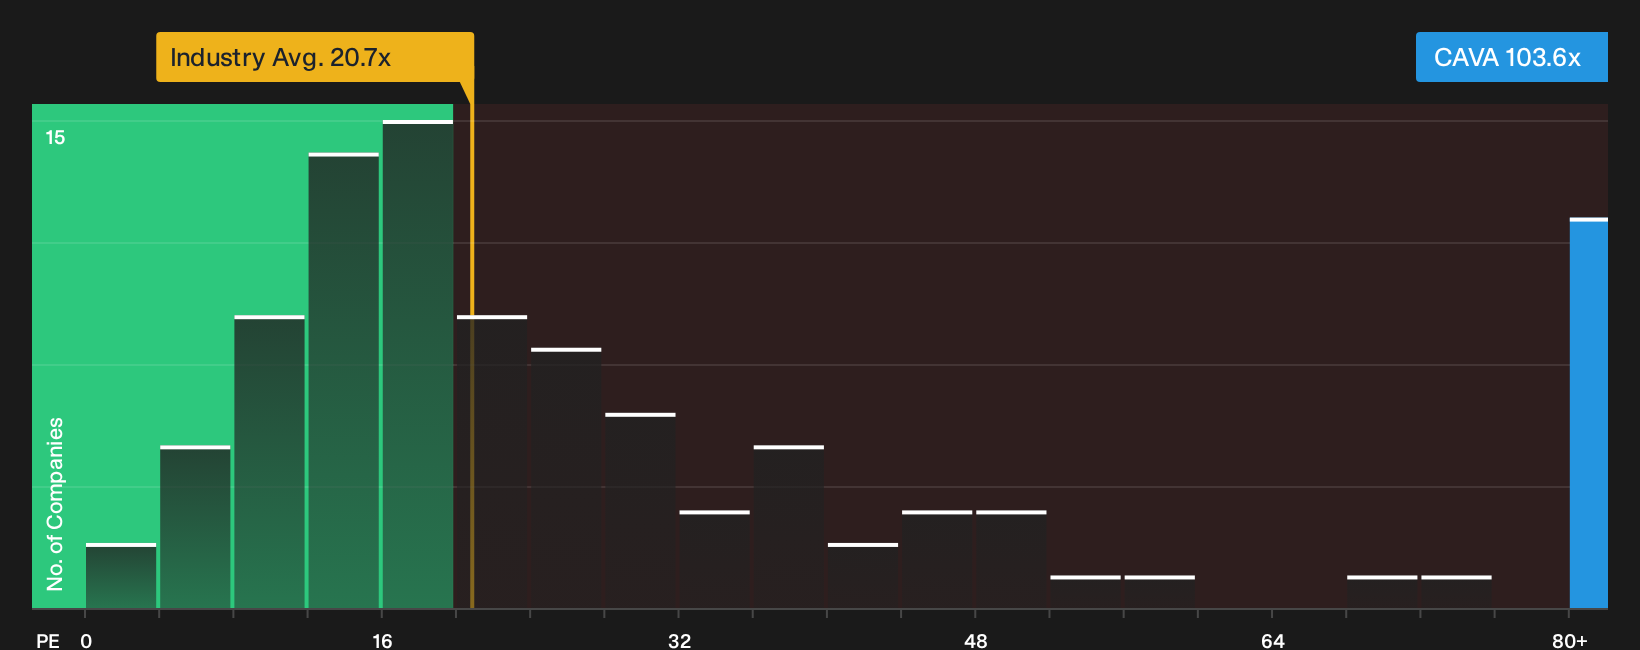
The narrative fair value of $80.08 and analyst target of $75.42 both imply upside for CAVA Group, yet the current P/E of 105.2x tells a different story. That multiple is more than double the peer average of 49x and far above the US Hospitality sector at 20.7x, while the fair ratio is 29x. For you, that gap points to meaningful valuation risk if sentiment cools or growth expectations soften.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on CAVA Group’s outlook can create both urgency and opportunity, so move quickly, review the underlying numbers, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond CAVA Group?
If you stop with CAVA Group, you only see one angle. Broaden your watchlist using targeted screeners that line up with your risk comfort and return goals.
- Target big upside potential with tighter financial filters by scanning a focused set of 13 elite penny stocks with strong financials that already clear quality hurdles.
- Prioritise value and resilience by zeroing in on companies that look mispriced on fundamentals through the 32 high quality undervalued stocks.
- Anchor your portfolio with steadier candidates by filtering for firms that pass balance sheet checks using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com