


EN
Is Monster Beverage (MNST) A Bargain Following Strong Earnings Growth?
Monster Beverage (MNST) is back in focus after its latest quarterly report, which paired higher sales and earnings with a US$19.9m impairment charge tied to property and equipment.
The latest move in Monster Beverage shares has been modestly positive, with a 1-day share price return of 1.95% and a 30-day share price gain of 5.07%. The 1-year total shareholder return of 30.30% and 5-year total shareholder return of 108.11% point to momentum that has built over time rather than suddenly appearing around this quarter’s impairment news.
See how Monster Beverage compares with other consumer names that have strong cash generation and balance sheets in our curated list of solid balance sheet and fundamentals (24 results).
Monster Beverage’s recent uptick follows earnings growth and an impairment charge landing in the same quarter, which raises a simple question: Are investors paying up for a stronger underlying business or just warming back to the stock’s story?
Most Popular Narrative: 7.5% Undervalued
Monster Beverage closed at $46.46, while the analyst consensus Narrative on Simply Wall St points to a fair value of about $50.24 based on discounted future earnings and cash flows using a 7.24% discount rate. That gap has helped frame the latest price move as part of a longer valuation debate rather than a reaction to one impairment line.
Strong double digit energy category value growth in regions such as APAC, EMEA and LATAM, combined with Monster Beverage’s 34.6% international net sales growth to US$1.16b in Q2 2026 and rising contribution from markets like China, India, Brazil and Mexico, is cited as supporting the view that continued international expansion can increase revenue and diversify earnings.
See why 73 investors see Monster Beverage as 8% undervalued.
Result: Fair Value of $50.24 (UNDERVALUED)
Still, the narrative can break if rising freight, fuel and aluminum costs squeeze margins faster than planned price moves and international expansion can offset.
Find out about the key risks to this Monster Beverage narrative.
Another View: Monster Beverage Looks Expensive On Earnings
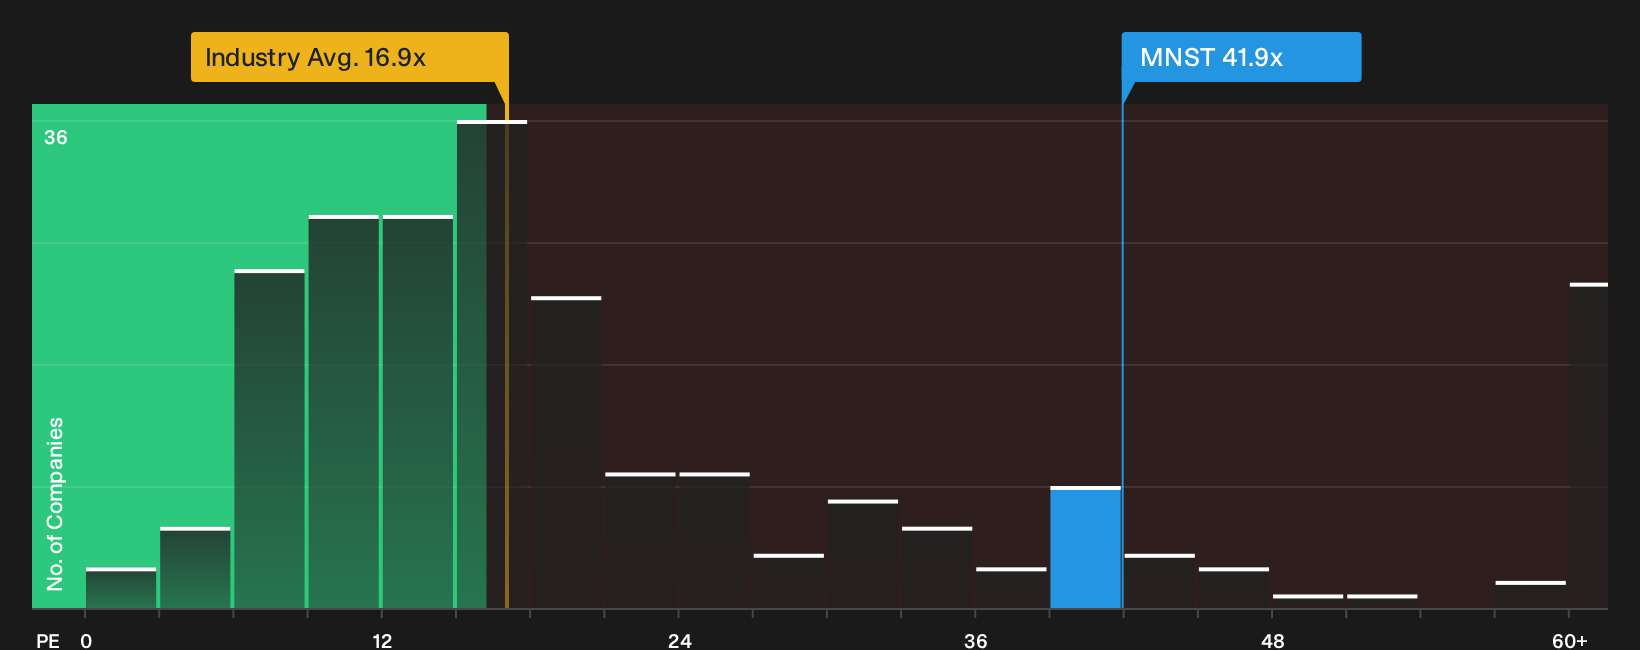
On the flip side of that 7.5% undervalued narrative, Monster Beverage trades on a P/E of 41.9x while the fair ratio sits at 25.4x. The Global Beverage industry sits at 16.9x and peers at 25.2x, which flags valuation risk if growth or margins slip even slightly.
When the market is paying this much more than the fair ratio and sector averages, how comfortable are you betting that the Monster Beverage story keeps justifying that premium?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Monster Beverage’s valuation are clear enough, so move quickly from headline takes to the underlying data and decide what feels justified for you. To see why some investors remain optimistic, review the 2 key rewards.
Looking for more investment ideas beyond Monster Beverage?
If Monster Beverage has your attention, do not stop here. Broaden your watchlist with fresh opportunities that match your risk, income, and value preferences.
- Target potential mispricing by scanning a curated set of 32 high quality undervalued stocks that pair solid cash generation with disciplined balance sheets.
- Lock in income-focused opportunities by reviewing companies in the 6 dividend fortresses that combine higher yields with consistent payout records.
- Reduce portfolio stress by concentrating on defensively positioned businesses in the 31 resilient stocks with low risk scores designed to keep overall risk levels in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com