


EN
AAON (AAON) Stock Looks Cheap Based On Current Earnings
AAON shares have delivered a 59.5% gain over the past 5 years, which puts a spotlight on a simple question for you as an investor. Is the current US$80.25 price tag still in line with what the business is earning today?
- The 59.5% return across 5 years means long term holders now need to decide whether that run is adequately backed by AAON's underlying earnings power.
- Record recent results driven by data center cooling and a stronger earnings profile can influence how much of AAON's current valuation reflects durable profitability versus shorter term momentum.
- Your read on AAON is one view; the desks covering it have another. See what analysts think AAON's shares could be worth.
The issue now is whether AAON's present share price is justified by its earnings when set against a Fair Ratio benchmark.
AAON's record data center cooling results and fast moving share price make it useful to compare this earnings story with other AI infrastructure opportunities using the 53 AI infrastructure stocks.
Is AAON a Bargain on Earnings?
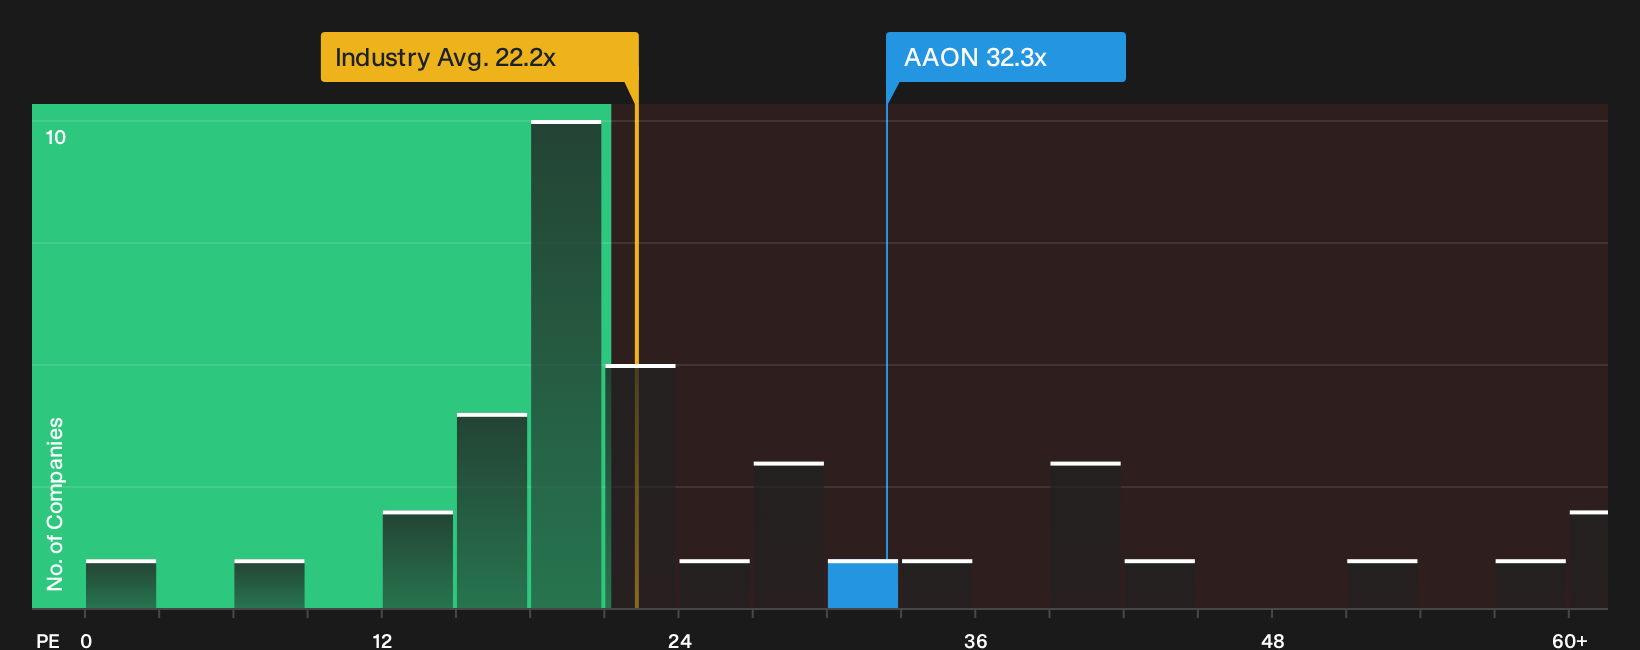
The P/E ratio fits AAON because earnings are now a key focus after the recent run in the share price. At roughly 32.3x earnings, the stock trades above the building industry average of about 22.2x, yet it sits below both the 33.9x peer group level and the tailored Fair Ratio benchmark that reflects AAON's growth profile and risk factors.
Because of the record Q3 2026 results in data center cooling, the current valuation suggests investors are paying a premium to the sector but not a premium to similar peers. This keeps the multiple in a range that many would still view as undervalued relative to that Fair Ratio benchmark. The gap implies the market has reacted to the recent performance but has not fully priced AAON in line with what this framework would suggest, so you need to decide whether the earnings quality and data center exposure justify that remaining uplift. Explore the numbers behind AAON's P/E valuation.
The AAON Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AAON pick up exactly where this valuation puzzle leaves you. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today's price. Each Narrative links a specific fair value estimate to a clear story about AAON's potential catalysts and key risks, so you can track over time which version of events is actually unfolding on the Community page.
One of the top narratives on AAON: 32% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that AAON turns rapid BASX data center growth, AAON brand share gains, and heavy capex into sustained margin expansion..."
Discover why this Narrative puts AAON at 32% undervalued.
One more AAON check that belongs beside the P/E
Price tells you what AAON costs today, but analyst models sketch where the business might be a few years out and give you a different yardstick to compare with this snapshot. Explore where analysts expect AAON to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com