


EN
Jacobs Solutions (J) Could Be 3% Undervalued On New Infrastructure Contract Wins
Jacobs Solutions (J) has just landed two substantial transport and aviation planning mandates: a 25 year master plan for Cochin International Airport in India and design work on New Zealand's Northland Corridor highway program.
These wins come as Jacobs Solutions trades at US$158.23, with the share price up 16.9% year to date and a 30 day share price return of 11.43%. The 3 year total shareholder return of 45.20% points to momentum that has built over a longer stretch, even though the 1 year total shareholder return of 3.57% has been more muted.
Scan other infrastructure focused contractors that are experiencing similar contract momentum using our hand picked 43 power grid technology and infrastructure stocks as a starting universe alongside Jacobs Solutions.
After a sharp 30 day move and fresh project wins in India and New Zealand, does Jacobs Solutions still offer enough upside to justify the risk, or is most of the easy money already reflected in the current price?
Most Popular Narrative: 3% Undervalued
Set against Jacobs Solutions' last close at $158.23, the analyst consensus Narrative on Simply Wall St points to a fair value of about $162.53. This suggests a small valuation gap that the narrative links to contract visibility and margin targets.
Record backlog of about US$29b with a trailing 12 month book to bill of 1.4x on gross revenue and 1.2x on net revenue points to multi year conversion of existing awards into revenue growth that many investors may not be fully pricing into Jacobs Solutions earnings power.
See why 22 investors see Jacobs Solutions as 3% undervalued.
Result: Fair Value of $162.53 (UNDERVALUED)
Still, Jacobs Solutions leans heavily on government infrastructure budgets and fast growing AI related work. Any pullback in awards or funding could quickly challenge this upbeat story.
Find out about the key risks to this Jacobs Solutions narrative.
Another View on Jacobs Solutions Using Earnings Multiples
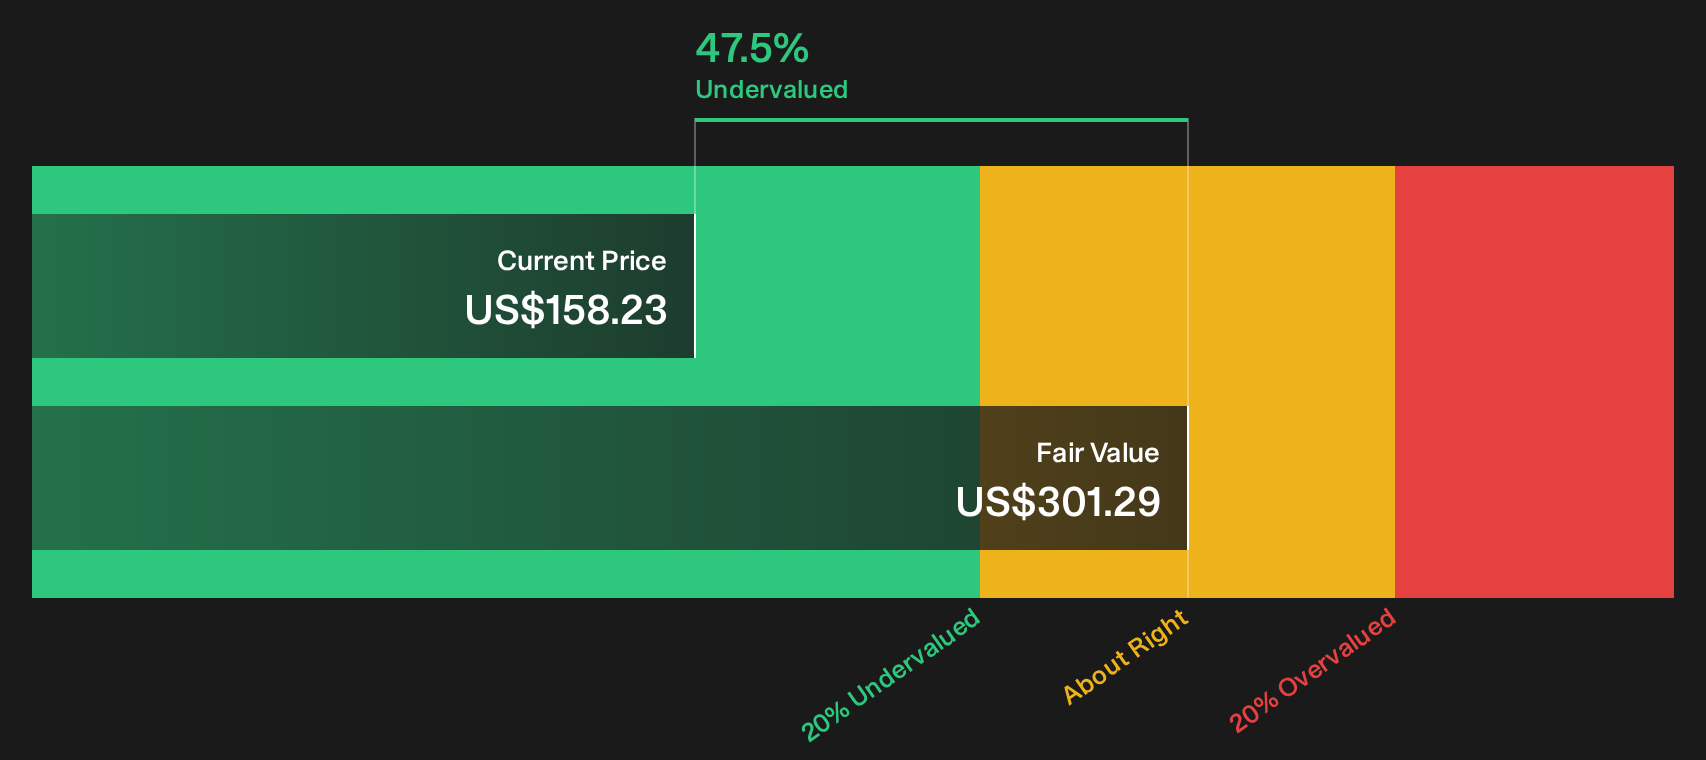
The SWS DCF model presents Jacobs Solutions as attractively priced against its estimated future cash flows, with the shares trading at a 47.5% discount to a modeled value of $301.29. However, the current P/E of 51.5x is more than double the US Professional Services industry on 22.7x and is also above the 34.1x fair ratio that the market could move toward. That gap highlights potential valuation risk if sentiment cools before the long term cash flow story fully plays out. This raises the question of which signal to give more weight to when sizing any position.
Before relying too heavily on either signal, it is worth understanding exactly how the SWS DCF model arrives at that $301.29 figure and what would need to hold true for Jacobs Solutions over time for that output to remain intact. Look into how the SWS DCF model arrives at its fair value.
For readers who prefer to visualise how the current share price compares with that modeled value on a simple chart, the latest DCF snapshot for Jacobs Solutions provides a clear side by side view.
Next Steps
Views on Jacobs Solutions in this article lean cautiously optimistic, yet the data can point either way if you examine it closely and act while sentiment is still settling. To see how the upside case compares with the concerns that other investors are flagging, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Jacobs Solutions?
If you want a broader watchlist alongside Jacobs Solutions, use these curated screeners to spot opportunities you might otherwise overlook.
- Target resilient income by reviewing companies in the 6 dividend fortresses that aim to pair higher yields with balance sheet support.
- Pursue valuation upside by scanning the 32 high quality undervalued stocks and compare how other stocks stack up on quality and pricing.
- Lower your downside risk by filtering for companies in the 31 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com