


EN
What ArcBest (ARCB)'s Third Quarter Earnings Rebound Means For Shareholders
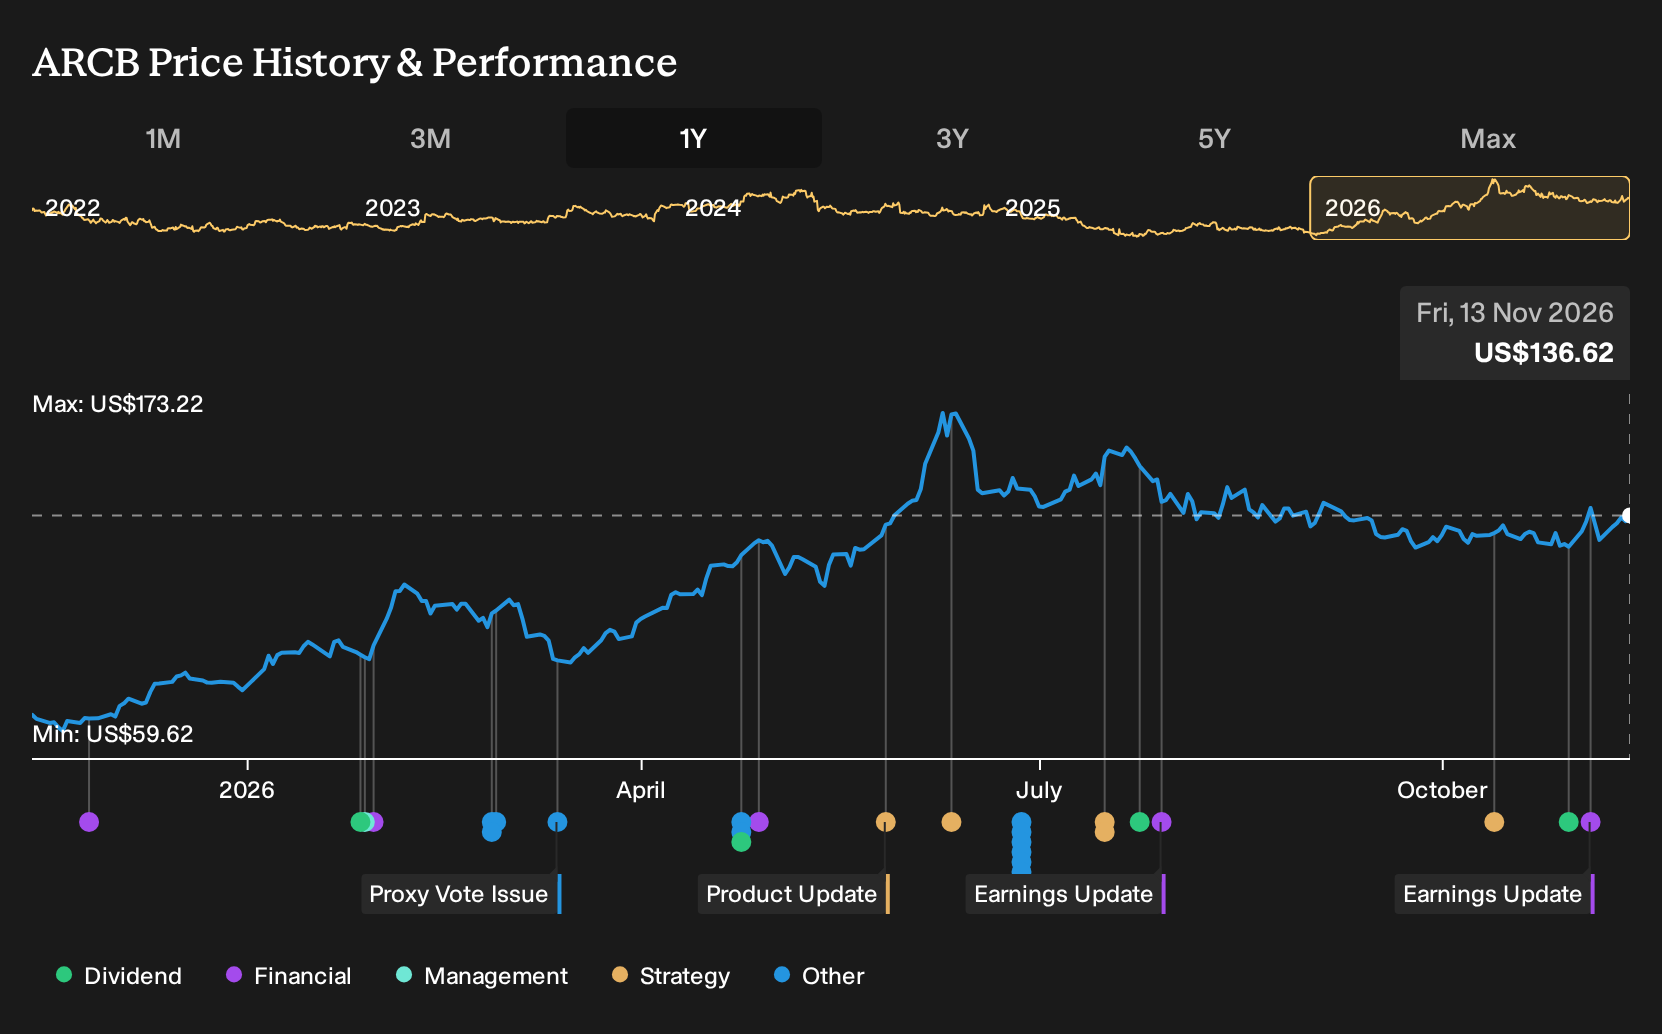
- ArcBest reported third quarter 2026 results with sales of US$1,210.5 million and net income of US$51.66 million, alongside higher basic and diluted earnings per share from continuing operations than a year earlier.
- An interesting tension for ArcBest is that nine month sales reached US$3,393.82 million, while net income and earnings per share from continuing operations were lower than the prior year period. This highlights how recent quarterly strength contrasts with softer year to date profitability.
- We will examine how ArcBest's investment narrative around efficiency and asset light growth is affected by the third quarter earnings rebound.
Compare ArcBest's earnings rebound with peers by scanning 32 high quality undervalued stocks that pair stronger balance sheets with profitability metrics investors often watch closely in trucking and logistics stocks.
ArcBest Investment Narrative Recap
To own ArcBest, you need to believe the freight cycle eventually rewards the work going into efficiency, technology and asset light services. The third quarter rebound in sales and earnings per share supports that narrative at the quarterly level. The analyst consensus Narrative on Simply Wall St still hinges on execution around cost savings and mix, and this update does not change that core requirement.
The short term swing factor is whether muted freight demand and heavier mix remain a drag on margins, despite the healthier quarter. The biggest risk is that pricing and claims costs erode the benefit of digital tools, restructuring and network consolidation before the freight backdrop improves.
With no fresh corporate announcements alongside the numbers, the most relevant reference point is the cost and network program already flagged in the analyst consensus Narrative on Simply Wall St. That framework points to about US$40 million of targeted annualized savings by early 2027 from terminal changes, brand consolidation and workforce actions.
The third quarter earnings recovery gives you a live test of how well ArcBest converts that kind of efficiency work into profit when conditions are still mixed. For catalysts, the key watch items now are consistency in Asset Based yield, continued growth in Asset Light activity and whether insurance and claims stay contained enough for those planned savings to show up in cleaner net income.
ArcBest's narrative projects US$5.4b revenue and US$426.4 million earnings by 2029. This implies 8.8% yearly revenue growth and a very large earnings increase from US$16.3 million today to the consensus forecast of US$426.4 million.
Uncover how ArcBest's fair value indicates a 24% potential upside to its current price that could narrow quickly if sentiment toward ArcBest shifts.
Exploring Other Perspectives
One alternate view on ArcBest focuses on digital disruption risk. The most cautious analysts worry that freight platforms and AI tools squeeze pricing power, so they were only modeling about US$5.2b of revenue and US$395.2 million of earnings by 2029. Those projections were set before this earnings surprise, so you might see opinions shift as fresh data lands.
Explore 2 other ArcBest fair value estimates, including one that suggests as much as 43% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ArcBest research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ArcBest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcBest's overall financial health at a glance.
Looking For More Investment Ideas Beyond ArcBest?
Once you have a view on ArcBest, it often helps to broaden the watchlist and compare similar risk and return profiles across the market using the Simply Wall St Screener.
- Prefer companies with steadier price moves and fewer shocks to the business model? Then scan a set of 31 resilient stocks with low risk scores that might better match your comfort level.
- If balance sheet resilience is a priority, focus on firms backed by a list of solid balance sheet and fundamentals (24 results) that can support operations through tougher freight or macro conditions.
- For investors who want a mix of quality metrics and potential mispricing, filter through a 20 high quality undiscovered gems that may not yet be widely followed by the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com