


EN
Everpure (P), Why Is The Stock Getting Attention Today?
Everpure (P) is back in focus after fresh Wall Street projections pointed to quarterly earnings of $0.77 per share and US$1.33b in revenue, with product and subscription lines expected to show strong year-over-year gains.
Recent trading shows how expectations are feeding into Everpure’s valuation story. The share price has fallen 23.7% over the past 30 days yet remains up 56.5% year to date. The 1-year total shareholder return of 27.7% and 3-year total shareholder return of roughly 2x suggest longer term momentum is still intact.
Spot similar momentum and potential in other data infrastructure players by scanning our curated list of 53 AI infrastructure stocks.For Everpure, a 23.7% slide in a month alongside strong earnings projections tells two very different stories. As you assess valuation next, are you pricing in weaker fundamentals or simply moderating enthusiasm?
Most Popular Narrative: 29% Undervalued
Everpure’s last close at $107.99 sits well below the analyst consensus Narrative fair value of $151.11, which is built on detailed revenue, earnings and cash flow forecasts in the analyst consensus Narrative on Simply Wall St that uses an 8.51% discount rate.
The adoption of Everpure’s Enterprise Data Cloud architecture and software-defined solutions is still building, as enterprises respond to AI driven data growth and management. This describes a core storage market that is expanding in value through 2030 and can support higher storage revenue over time.
Co engineering relationships and design wins with top hyperscalers have progressed, with Everpure now holding supply agreements with two top 5 hyperscalers for DirectFlash solutions that are expected to ramp from minimal contribution in FY27 to materially larger exabyte volumes in FY28 and beyond, with product gross margins in the range of 75% to 85%.
See why 138 investors see Everpure as 29% undervalued.
Result: Fair Value of $151.11 (UNDERVALUED)
Still, if chip costs stay elevated or core system volumes remain weak while pricing power fades, the Everpure narrative could shift far quicker than bulls expect.
Find out about the key risks to this Everpure narrative.
Another View: Everpure on Earnings Multiples
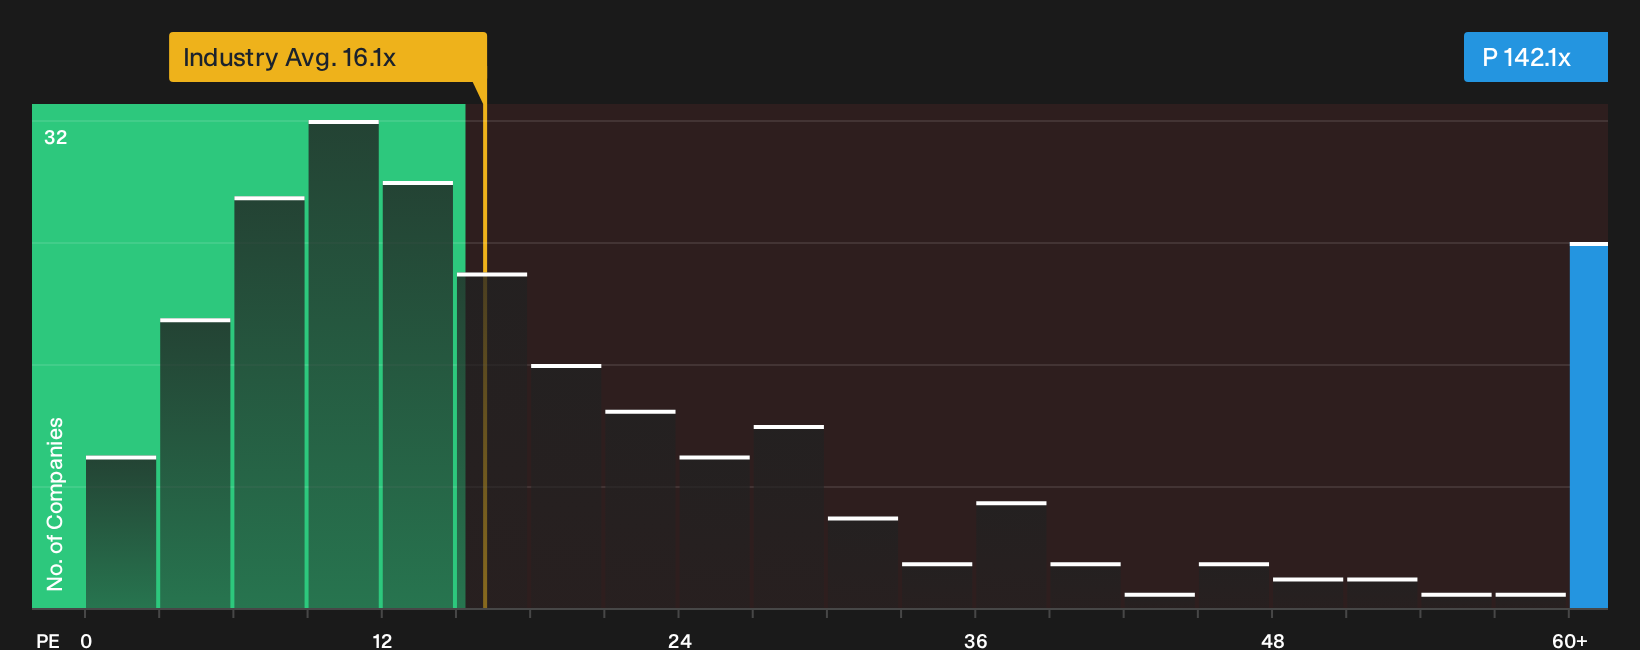
DCF inputs indicate that Everpure may be trading well below an estimated future cash flow value, yet the earnings multiple suggests a very different picture. The stock changes hands at a P/E of 142.1x, compared with 17.8x for peers, 16.1x for the wider tech group and a fair ratio of 47.2x that the market could move toward. Is this a mispriced growth story, or is a lot of optimism already reflected in the current price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Everpure can be exciting or unsettling, so look at the data yourself and move quickly while sentiment is still forming. To frame that view with both caution and optimism, weigh up the 3 key rewards and 2 important warning signs.
Looking for more Everpure sized investment ideas?
You have seen how one stock can polarize opinion. Now widen your opportunity set with a few focused screens that surface very different types of potential.
- Target resilient compounding potential by scanning a 6 dividend fortresses that aims to balance income with staying power when conditions change.
- Hunt for quality at a measured entry point by reviewing a 32 high quality undervalued stocks that filters for fundamentals first instead of headline excitement.
- Tilt your watchlist toward durability by checking a 31 resilient stocks with low risk scores that prioritizes lower risk scores so setbacks hit your portfolio less hard.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com