


EN
How NCAA Beer Deal At Constellation Brands (STZ) Has Changed Its Investment Story
- Constellation Brands announced that Modelo will become the first Official Beer Partner of the NCAA, gaining exclusive beer-category rights across more than 90 men's and women's college championships and planning a dedicated March Madness advertising push.
- The NCAA partnership gives Constellation Brands a fresh way to put marketing spend directly in front of college sports fans, which could help support volumes and reinforce the operator mindset that relies on brand strength rather than new brewery buildouts.
- We will now see how Constellation Brands' investment narrative could be influenced by Modelo's exclusive NCAA college championships partnership.
Scan how Constellation Brands stacks up against hand-picked peers by reviewing 32 high quality undervalued stocks that share solid fundamentals with room for a potential breakout.
Constellation Brands Investment Narrative Recap
To own Constellation Brands, you need to believe the operator mindset in beer can keep doing the heavy lifting while Wine & Spirits gradually stops dragging on margins. The analyst consensus narrative on Simply Wall St assumes modest revenue and earnings growth, helped by past cost savings and a focus on high quality earnings rather than big capacity expansions.
Right now, the key near term swing factor is beer volumes and pricing against a stretched consumer, especially Hispanic drinkers in key states. The biggest risk is that Wine & Spirits margins stay stuck near 5% to 6% while new tariffs and high debt keep pressure on earnings. The recent NCAA deal does not materially change those near term pressures by itself.
The NCAA partnership for Modelo looks most relevant to those catalysts. Management is trying to close Modelo’s awareness and distribution gap versus domestic beers, and March Madness is a direct shot at that opportunity. If the campaign lands with college sports fans, it could support the volume runway that underpins the current beer centric profit story.
Your focus, though, probably stays on execution and cost discipline. Constellation Brands has already booked more than US$600 million of efficiency gains, carries a high level of debt, and still faces softer Wine & Spirits channels. The question is whether brand building like the NCAA deal, combined with past savings, can offset tariff risk and any further pullback in beer spending.
Constellation Brands' current analyst narrative points to forecast revenue of US$9.5b and consensus earnings of US$2.1b by 2029. This implies annual top line growth of about 1.2% and an earnings increase of roughly US$0.2b from US$1.9b today.
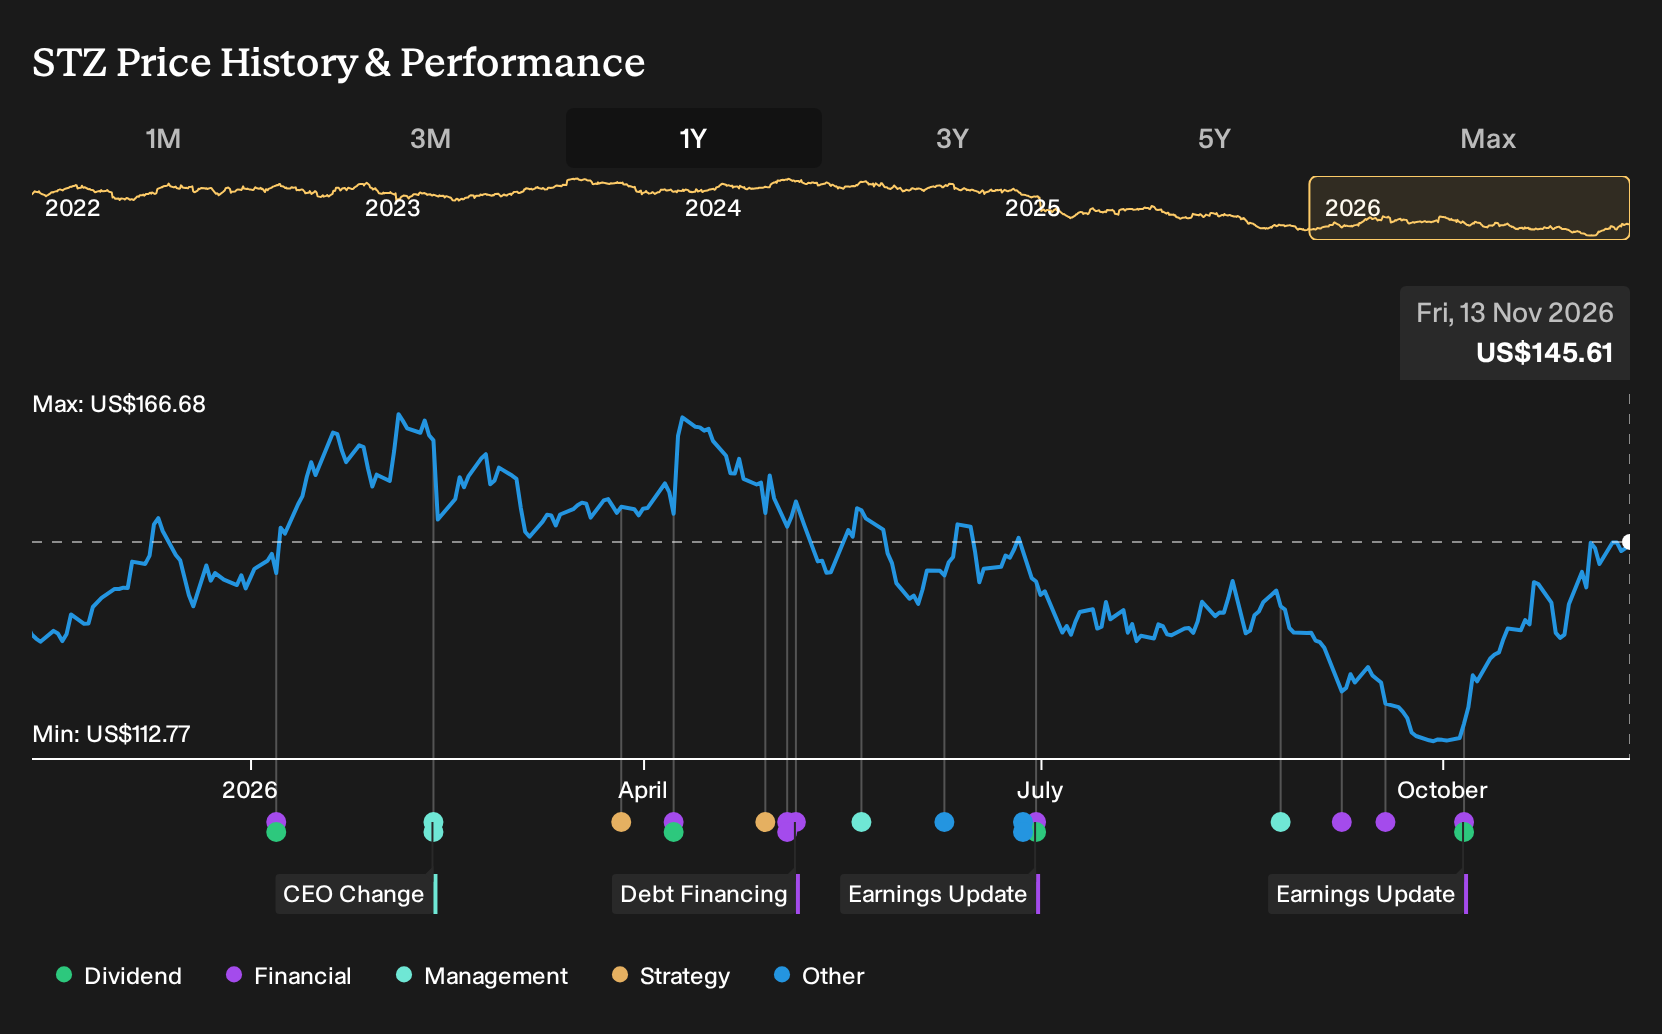
Uncover why Constellation Brands' fair value indicates a 4% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the lowest Constellation Brands forecasts lean into marketing cost risk instead of NCAA upside. Those analysts were penciling in revenue of about US$8.8b and earnings near US$1.7b by 2029, which is far below consensus. You can treat the new Modelo deals as a live test of which story deserves more weight.
Explore 6 other Constellation Brands fair value estimates, including one that suggests as much as 29% downside from the current price.
Reach Your Own Conclusion
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Constellation Brands research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Constellation Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Constellation Brands' overall financial health at a glance.
Looking for more Constellation Brands style investment ideas?
If this Constellation Brands breakdown helped sharpen your thinking, you can use the Simply Wall St Screener to hunt for other opportunities that match your risk profile and income needs.
- If capital preservation comes first for you, start with a group of resilient businesses by scanning 31 resilient stocks with low risk scores that aim to keep volatility in check.
- If balance sheet strength is non negotiable, narrow your watchlist with a focused list of solid balance sheet and fundamentals (24 results) so you are only comparing companies with sturdier foundations.
- If you want ideas with quality fundamentals that the market may not fully appreciate, broaden your opportunity set by checking out a curated pool of 20 high quality undiscovered gems that could be flying under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com