


EN
Dell (DELL) Stock May Be 45% Undervalued Despite AI Backlog News
Dell Technologies has ridden an extraordinary multi‑year share price run, and with the stock now around US$344, the question is whether that market value lines up with the cash the business is expected to generate. Recent headlines around artificial intelligence servers and data center demand add more noise. The real issue for you is what the underlying cash flows justify.
- Over the past 5 years Dell Technologies has delivered a very large share price gain. That puts real pressure on the story that future cash flows can keep carrying that valuation.
- The reported US$95b backlog of AI server orders and a series of AI and high performance computing projects may support expectations for stronger cash generation, but it also concentrates a lot of the valuation narrative in one part of the business.
- If you'd rather focus on earnings, this one's for you. See what Dell Technologies's 19.3x P/E says about the price.
The issue now is whether the current share price of Dell Technologies is appropriately supported by its projected cash flows when you look at an intrinsic value estimate built from a Discounted Cash Flow (DCF) model.
You can stress test this same AI hardware and data center story across a wider field of companies by scanning the 53 AI infrastructure stocks.
Is Dell Technologies a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here projects the cash Dell Technologies could return to shareholders over time and discounts it back to today. Latest twelve month free cash flow sits at about $8.2b, and the model uses this as a base for a stream of future cash generation that is modeled to grow rather than shrink.
Analysts contributing to this DCF are forecasting rising free cash flow over the next decade, with estimates reaching into the low $20b range by 2031, followed by more moderate expansion. That modeled path for cash flows helps explain why the intrinsic value outcome from the model is substantially above the current share price of $344.53. The recent Texas data center permit risk, which coincided with a sharp share price move in early November 2026, also helps explain why the price may lag what these cash flow projections indicate. Find out what Dell Technologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Dell Technologies Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take that valuation puzzle around Dell Technologies and spell out the specific future paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today on the market, and they sit on the Community page. Where a single ratio or DCF output gives you one figure, these storylines unpack the future those numbers rely on so you can see over time whether reality matches the premise.
One of the top narratives on Dell Technologies: 42% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers imply that Dell Technologies' current share price already reflects a bullish view on its AI driven growth and operating leverage, so the stock is fairly valued on this narrative..."
Discover why this Narrative puts Dell Technologies at 42% undervalued.
Dell Technologies: the share price is only one signal
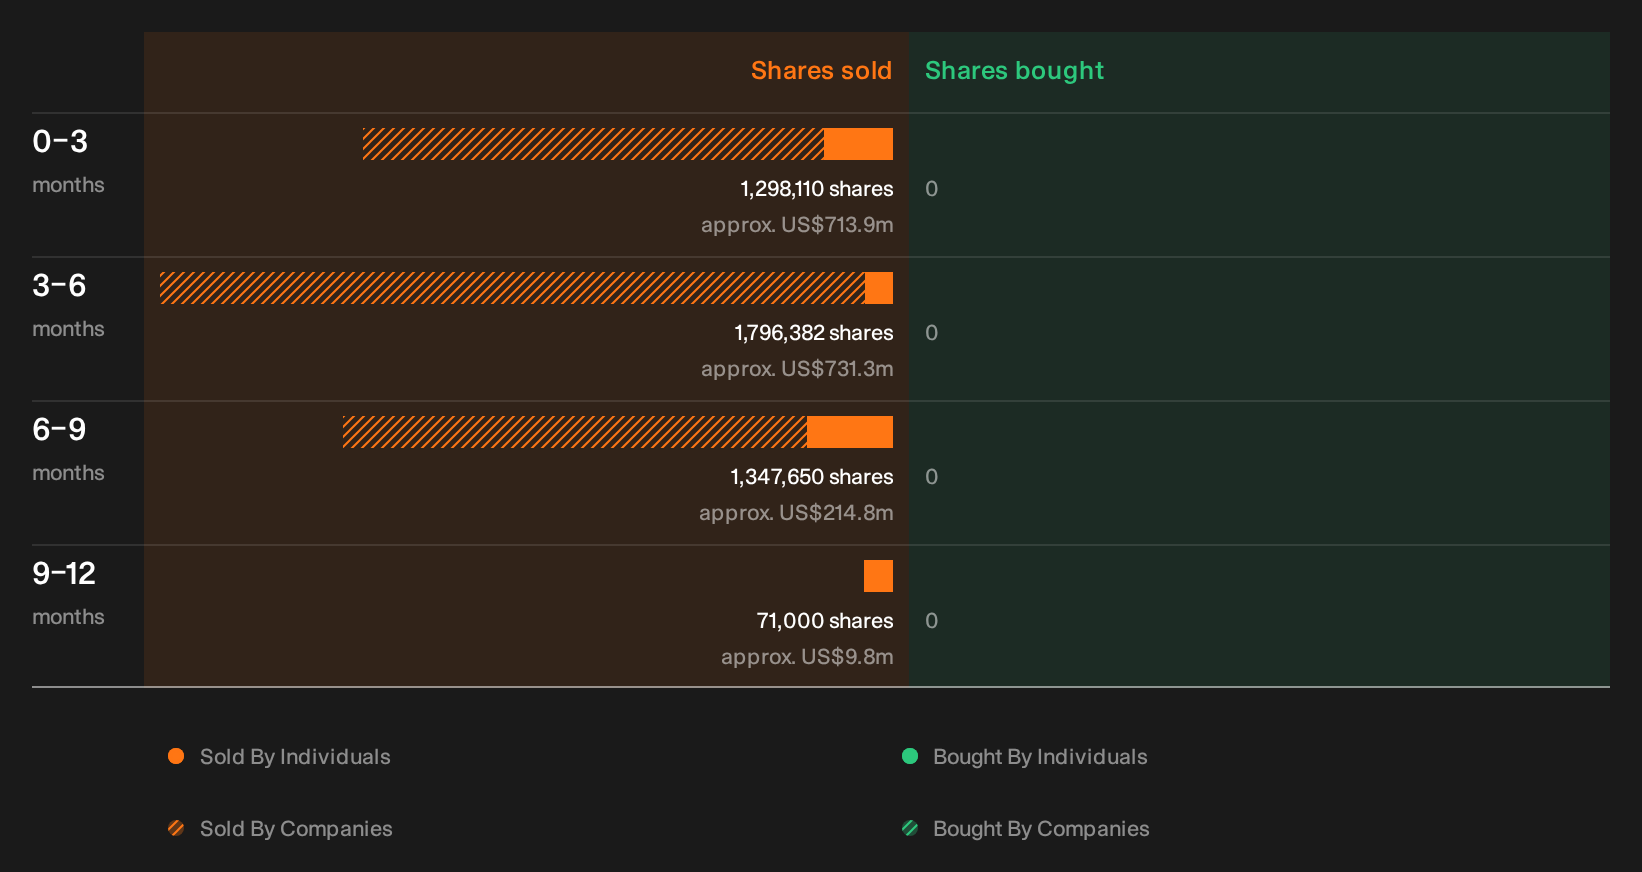
Valuation work tells you what the market might be paying for Dell Technologies, but recent insider transactions flagged by our checks raise a different set of questions about behaviour and incentives that you can review directly. See the recent insider selling flagged for Dell Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com