


EN
Onex (TSX:ONEX) Climbed, So What Is Behind The Fresh Attention?
How Onex’s Latest Earnings Sparked Fresh Investor Interest
Onex (TSX:ONEX) just released third quarter results that showed higher revenue and net income than a year ago, even as the nine month figures reflected a softer performance.
The quarter featured revenue of US$155 million and net income of US$97 million, both above the levels reported in the same period last year, which drew more attention to the recent quarterly trend.
Onex’s latest earnings update landed alongside a 1 month share price return of 9.6% and a 1 day move of 2.73%, while the 90 day share price performance is still down 4.64% and the 3 year total shareholder return sits at 25.71%. This suggests recent momentum has picked up against a more mixed medium term record.
Scan how Onex’s earnings shift fits into a broader pattern of profitable, resilient businesses by comparing it with the curated 9 resilient stocks with low risk scores.
After a near 10% swing higher in a month, Onex now trades between a modest intrinsic premium and a sizeable analyst target gap. So where does a reasonable fair value range actually sit for this stock today?
Preferred Price-to-Earnings of 12.3x: Is It Justified?
Onex closed at CA$110.15, and on a headline measure it trades on a P/E of 12.3x, which screens as cheaper than the wider Canadian equity market but richer than its direct Capital Markets peers.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors are paying for each dollar of profit. For a diversified private equity platform like Onex, this matters because earnings can be lumpy from deal activity, fund performance, and carried interest. As a result, the multiple often reflects views on how repeatable those profits might be.
Against peers, the picture is split. The Onex P/E of 12.3x is described as good value versus a peer average of 34.2x, which signals the stock trades at a steep discount to some comparable companies. At the same time, that same 12.3x level is labelled expensive when lined up against the Canadian Capital Markets industry average of 6.8x, which indicates investors are willing to pay almost double the sector multiple for the current earnings profile.
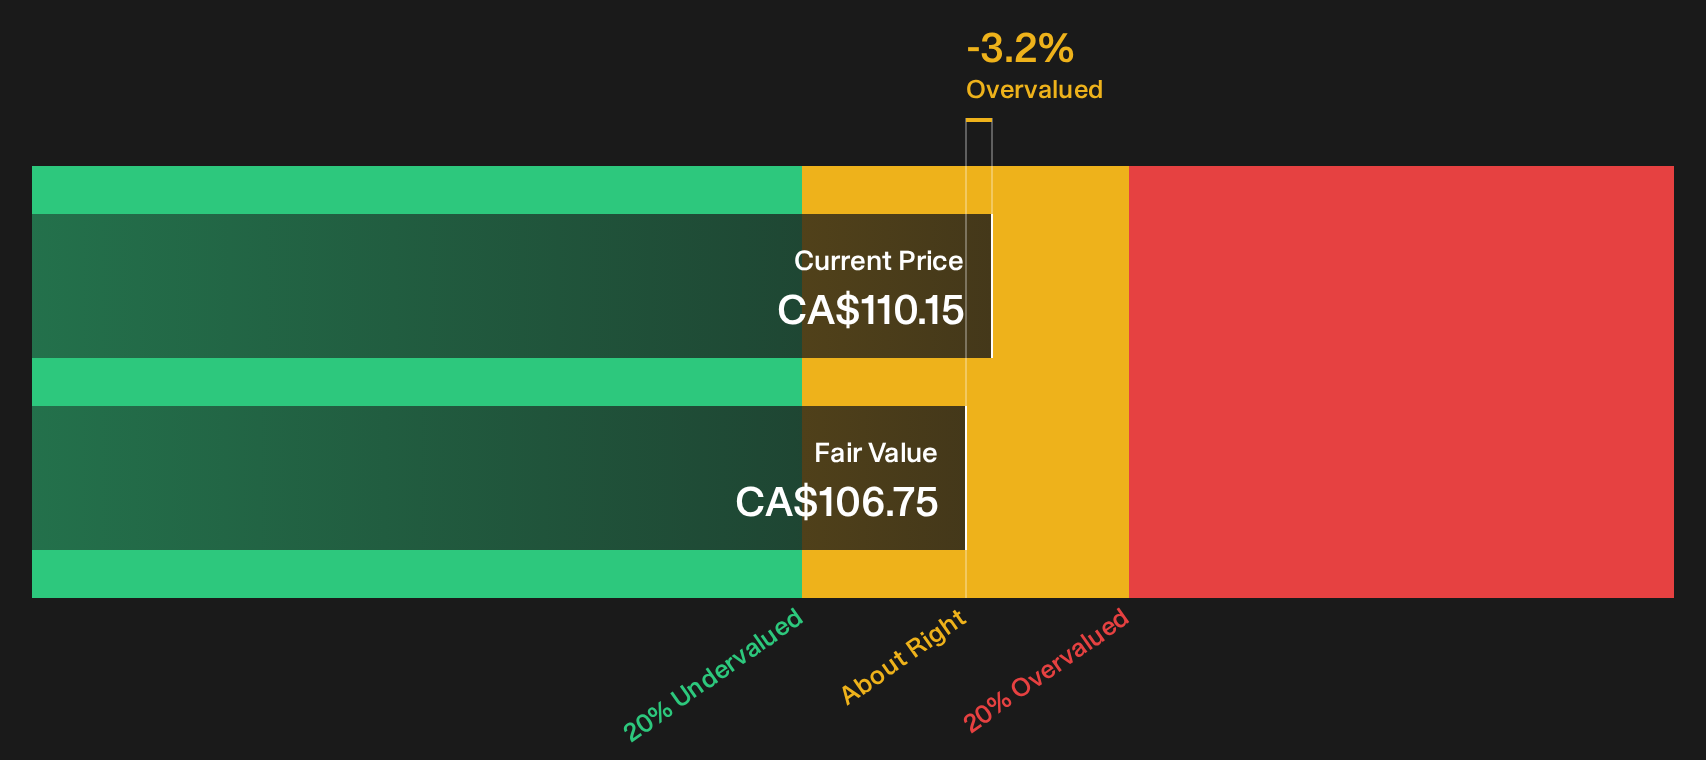
That tension is partly echoed in other metrics. Onex has a low 5% return on equity, earnings have declined by 18% per year over the past 5 years, and profit growth over the last year has been negative, even though current net margins of 66.1% are higher than a year ago. The SWS DCF model also places fair value at CA$106.75, slightly below the current CA$110.15 share price. This suggests the market is already pricing in some recovery or resilience beyond the base cash flow scenario.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 12.3x (OVERVALUED)
Still, the recent 1 year return of 3.3%, alongside a year to date decline of 3.4%, leaves Onex vulnerable if earnings or deal activity soften again.
Find out about the key risks to this Onex narrative.
Another View On Onex’s Value
The SWS DCF model lines up closely with the P/E story for Onex. On a cash flow basis, fair value lands at CA$106.75, slightly below the CA$110.15 share price, which points to a modest premium. If both earnings and cash flows indicate that the shares are fully priced, what would need to change to alter that picture?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Onex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Onex’s value and recent performance can be confusing, so act promptly, review the underlying numbers, and weigh both the 2 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Onex?
If Onex has you thinking harder about price, quality, and risk, then now is the moment to widen your watchlist before the next move passes you by.
- Target robust balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (6 results) that meet strict financial strength filters.
- Hunt for pricing gaps where quality and value intersect using the focused 6 high quality undervalued stocks that flags opportunities others may be overlooking.
- Build a cash flow stream that works harder for you by zeroing in on the 3 dividend fortresses designed for reliable income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com