


EN
Earnings Beat Could Be A Big Moment For Quebecor Stock (TSX:QBR.A)
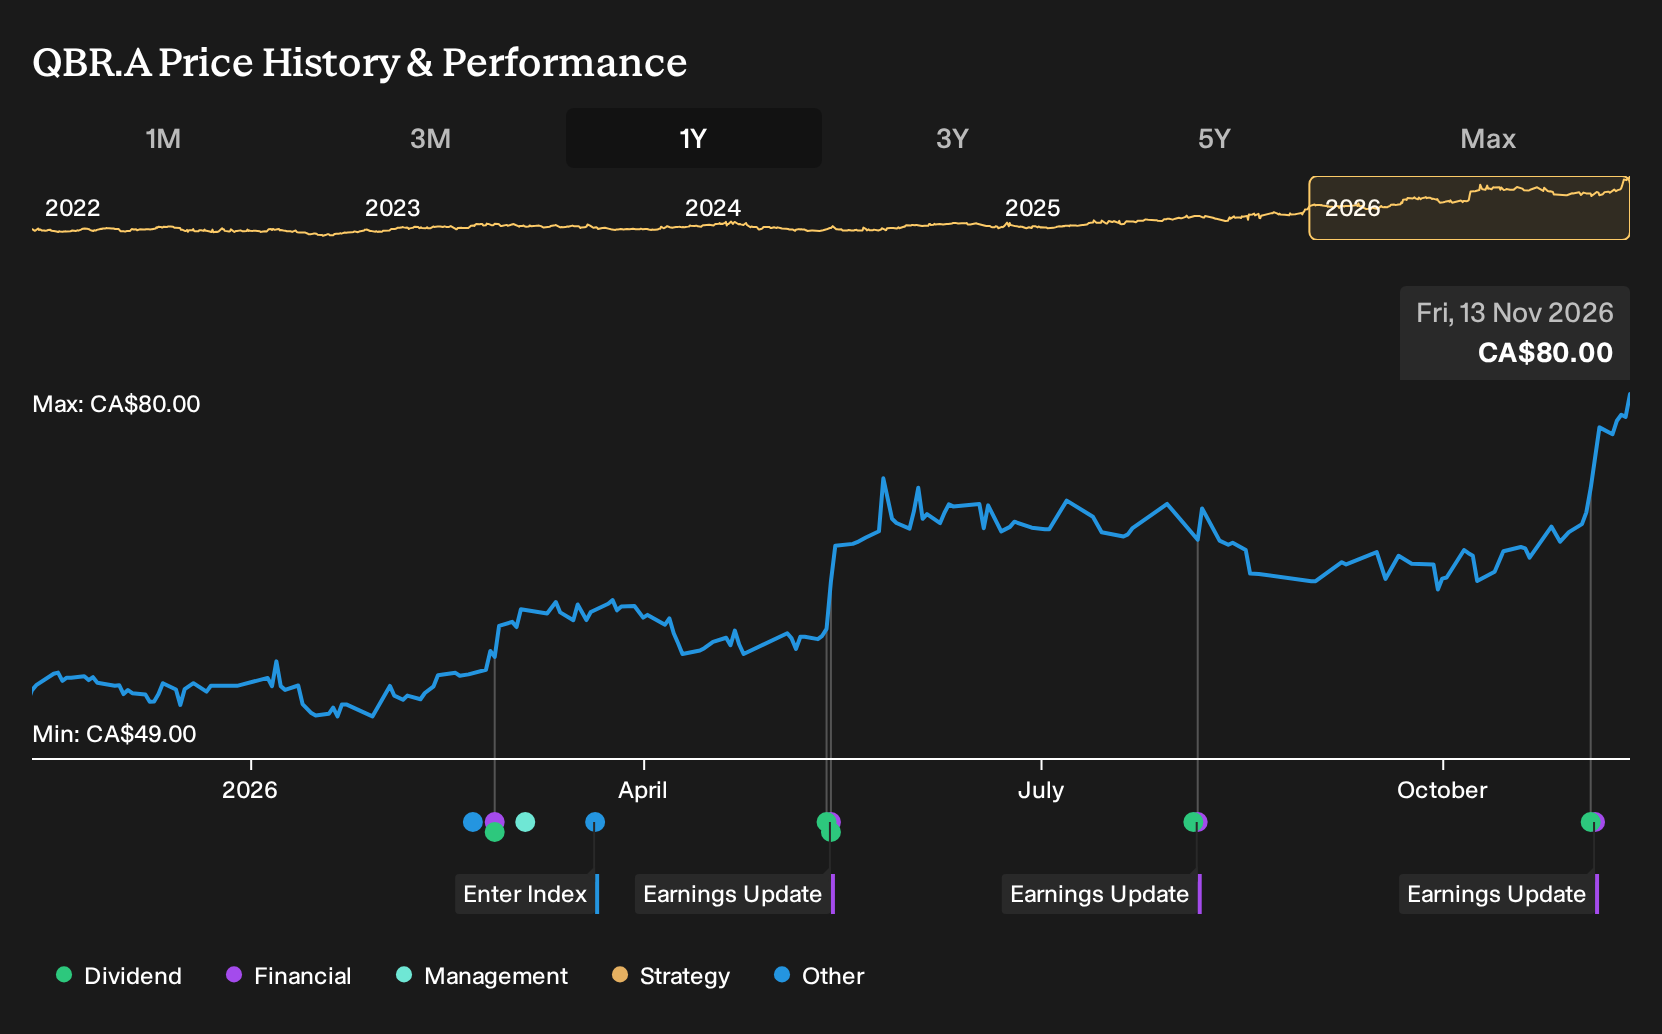
- Quebecor Inc. reported third quarter 2026 sales of C$1,454.7 million and net income of C$296.4 million, with earnings per share from continuing operations higher than a year earlier, and confirmed a quarterly dividend of C$0.45 per share payable in December 2026.
- The business also reported higher sales and net income for the first nine months of 2026 compared with the prior year, which points to sustained operational momentum across its core segments rather than a single quarter anomaly.
- Next, the focus turns to how Quebecor's stronger earnings profile could reshape the broader investment narrative for the company.
What Is Quebecor's Investment Narrative?
The big idea with Quebecor is straightforward. You either believe this telecom and media group can keep turning its Canadian footprint into steady earnings and reliable cash, or you do not. The latest quarter fits neatly into that story. Sales and net income for both the third quarter and the first nine months of 2026 were higher than a year earlier, and earnings per share from continuing operations moved up as well. That kind of delivery, paired with a confirmed C$0.45 dividend for December, reinforces a thesis built on execution, pricing discipline and recurring demand for connectivity rather than one-off gains.
In the short term, the key swing factors remain operational. Telecom is capital intensive, so the ability to fund network spending and spectrum costs while carrying a high level of debt matters as much as headline profit growth. The recent earnings beat and maintained payout indicate that management still sees room to balance investment and shareholder returns, although forecast earnings and revenue growth sit below broader Canadian market expectations. With the share price already well above internal fair value estimates based on future cash flow at C$73.42 and trading on a higher P/E than both the global telecom group and peers, any stumble on these execution points could change the narrative quickly.
That said, there is a specific pressure point in Quebecor's setup that could test this otherwise clean story if ...
There's only one way to know the right time to buy, sell or hold Quebecor. Head to Simply Wall St's company report for the latest analysis of Quebecor's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own. Quebecor rewards that kind of work because the story sits in the details of earnings quality, balance sheet strength and how management allocates every extra dollar of cash.
- A great starting point for your Quebecor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quebecor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quebecor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Quebecor?
Once you have a view on Quebecor, it can help to benchmark that thinking against other businesses with different risk and income profiles. A focused screener lets you quickly surface candidates that fit your preferred mix of balance sheet strength, cash generation and income potential, so you spend time assessing quality rather than just hunting for tickers.
- If you want resilient businesses with conservative leverage and healthy liquidity, start with a list of solid balance sheet and fundamentals (6 results) that already filters for stronger financial footing.
- For investors hunting for potential value ideas, use the 6 high quality undervalued stocks to see which stocks combine quality fundamentals with prices that sit below many fair value estimates.
- If dependable income is a priority, narrow your search to higher yielding payers by running the 3 dividend fortresses that focuses on companies offering dividend returns of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com