


EN
Does Return To Profit Change The Bull Case For Chartwell Retirement Residences (TSX:CSH.UN)?
- Chartwell Retirement Residences reported third quarter 2026 revenue of CA$324.98 million and net income of CA$114.96 million, compared with revenue of CA$282.17 million and a net loss of CA$5.24 million in the same period a year earlier.
- The swing from loss to profit, alongside nine month revenue of CA$960.47 million and net income of CA$121.61 million, indicates that recent portfolio upgrades and operating changes are now reflected more clearly in the income statement.
- This article considers how Chartwell Retirement Residences' investment narrative is affected by this shift from quarterly loss to substantial profit.
Chartwell Retirement Residences Investment Narrative Recap
Owning Chartwell Retirement Residences means believing its senior housing portfolio can keep turning strong demand and operational tweaks into recurring earnings, not just one off jumps. The latest quarter shows clean revenue and profit figures on the surface, but management still has to prove that this profitability is durable as staffing, utilities and regulatory pressures remain very real.
The key short term catalyst is execution of the 2026 to 2028 plan described in the analyst consensus Narrative on Simply Wall St, especially occupancy above 95% and tight cost control. The biggest near term risk stays the same. Equity issuance and higher interest costs could dilute per unit results even if operating income holds up.
The third quarter report, with CA$324.98 million of revenue and CA$114.96 million of net income, sits right at the center of that story. It connects directly to the analyst consensus Narrative on Simply Wall St, which leans on portfolio recycling, limited new Canadian supply and operating efficiency to support revenue and earnings over the plan period.
On the risk side, the same report highlights why investors may want to keep an eye on quality of earnings and funding choices. Recent commentary flags large one off items in the last 12 months and reliance on higher risk funding, while the distribution is described as not well covered by earnings or free cash flow. How Chartwell Retirement Residences balances growth, leverage and dilution looks crucial to those catalysts playing out.
Chartwell Retirement Residences' current earnings are CA$8.7 million, with analysts forecasting revenue growth of 10.6% per year and projecting CA$1.6b of revenue and CA$198.8 million of earnings by 2029. This implies an earnings increase of about CA$190 million from today.
Uncover why Chartwell Retirement Residences' fair value indicates a 23% potential upside to its current price that could narrow quickly.
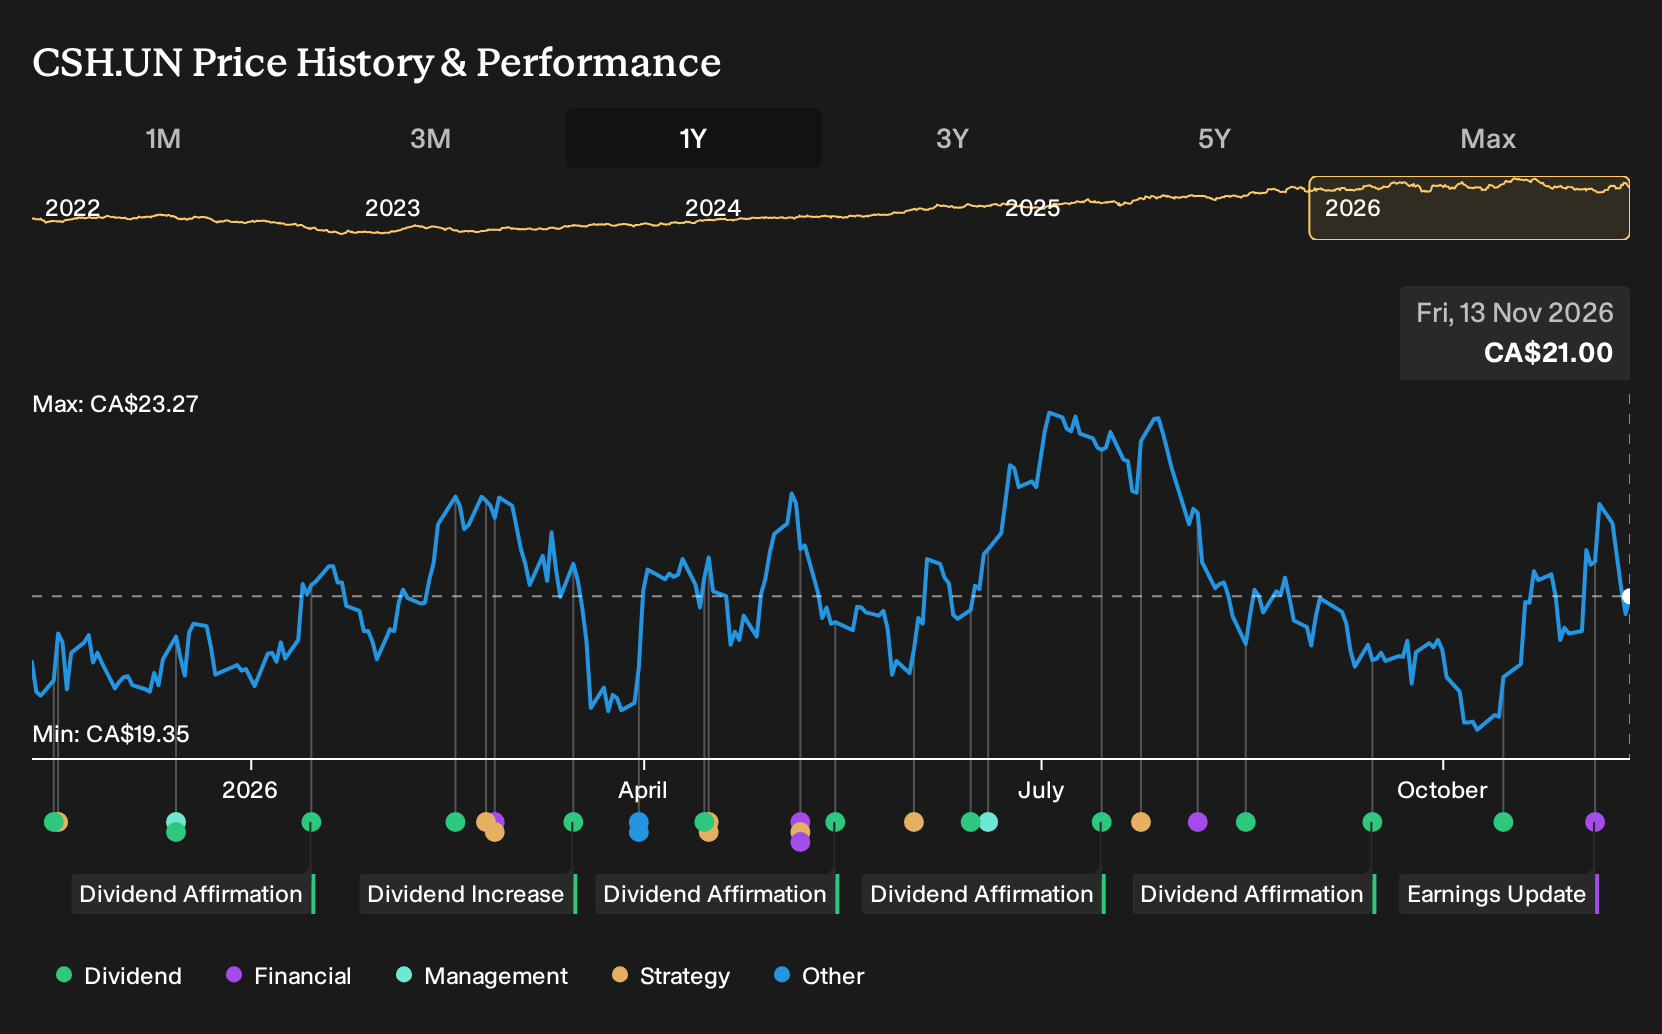
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span an extreme range, from about 0.17x to over 25x the current Chartwell Retirement Residences price. Such dispersion shows how far opinions can spread when earnings quality, equity issuance and sector demand all pull in different directions. Use that gap as a prompt to explore several contrasting viewpoints before deciding how this turnaround story fits your own income and risk goals.
Explore 2 other Chartwell Retirement Residences fair value estimates, including one that suggests as much as 99% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Chartwell Retirement Residences research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Chartwell Retirement Residences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chartwell Retirement Residences' overall financial health at a glance.
Looking for more investment ideas beyond Chartwell Retirement Residences?
Once you have a view on Chartwell Retirement Residences, it can help to compare that thesis with other opportunities that match your income, risk and balance sheet preferences. The Simply Wall St Screener lets you filter for the kind of businesses that fit how you invest, rather than forcing your process around a single stock.
- If capital preservation matters most, start with companies that score well on resilience and funding strength through the 9 resilient stocks with low risk scores.
- If dependable balance sheets appeal more than a turnaround story, line up Chartwell Retirement Residences beside a list of solid balance sheet and fundamentals (6 results) to see how its financial position compares.
- If you want a wider hunting ground before committing fresh capital, cast a broader net over 9 high quality undiscovered gems that pair quality fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com