


EN
Russel Metals (TSX:RUS) Posts Stronger Earnings As Investors Ask If The Stock Is Fully Valued
Why Russel Metals' latest earnings matter for investors
Russel Metals (TSX:RUS) just posted third quarter and nine month 2026 results, highlighted by higher sales and net income compared with a year earlier, which has put fresh attention on the stock's recent performance.
The latest earnings update landed on a stock that has already had a strong run, with Russel Metals' share price up 81.88% year to date and total shareholder return of 106.11% over the past year. This comes even though the 30 day share price return declined 13.57%, as some investors reassessed how much of this stronger profitability is already reflected in the CA$79.41 price.
Scan the metal and capital-goods space for other potential breakouts with strong balance sheets and earnings power by running the list of solid balance sheet and fundamentals (6 results) alongside Russel Metals after this report.
Russel Metals just reported much stronger earnings and the share price has already surged this year. The business appears strong, but does the current valuation still leave enough potential upside for new investors?
Most Popular Narrative: 29% Overvalued
Russel Metals last closed at CA$79.41 while the analyst consensus Narrative on Simply Wall St points to a fair value of CA$61.50, so that framework sees the shares trading well above its estimate and anchors the discussion in discounted future cash flows.
Ongoing investments in value-added processing, facility modernization, and supply chain digitization are set to enhance operational efficiency, supporting margin improvement and stronger free cash flow as Russel shifts its business mix to higher-margin products and services.
Strategic M&A activity, coupled with a robust balance sheet and capital flexibility, gives Russel significant optionality to accelerate expansion into higher-growth, higher-margin segments and geographies, fueling both revenue and net margin upside.
See why 46 investors see Russel Metals as 29% overvalued.
The Narrative applies a 7.6% discount rate and a future P/E of about 15.2x to those projected earnings and cash flows, which leads to a fair value that sits well below the current CA$4.3b market value and frames Russel Metals as pricing in a lot of that expected execution already.
Result: Fair Value of CA$61.50 (OVERVALUED)
Still, the story can change quickly if cyclical demand in construction and energy softens further, or if shifts in trade policy compress Russel Metals' pricing power.
Find out about the key risks to this Russel Metals narrative.
Another View: What Russel Metals' P/E Is Saying
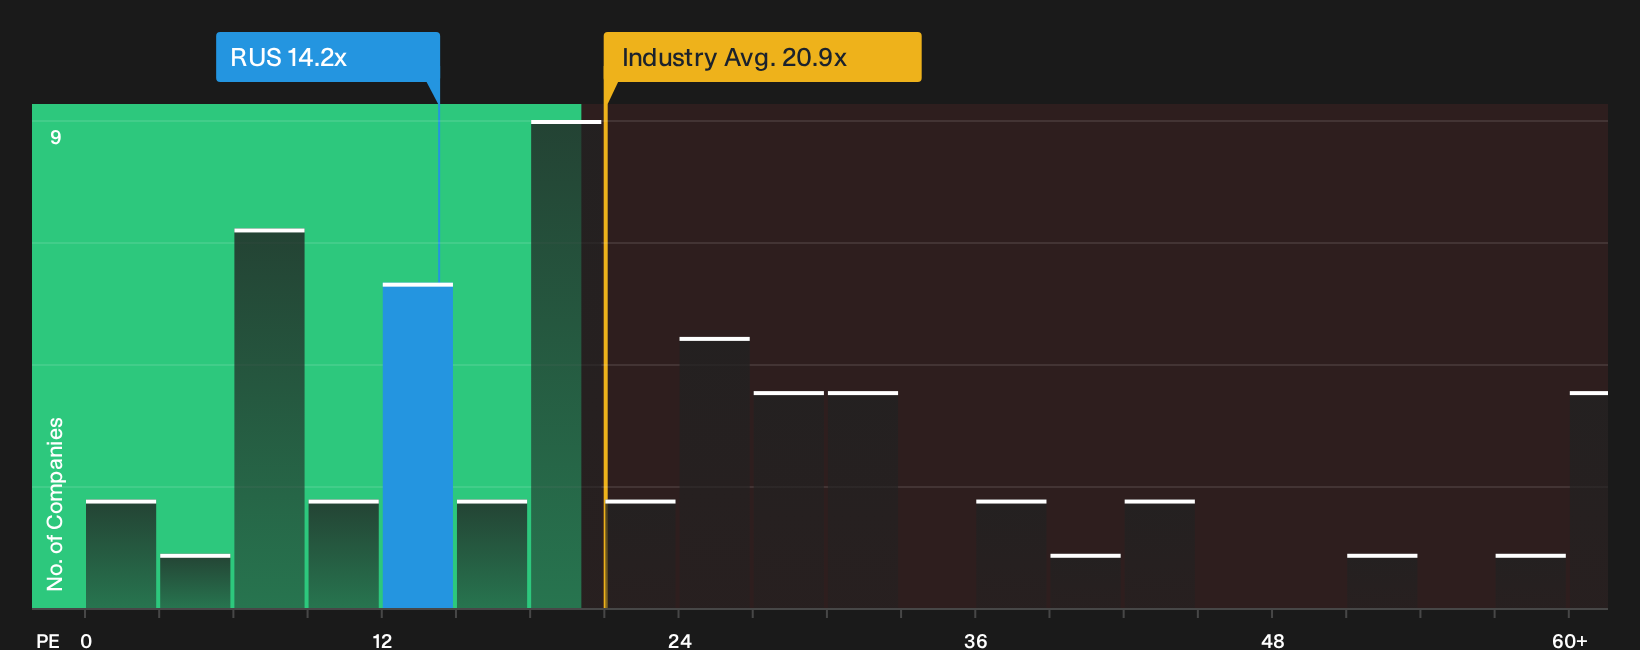
The analyst Narrative leans on discounted future cash flows and flags Russel Metals as overvalued at CA$79.41 versus a CA$61.50 fair value. The current P/E near 14.2x tells a very different story because it sits well below the Canadian Trade Distributors industry on 20.9x and a peer group on 20.4x.
That gap means investors today are paying a lower price for each dollar of Russel Metals' earnings compared with both the wider industry and closer peers, even after a strong share price run and a view that cash flows are fully priced. The question is whether this cheaper earnings multiple reflects hidden risk or a mispriced opportunity.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Russel Metals so far? Use the full data set, weigh both the risks and the potential rewards, then decide where you stand with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Russel Metals?
If Russel Metals has sharpened your thinking, do not stop here. Broaden your watchlist with fresh opportunities that match different goals and risk levels.
- Target potential mispricing by scanning a curated set of high quality opportunities using the 6 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature resilient payouts with the 3 dividend fortresses.
- Dial down volatility in your portfolio by sourcing companies with sturdier financial profiles through the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com