


EN
What Is Drawing Attention To SmartCentres Real Estate Investment Trust (TSX:SRU.UN)?
SmartCentres Real Estate Investment Trust (TSX:SRU.UN) just reported third quarter 2026 results, with revenue slightly lower year over year but quarterly net income more than doubling, a shift that immediately refocused attention on profitability.
At a share price of CA$28.03, SmartCentres Real Estate Investment Trust has seen a 6.05% 1 month share price return and an 8.73% year to date share price gain. Its 1 year total shareholder return of 14.18% and 3 year total shareholder return of 50.81% indicate momentum that has cooled slightly in recent months but still reflects investors reassessing the trust after the sharp quarterly profitability improvement.
Scan how SmartCentres Real Estate Investment Trust stacks up against other income-focused real estate plays by reviewing our curated list of 3 dividend fortresses.
SmartCentres Real Estate Investment Trust has just delivered a sharp swing in quarterly profit while the unit price has already moved higher. Do you lock in exposure now, or wait and hope for a better entry once the dust settles on valuation?
Preferred Price-to-Earnings of 17.1x: Is it justified?
On valuation, the tension point is clear. SmartCentres Real Estate Investment Trust trades at a P/E of 17.1x, which looks a bit rich next to its own peer group but cheaper than the broader North American retail REIT pack.
The P/E multiple compares the current unit price to earnings per unit. For an income-focused trust like SmartCentres Real Estate Investment Trust, it tells you how much investors are paying for each dollar of profit, and therefore hints at how the market views the sustainability of those earnings relative to other options in the sector.
Against direct peers, the P/E of 17.1x is higher than the peer average of 15.6x. That suggests investors are paying a premium relative to similar Canadian listed comparables for the current earnings profile. When a unit trades richer than its closest reference group, the market is often baking in steadier income, perceived quality of the asset base, or confidence in management execution that is not fully reflected in near term numbers.
Set against the wider North American retail REIT universe, the picture flips. The same 17.1x P/E screens as good value against the industry average of 22.4x, which points to a material discount relative to the broader regional peer set. That kind of gap often signals the potential for re rating if investors start to view SmartCentres Real Estate Investment Trust in line with larger or more widely held retail REITs, although the slower forecast revenue growth of 2.8% a year and low 4.7% return on equity show why some investors may hesitate to close that gap quickly.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 17.1x (ABOUT RIGHT)
Still, SmartCentres Real Estate Investment Trust carries risks if revenue growth stalls from the current 2.8% rate or if the 4.7% return on equity limits future reinvestment options.
Find out about the key risks to this SmartCentres Real Estate Investment Trust narrative.
Another View On SmartCentres Real Estate Investment Trust: Cash Flows Tell A Different Story
The earnings multiple paints SmartCentres Real Estate Investment Trust as roughly fairly priced, yet the SWS DCF model points to something else. At CA$28.03, units trade about 26% below the modelled future cash flow value of CA$37.99. That raises a blunt question for income investors. Is the market overly focused on slow revenue growth and low 4.7% return on equity, or is the cash flow model too generous about what this REIT can deliver over time?
Look into how the SWS DCF model arrives at its fair value.
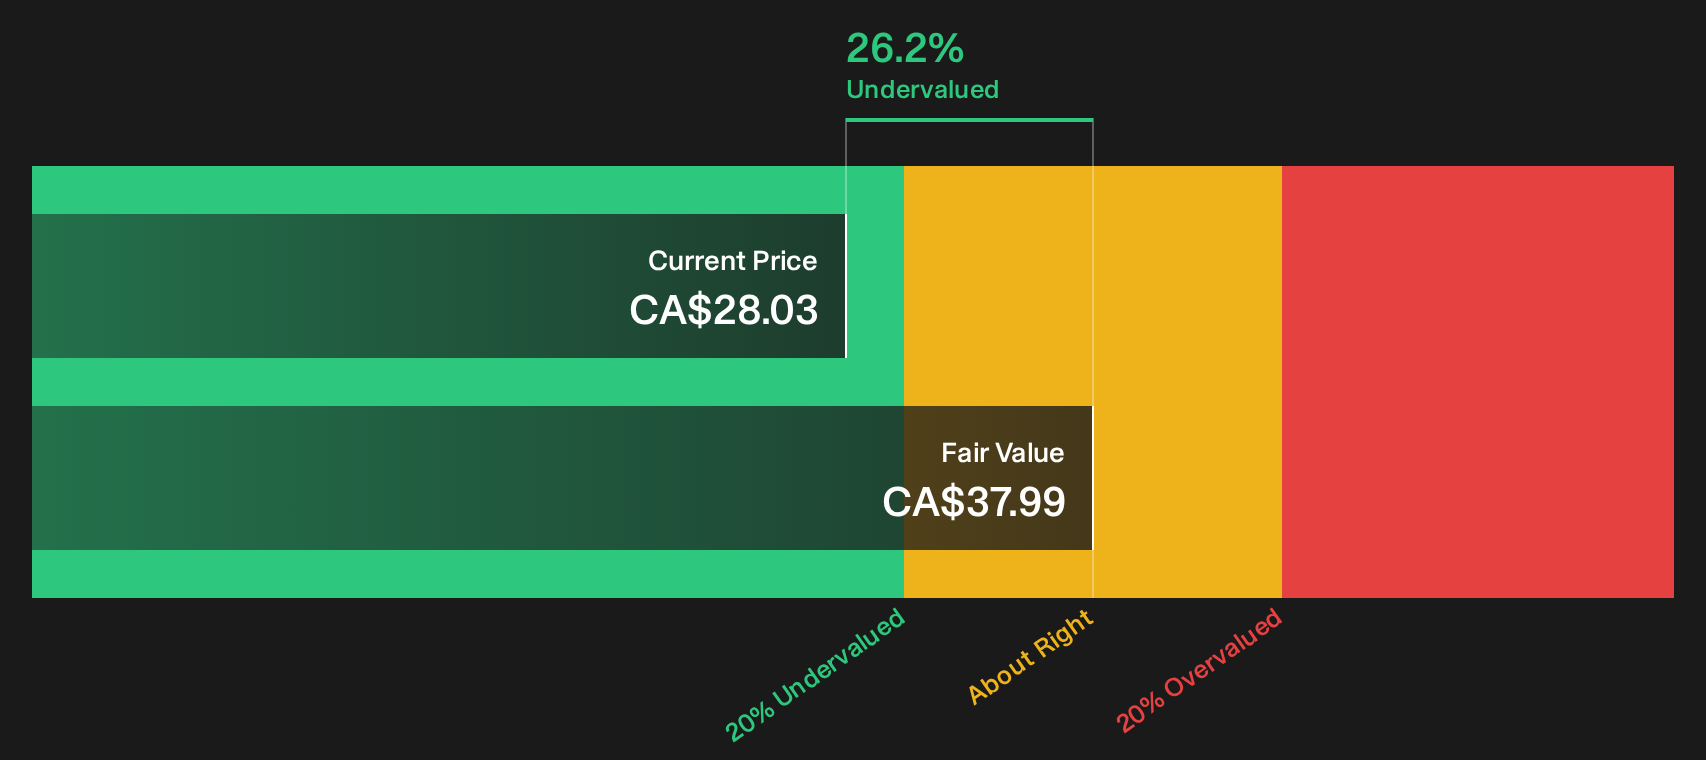
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SmartCentres Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on SmartCentres Real Estate Investment Trust so far. If you want to move quickly and shape your own view, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond SmartCentres Real Estate Investment Trust?
If SmartCentres Real Estate Investment Trust has your attention today, do not stop here. Broaden your watchlist with a few targeted hunting grounds for potential opportunities.
- Spot potential turnaround stories early by scanning 19 elite penny stocks with strong financials that already pair higher risk with supporting financials, rather than pure speculation.
- Zero in on quality at a discount through our curated 6 high quality undervalued stocks, where stronger fundamentals meet more modest market expectations.
- Prioritise resilience first by working through the 9 resilient stocks with low risk scores and focus on businesses that score well on financial strength and stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com