


EN
Is Edwards Lifesciences (EW) Fully Priced On Raised Guidance And Clinical Trial Wins?
Edwards Lifesciences (EW) just reported a third quarter earnings update showing higher year on year sales and net income, along with raised full year 2026 guidance and strong new clinical trial data.
At a share price of $107.15, Edwards Lifesciences has seen momentum build recently, with a 1-month share price return of 23.94% and a year-to-date share price return of 25.57%. The 3-year total shareholder return of 60.16% contrasts with a decline of 8.44% over five years.
Spot 35 healthcare AI stocks that, like Edwards Lifesciences after its earnings and clinical wins, are drawing fresh attention from investors who are looking for catalysts tied to real-world medical outcomes.After a 24% jump in a month, Edwards Lifesciences is no longer a quiet backwater on the watchlist. Is this a fair entry now, or does it make more sense to wait for a pullback once the excitement cools and the valuation is clearer?
Most Popular Narrative: 3% Overvalued
On the analyst consensus Narrative on Simply Wall St, Edwards Lifesciences screens as modestly overvalued, with a fair value of $104.27 against the recent $107.15 close, which anchors the current debate around how much of the growth story is already in the price.
The main factor that has to go right is successful execution on the multi-platform structural heart strategy. This includes TMTT growth toward the stated 2030 revenue goal and continued translation of long-term clinical data into physician preference.
See why 29 investors see Edwards Lifesciences as 3% overvalued.
Result: Fair Value of $104.27 (OVERVALUED)
Still, TAVR volume assumptions and the injunction linked to the blocked JenaValve acquisition could easily unsettle the Edwards Lifesciences narrative if they break the current script.
Find out about the key risks to this Edwards Lifesciences narrative.
Another View: What The DCF Says About Edwards Lifesciences
The multiple based fair value of $104.27 points to Edwards Lifesciences looking slightly expensive against the current $107.15 share price. The SWS DCF model lands in a very different place, with an estimated future cash flow value of $108.21, which suggests a small potential upside instead.
That gap is not huge in either direction. Yet it raises a simple question for you as an investor: Do you trust the market to keep anchoring around earnings multiples, or does the cash flow picture feel like the cleaner guide for your own homework?
Look into how the SWS DCF model arrives at its fair value.
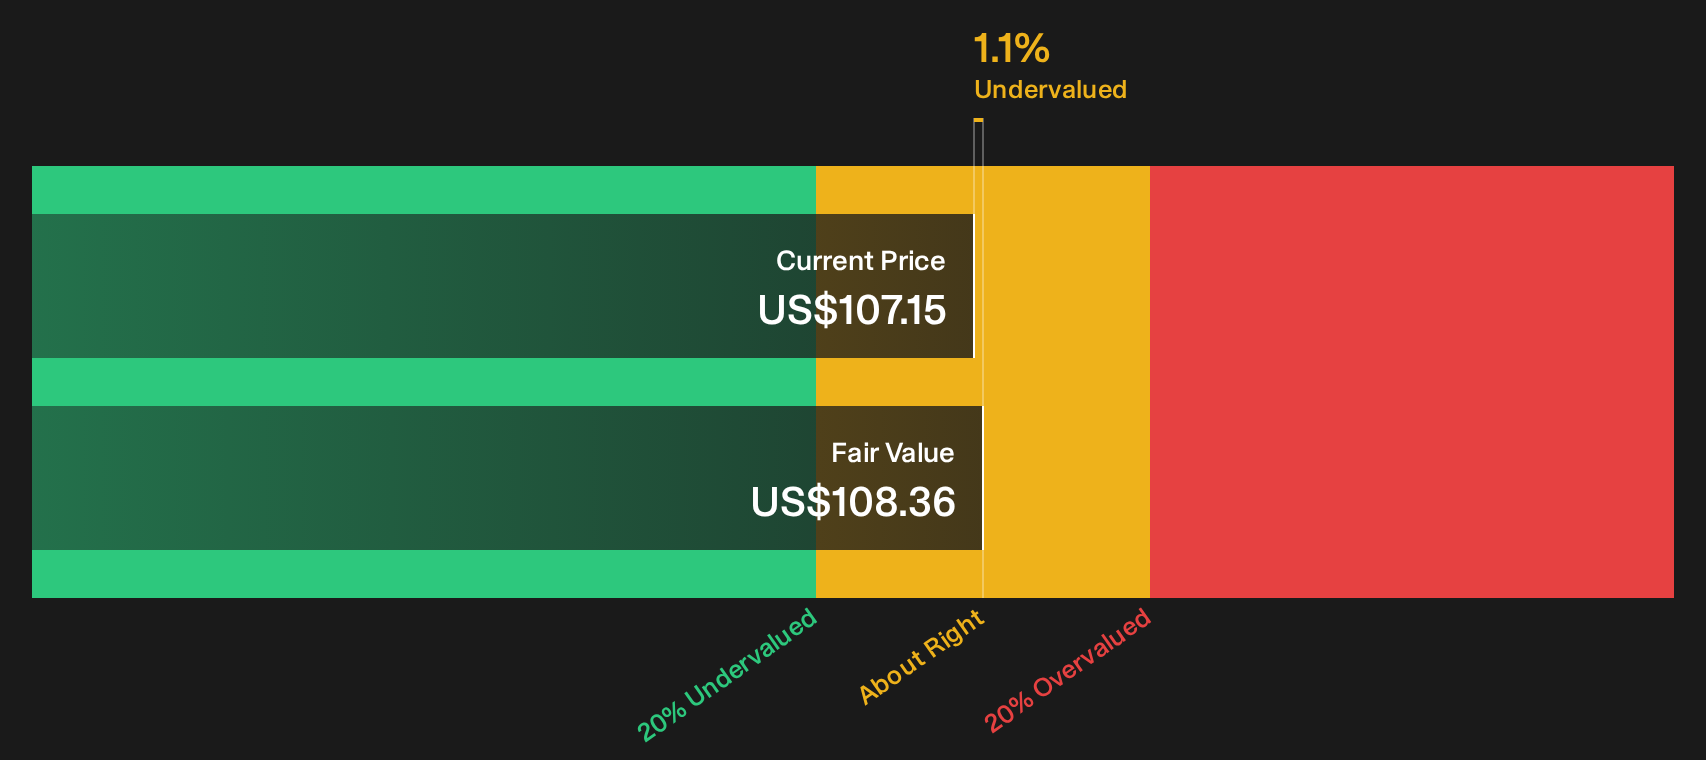
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Edwards Lifesciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment this mixed around Edwards Lifesciences, it makes sense to move fast, test the numbers yourself, and weigh both sides of the story through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Edwards Lifesciences?
If Edwards Lifesciences has your attention, do not stop here. Broaden your watchlist with focused stock ideas that match clear goals and risk levels.
- Target potential mispricing by scanning a curated set of 32 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Build income resilience by tracking 6 dividend fortresses that aim to balance strong payouts with business strength instead of just chasing yield.
- Prioritize capital protection by filtering for 29 resilient stocks with low risk scores that score well on financial stability before headlines move the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com