


EN
Does Strong Earnings Guidance Change The Bull Case For Grand Canyon Education Stock (LOPE)?
- Grand Canyon Education reported third quarter 2026 net income of US$43.01 million and diluted EPS of US$1.67 from continuing operations, alongside year-to-date net income of US$164.21 million and diluted EPS of US$6.25.
- Management also issued fourth quarter and full-year 2026 guidance that outlined specific targets for service revenue, operating margin, and earnings per share, giving investors clearer visibility into how the education services model is currently performing.
- We will now look at how Grand Canyon Education's recent earnings results and margin guidance could influence the existing investment narrative.
Grand Canyon Education Investment Narrative Recap
To own Grand Canyon Education, you need to believe its outsourced education services model can keep filling online and hybrid programs even as the pool of traditional high school graduates shrinks and more students consider alternatives to four year degrees. The new 2026 guidance puts concrete numbers around service revenue and margins, which helps you judge whether that operating thesis is still intact.
The near term swing factor is execution on enrollment and student retention across university partners, because that drives both service revenue and the guided operating margins. The biggest risk is pressure on revenue per student and higher costs for technology, benefits, and legal matters, and this latest outlook does not remove those concerns.
The most relevant update here is Grand Canyon Education's fresh guidance for fourth quarter and full year 2026. Management is targeting service revenue of US$320.5 million to US$321.5 million in Q4 and US$1.1607b to US$1.1617b for the year, with Q4 operating margin around 36% and full year margin just under 28%.
For you, this guidance is a real time check on the analyst consensus Narrative on Simply Wall St, which leans on ongoing online program adoption and margin efficiency as key drivers. The outlined EPS ranges and profitability goals give you reference points to watch execution, especially around partner economics, cost inflation, and any future pressure on revenue share or student mix.
Grand Canyon Education's current earnings are US$236.5 million, with analysts forecasting earnings of US$306.2 million by 2028 and projecting revenue of US$1.3b in the same year. This outlook assumes revenue growth of 6.7% per year and an earnings increase of US$69.7 million from today's level.
Uncover why Grand Canyon Education's fair value indicates a 62% potential upside to its current price before that gap starts to close.
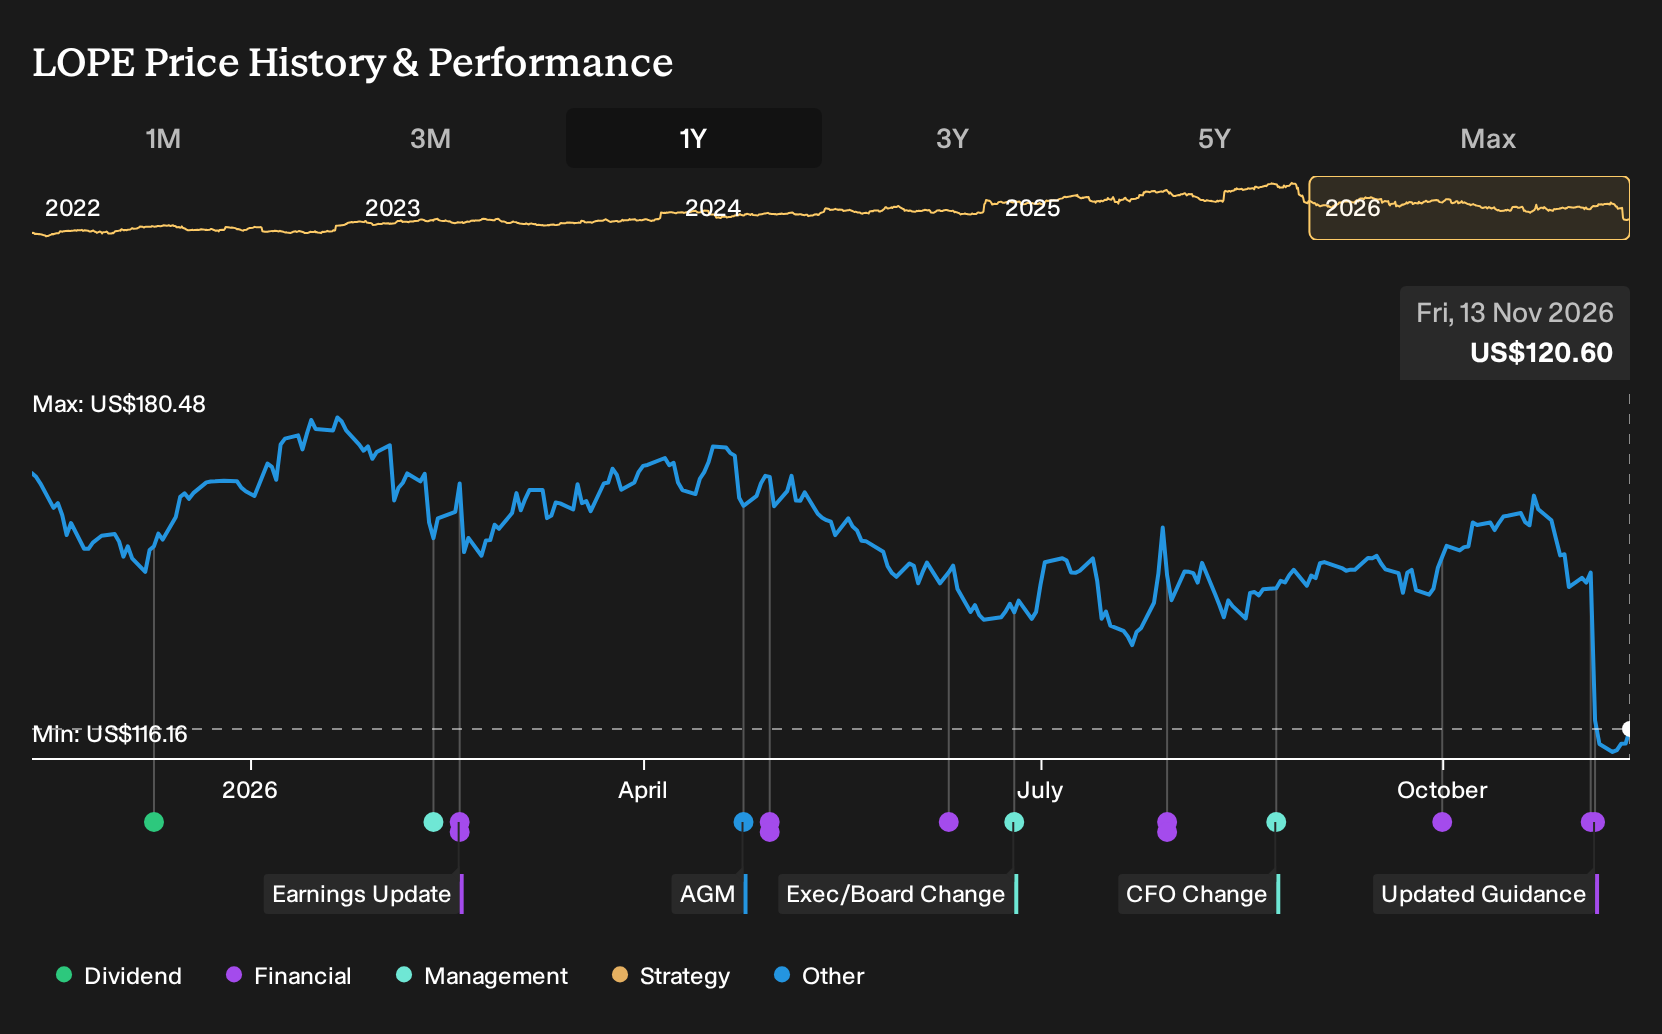
Exploring Other Perspectives
Fair value estimates for Grand Canyon Education from 2 Simply Wall St Community members range from US$195 up to about US$360, which is a wide band for such a small sample. Those views sit alongside twin forces you need to weigh: online program expansion as a potential catalyst, and enrollment or regulatory pressure as potential brakes. Together they highlight how far investor opinions can diverge and why you should review several alternative viewpoints before deciding how this story fits your portfolio.
Explore another Grand Canyon Education fair value estimate, including one that suggests it could be worth just $195.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grand Canyon Education research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Grand Canyon Education. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grand Canyon Education's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grand Canyon Education?
Once you have a view on Grand Canyon Education, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. You get a broader context for quality, value, and risk, and that can sharpen how you think about where this education services stock fits in your overall portfolio.
- If you want potential value combined with financial resilience, scan a 32 high quality undervalued stocks that pairs strong balance sheets and healthy cash generation with prices that still look undemanding.
- For investors who care most about defence, focus on stability and capital preservation with a 29 resilient stocks with low risk scores that scores well on earnings consistency and financial health.
- When income matters more than headlines, zero in on a 6 dividend fortresses that offers higher yields while still screening for balance sheet strength and coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com