


EN
Goodwill Write Downs Might Change The Case For Investing In Ziff Davis Stock
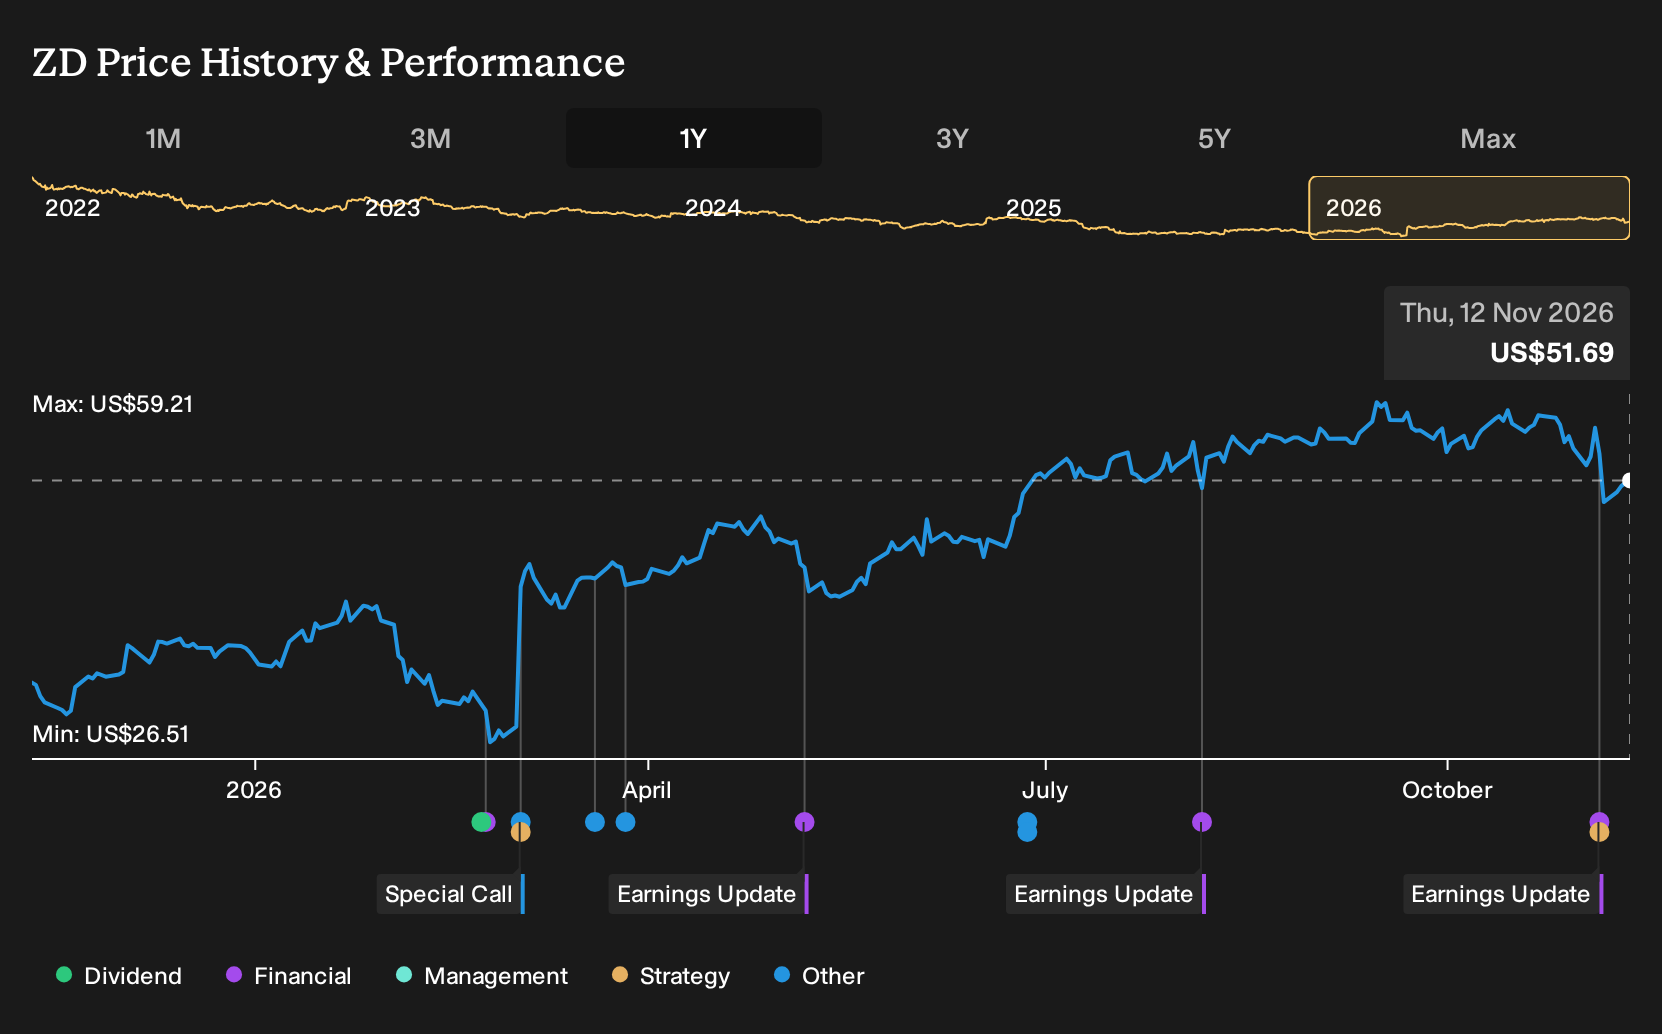
- Ziff Davis reported third quarter 2026 results with sales of US$289.33 million, a net loss of US$28.69 million, and goodwill impairment charges of US$29.55 million.
- The sharp rise in goodwill write downs, together with a shift from profit to loss, highlights mounting pressure on acquired assets and core profitability at Ziff Davis.
- The focus now is on how Ziff Davis's investment narrative is affected by higher goodwill impairment and weaker third quarter earnings.
Ziff Davis Investment Narrative Recap
To own Ziff Davis, you need to believe the portfolio of digital media, cybersecurity and Martech assets can offset pressure in search driven and healthcare advertising revenue that the analyst consensus Narrative on Simply Wall St already flags as a risk. The latest quarter complicates that story. Higher goodwill impairment and a wider quarterly loss suggest some acquired units are not performing in line with earlier expectations.
In the short term, the key swing factor is whether subscription and non advertising lines in areas like Cybersecurity and Martech can steady earnings while management works through weaker Tech & Shopping and Health & Wellness trends. The biggest risk is that ongoing revenue softness and further write downs keep profitability under strain and slow any path back to cleaner margins.
The most relevant update here is the third quarter 2026 earnings release itself. Ziff Davis reported US$289.33 million of sales for the period and a net loss of US$28.69 million, alongside goodwill impairment of US$29.55 million compared with US$17.58 million a year earlier. That combination points to both operating and balance sheet pressure in parts of the portfolio.
Those figures sit against an analyst view that expects revenue to decline over the next three years but for the group to become profitable over that horizon. For catalysts such as asset recycling and share repurchases to matter in the way analysts outline, execution now hinges on stabilising core segments and avoiding a pattern of recurring impairments that could absorb future cash generation.
Ziff Davis's current analyst script points to revenues of US$1.2 billion and earnings of US$34.8 million by 2029, based on an assumed 7.2% yearly decline in revenue and an earnings move of roughly US$64.5 million from a loss of US$29.7 million today to the forecast level in that same year.
Uncover how Ziff Davis' fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view argues that the real swing factor for Ziff Davis is future goodwill write downs rather than ad recovery. That group was already using a lower price target and assuming roughly US$1.2b of revenue and about US$52.2 million of earnings by 2029. You can treat this more pessimistic script as a reference point, then decide whether the latest impairments justify adjusting your own expectations.
Explore another Ziff Davis fair value estimate, including one that suggests it could be worth just $63.67!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ziff Davis research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ziff Davis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ziff Davis' overall financial health at a glance.
Looking for more Ziff Davis style investment ideas?
If the Ziff Davis story has you thinking about portfolio resilience, use this momentum to widen your watchlist with companies that better match your own risk, income, and value preferences through the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, scan our value focused picks through the 32 high quality undervalued stocks and see which businesses match your return and risk filters.
- If protecting capital comes first, filter for steadier balance sheets and stronger fundamentals by running the list of solid balance sheet and fundamentals (23 results) as a starting universe.
- When you want to broaden your opportunity set beyond the usual large caps, use the 20 high quality undiscovered gems to surface underfollowed companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com