


EN
H&R Real Estate Investment Trust (TSX:HR.UN) Following The Failed Sale Is The Valuation Case Still Intact
H&R Real Estate Investment Trust (TSX:HR.UN) is back in focus after the collapse of its proposed CA$3.4b sale to a GO Residential led consortium, a deal that was terminated when unitholders withheld approval.
Over the past year, H&R Real Estate Investment Trust has seen its momentum cool, with the unit price at CA$9.36 after a 90 day share price return that declined 9.57% and a 1 year total shareholder return that fell 11.75%, even though the 3 year total shareholder return is up 26.07%.
Scan how other real estate and income-focused opportunities stack up by reviewing our hand-picked 3 dividend fortresses alongside H&R Real Estate Investment Trust.
After the failed CA$12.01 per unit takeout and the pullback to CA$9.36, some investors see H&R Real Estate Investment Trust as a reset opportunity, while others prefer to wait. How does the current valuation stack up against that backdrop?
Most Popular Narrative: 14.5% Undervalued
Against the last close at CA$9.36, the analyst consensus Narrative on Simply Wall St points to a fair value of CA$10.95, which frames H&R Real Estate Investment Trust as trading at a discount and puts more weight on future earnings power than on the scrapped takeout price.
New developments such as Lantower West Love, Lantower Midtown, Bayside and Sunrise, along with 9 Sunbelt developments totaling about 2,900 suites, are progressing on time and on budget. This can add incremental rental income and NOI as they lease up.
See why 4 investors see H&R Real Estate Investment Trust as 15% undervalued.
The fair value in that Narrative is built around analyst assumptions that H&R Real Estate Investment Trust’s revenue trends ease rather than collapse, profit margins recover from current loss levels, and discounted earnings by 2029 support a CA$10.95 outcome at a 7.06% discount rate.
Analysts in that framework are effectively saying the current unit price reflects a lot of the pain from recent losses, while the forecast path to CA$563.7m in earnings and a 6.5x P/E by 2029 would justify a higher valuation if those numbers arrive as projected.
For you, the key question is whether the ingredients inside that Narrative, from Sunbelt multifamily supply to asset recycling and margin repair, feel realistic enough to bridge the gap between today’s CA$9.36 and the CA$10.95 anchor.
Result: Fair Value of CA$10.95 (UNDERVALUED)
Still, the narrative around H&R Real Estate Investment Trust only holds if office vacancies such as 330 Front Street are managed well and industrial NOI pressure does not become entrenched.
Find out about the key risks to this H&R Real Estate Investment Trust narrative.
Another View: What HR.UN’s P/S Ratio Is Saying
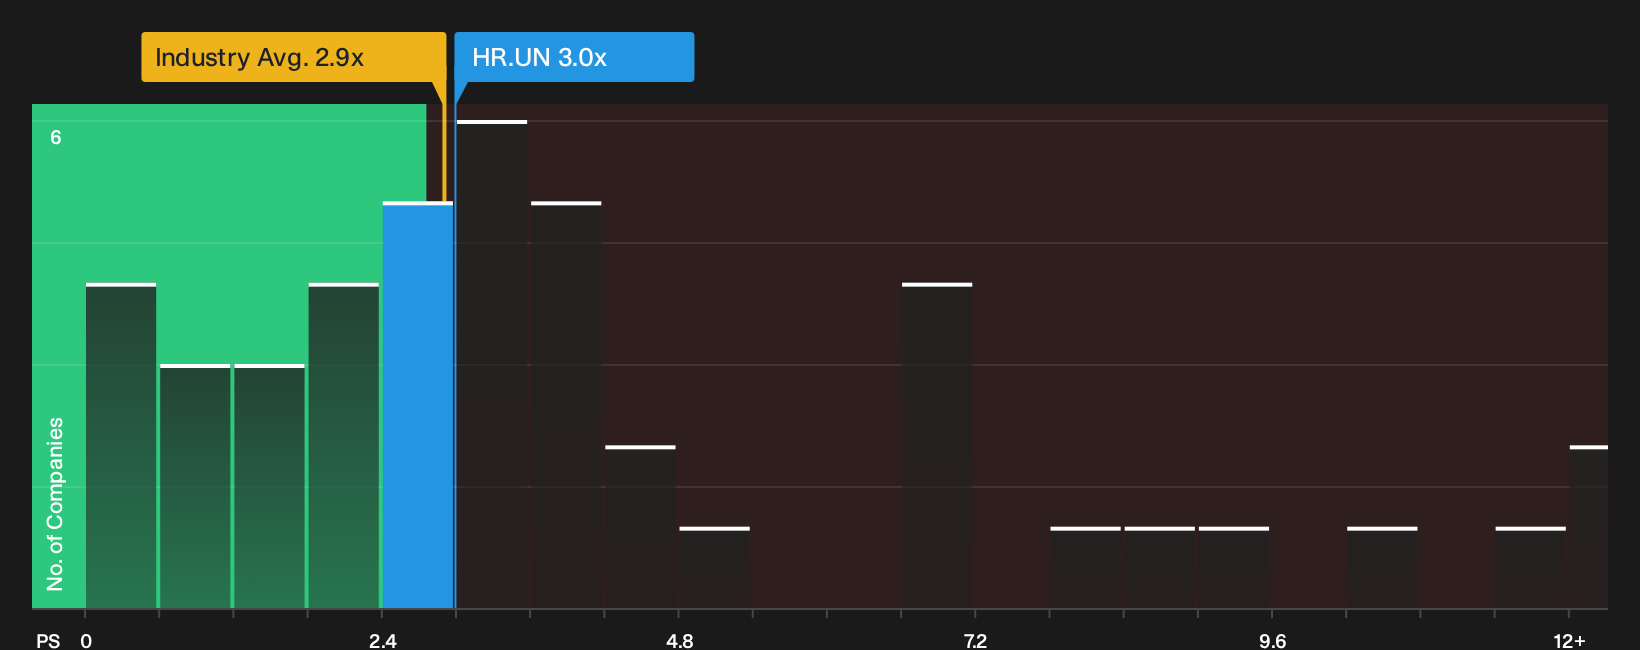
That CA$10.95 fair value hinges on earnings turning around, but today investors can also look at H&R Real Estate Investment Trust through its P/S ratio of 3x. That is slightly higher than the North American REITs industry at 2.9x, yet below a fair ratio estimate of 4.3x, which points to some valuation cushion if the market ever prices HR.UN closer to that fair ratio. The question is whether you see that gap as upside potential or compensation for execution risk.
For a grounded breakdown of how this pricing stacks up against peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around H&R Real Estate Investment Trust can feel messy, so move quickly to your own view by weighing both sides of the ledger and testing the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond H&R Real Estate Investment Trust?
If H&R Real Estate Investment Trust has sharpened your focus, use that momentum and quickly size up a few other opportunities that could suit different parts of your portfolio.
- Target potential mispricings by scanning a curated set of 5 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Strengthen the defensive side of your holdings by filtering for a list of solid balance sheet and fundamentals (5 results) that can better handle shocks and funding pressure.
- Get ahead of the crowd by combing through 8 high quality undiscovered gems where quality metrics look appealing but broader attention still feels limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com