


EN
Is Sylvamo (SLVM) Undervalued After Its Earnings Loss And Sales Decline?
What Sylvamo’s Latest Earnings Signal For Investors
Sylvamo (SLVM) just posted third quarter 2026 results that flipped from a prior profit to a net loss, with quarterly sales lower than the same period a year earlier.
Sylvamo’s share price sits at US$38.57, with a sharp 16.63% 7 day share price return and a 19.89% 30 day share price return suggesting a short burst of momentum after a weak year to date share price return of 19.28% and a 1 year total shareholder return decline of 13.12%.
That rebound has arrived alongside the third quarter earnings release, which put a spotlight on the swing to a loss and likely reframed how investors weigh Sylvamo’s cash generation, balance sheet strength and long term potential against recent operational setbacks.
Spot opportunities beyond Sylvamo’s sharp swing by scanning our hand picked 32 high quality undervalued stocks, built to highlight resilient balance sheets and stronger recent execution.Bulls see Sylvamo’s long established brands and mills on sale after a sharp earnings hit, while bears see a value trap forming. Which case does the current valuation actually support?
Most Popular Narrative: 16% Undervalued
On the analyst consensus Narrative on Simply Wall St, Sylvamo’s fair value sits at $45.80 compared with the latest close of $38.57, which frames the recent loss making quarter as a potential mispricing rather than a permanent reset.
The current valuation implies that the market is heavily discounting Sylvamo’s potential to reach its more than US$300 million annual free cash flow ambition and higher returns on invested capital, in spite of the company’s low-cost Brazilian assets, extended debt maturities, and planned cost savings.
See why 4 investors see Sylvamo as 16% undervalued.
The Narrative uses an 8.87% discount rate and ties that $45.80 fair value to a path where revenue trends, margin rebuild and capital spending eventually support higher free cash flow, while still acknowledging the execution and industry risks already reflected in the share price.
On that view, the recent swing from profit to loss and weaker profit margin of 2.7% compared with 8.4% a year ago reads more as a period of heavy adjustment rather than the end of Sylvamo’s earnings power, with the model assuming that planned cost programs and mill upgrades can restore returns over time.
Result: Fair Value of $45.80 (UNDERVALUED)
Still, that 2027 cash flow reset story for Sylvamo could be knocked off course if European pricing stays weak or if changes in the North American footprint weigh on volumes for a longer period.
Find out about the key risks to this Sylvamo narrative.
Another View: Sylvamo On Earnings Multiples
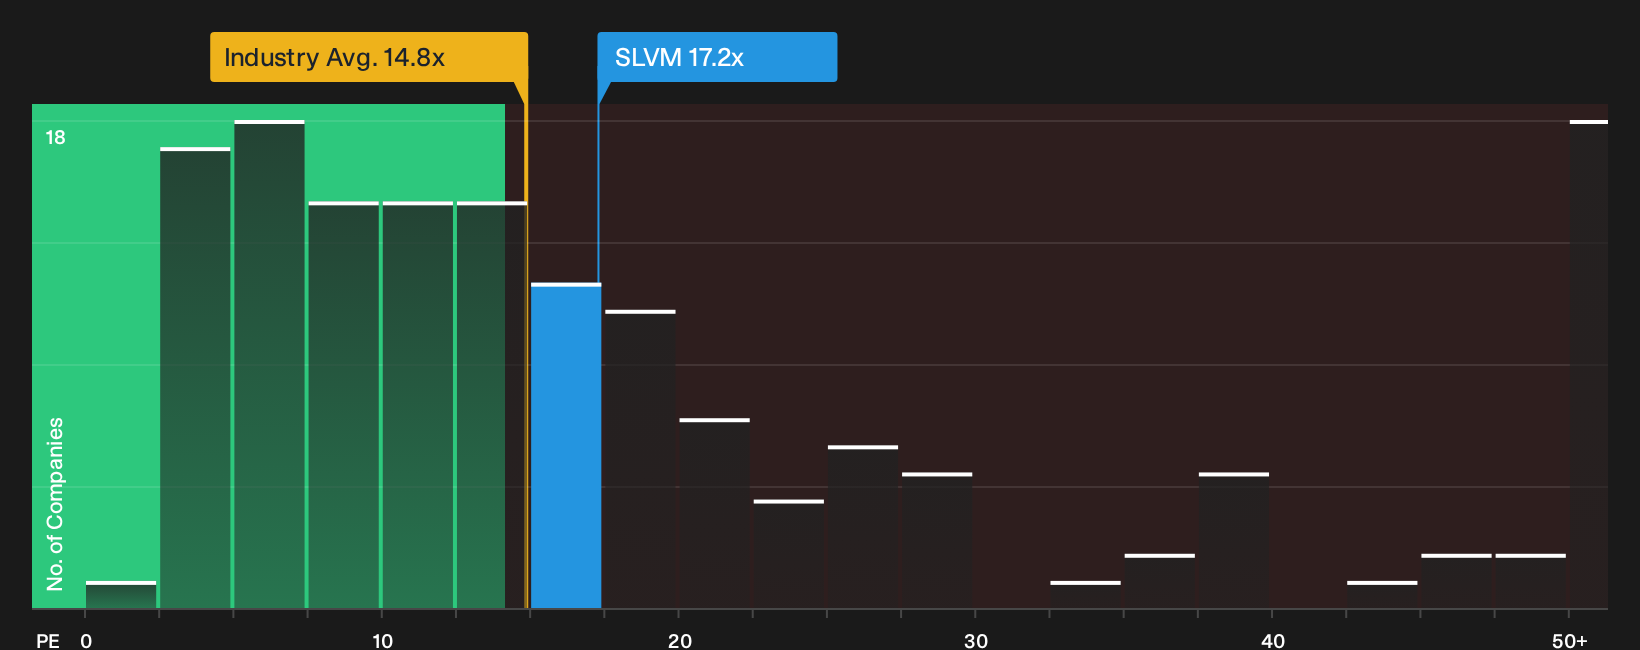
Sylvamo might look inexpensive compared with analyst fair value, yet the current P/E of 17.2x is higher than the global forestry group at 14.6x, even though profit margins have slipped from 8.4% to 2.7%. That difference indicates investors may be paying a premium today. Is the underlying narrative strong enough to justify that valuation?
For a closer look at how current pricing compares with what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Sylvamo’s recent results and valuation mean the real call now is yours, so review both sides of the story and weigh the 2 key rewards and 3 important warning signs
Looking For More Ideas Beyond Sylvamo?
If Sylvamo has you thinking harder about valuation, do not stop at one ticker. Cast a wider net so you are not missing better options.
- Target reliable income by reviewing a focused set of companies with durable payouts using the 6 dividend fortresses.
- Hunt for high quality businesses trading below their estimated worth through the hand picked 32 high quality undervalued stocks.
- Prioritise peace of mind by scanning financially resilient candidates with strong balance sheets in the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com