


EN
Did Earnings Beat Just Shift Howmet Aerospace (HWM) Investment Narrative?
- Howmet Aerospace recently reported third quarter 2026 results that exceeded earnings and revenue expectations, raised its full year outlook, and closed the acquisition of Consolidated Aerospace Manufacturing while continuing dividends and share repurchases, all supported by strong commercial and defense aerospace demand.
- The striking angle is how higher guidance, robust spare parts demand and the CAM fasteners acquisition all lean on the same theme: Howmet Aerospace is trying to convert intense aerospace and industrial turbine demand into durable margins and cash flow despite heavier investment and integration work.
- We will now see how Howmet Aerospace's raised full year outlook could reshape the existing investment narrative built around capacity expansion.
Howmet Aerospace Investment Narrative Recap
To own Howmet Aerospace, you need to believe the analyst consensus narrative on Simply Wall St that strong commercial and defense aerospace demand, plus industrial gas turbines, can support capacity additions and keep margins healthy. The raised 2026 outlook supports that view in the near term. The key short-term catalyst is clean execution on higher volumes without operational hiccups.
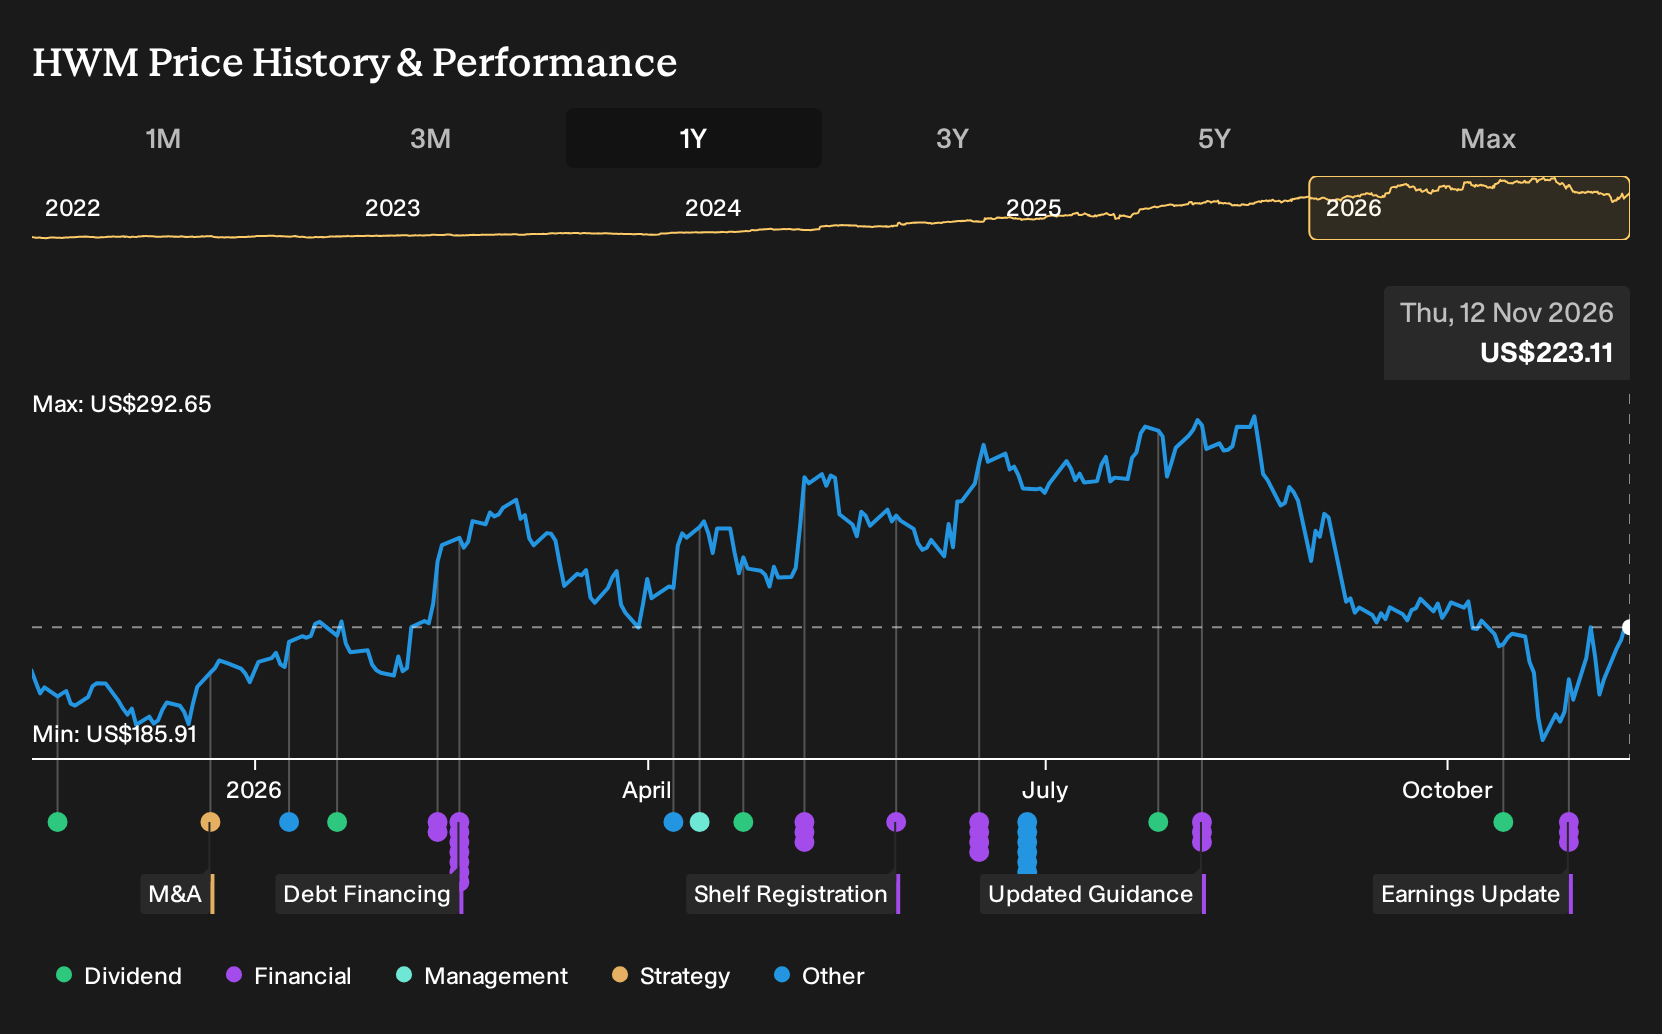
The biggest current risk is that sentiment cools after a share price move of roughly 7x to 8x in five years and some work flagging about 20% overvaluation. If investors decide to apply a lower P/E multiple, even with forecast earnings delivered, recent guidance tweaks would not materially offset that valuation pressure.
The most relevant recent development is management lifting earnings guidance for 2027 and putting a US$5b share repurchase plan on the table. That sits on top of the latest beat and raise quarter and signals confidence that capacity investments and the CAM fasteners integration can feed into future cash generation.
For you as a shareholder, the announcement ties straight into the main catalyst and risk. Stronger projected free cash flow supports buybacks at a time when the stock already trades on a 43.2x P/E versus a 32.7x fair P/E estimate and above both industry averages and DCF value. If execution on expansions, turbine demand and spares mix falls short, that leverage cuts both ways.
Howmet Aerospace's current analyst narrative points to revenues of US$13.9b and earnings of US$3.4b by 2029. These projections are built on forecast revenue growth of 12.7% per year and an earnings step up of roughly US$1.3b from the US$2.1b reported today.
Uncover how Howmet Aerospace's fair value indicates a 37% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Howmet Aerospace's aftermarket catalyst instead of valuation risk. Before this latest update, the bullish camp was already pencilling in revenue near US$14.6b and earnings around US$3.9b by 2029. That is a much richer story, and these new results could push those viewpoints to shift again.
Explore 5 other Howmet Aerospace fair value estimates, including one that suggests potential upside of as much as 68% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on thorough research.
- A great starting point for your Howmet Aerospace research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Howmet Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Howmet Aerospace's overall financial profile at a glance.
Looking for more investment ideas beyond Howmet Aerospace?
If you like the way the Howmet Aerospace story links real business drivers to valuation, you can use the Simply Wall St Screener to hunt for other companies that fit your style and risk tolerance.
- For investors who care most about valuation support and earnings quality, consider scanning a curated set of companies trading at what may be undemanding prices with robust fundamentals through our 32 high quality undervalued stocks.
- If capital preservation and a steadier ride matter more to you than chasing every rally, you might gravitate toward our 29 resilient stocks with low risk scores that filters for businesses with more resilient profiles.
- Readers who prize balance sheet strength and financial stability can start with a list of solid balance sheet and fundamentals (23 results) that surfaces companies supported by stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com