


EN
3 Australian Growth Stocks With Revenue Growth Up To 52%
AI related goods are now driving a large share of global trade growth, according to recent data showing AI enabling products responsible for most of the increase in goods flows this year. That kind of structural shift tends to reward fast growing Australian businesses where founders and executives still own meaningful stakes. This article highlights three such high insider ownership stocks that may help you tap into that momentum.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are clearly aligned with outside shareholders. However, if you want the standouts, these 24 high growth high conviction stocks are the most outstanding.
PDI Gold (ASX:PDI)
Overview: PDI Gold is a West Africa focused gold explorer and producer, centred on the Kiniéro Gold Mine as its main growth engine.
Operations: PDI Gold currently generates revenue mainly from Kiniéro at about $156 million and Nampala at about $47 million.
Market Cap: A$4.5b
PDI Gold fits this fast growing, high insider ownership theme because the Kiniéro Gold Mine is the key project management is building around, and the bullish analyst Narrative on Simply Wall St pushes that growth story further through an optimistic view on funding and expansion capacity.
"The cash and bullion position reported at about US$530m by June 2026 and US$364m by late September 2026 against US$130m of debt creates scope for PDI Gold to self fund a larger portion of Bankan and other growth options, which can limit future financing costs and support net margins."
Future returns hinge on how one crucial execution decision shapes the balance between higher output growth and the durability of those margins.
That execution choice is where things get interesting, and the full narrative for PDI Gold shows how management could balance accelerating output with keeping those margins resilient.

Barrenjoey Group (ASX:BJY)
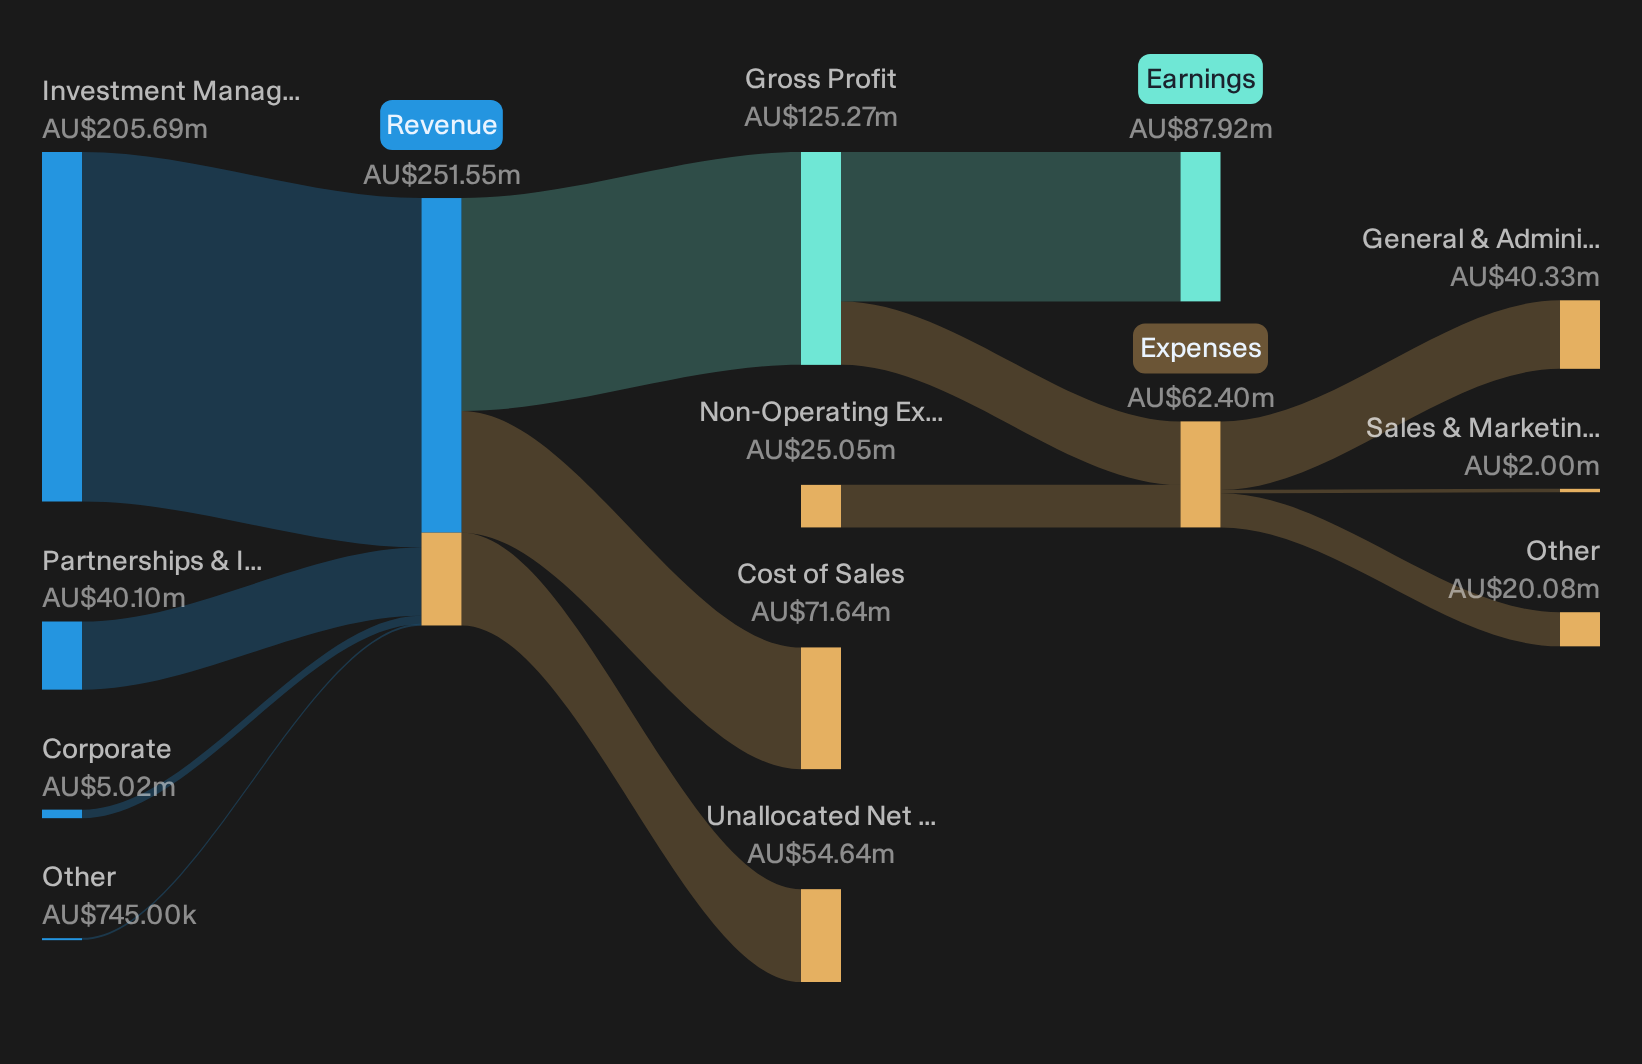
Overview: Barrenjoey Group is an Australian investment manager running global equity and global listed infrastructure funds that target higher growth opportunities.
Operations: Most revenue comes from Investment Management Services at about A$206 million, with Partnerships & Investments adding roughly A$40 million.
Market Cap: A$2.6b
Barrenjoey Group matters for this screener because its global equity and infrastructure franchises sit at the centre of the growth story that the analyst consensus Narrative on Simply Wall St links to performance fees and insider-aligned ownership.
"The growth of partnership income to A$25.7 million in the first half of FY26, accounting for 31% of operating profit and supported by contributions from Barrenjoey and Vinva, points to a larger role for capital light fee streams that can affect future margins and profit mix."
What happens when one pressure on those fee streams shifts will likely determine how strongly that earnings profile actually feeds through to shareholders.
That tipping point on fee pressure is exactly where the full narrative for Barrenjoey Group shows how Barrenjoey Group could turn partnership income into accelerating, more resilient earnings power.
Codan (ASX:CDA)
Overview: Codan designs and sells communications systems and Minelab metal detectors for gold mining, demining, military and recreational customers worldwide.
Operations: Codan generates about A$506 million from Communications and A$362 million from Metal Detection, with additional revenue from smaller unallocated activities.
Market Cap: A$10.0b
Codan fits this fast growing, high insider ownership theme through Minelab’s exposure to gold detection and demining markets. The analyst consensus Narrative on Simply Wall St points to strong earnings momentum supported by growing demand across both metal detection and mission critical communications.
"Heightened defense and security demand for unmanned and secure communications, reflected in approximately $215m of unmanned revenue in FY26 and a Communications order book of $380m that is 50% higher year on year, points to further growth potential in segment revenue and earnings if these orders continue to convert."
What happens if a single supply constraint or tax shift starts to pinch that growth curve will matter a lot for Codan’s margins.
That pressure point is exactly where the full narrative for Codan maps how Codan could turn supply risks into accelerating earnings power without losing pricing discipline.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not wait. Breakout stories move, momentum builds, and slow movers may end up chasing stocks that are already rising. Scan these under the radar ideas while it matters and consider them early in your process.
- Search for resilient cash generators with strong balance sheets before institutions increase their focus by scanning the curated list of solid balance sheet and fundamentals (12 results).
- Identify possible future AI leaders while sentiment is still forming by reviewing the focused list of 43 profitable AI stocks that aren't just burning cash.
- Review potential uranium infrastructure ideas by checking the tightly filtered 17 nuclear energy infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com