


EN
Kaneka (TSE:4118), Why Is Fresh Attention Building Now?
Kaneka board meeting puts fresh focus on earnings and dividends
Kaneka (TSE:4118) drew attention on 11 November 2026 after its board met to consider revisions to the consolidated earnings forecast and dividend outlook for the year ending 31 March 2027, a decision point closely watched by shareholders.
That boardroom decision comes after a powerful run in Kaneka’s shares. The stock is at ¥6,533 with a year-to-date share price return of 47.21%, while the 1-year total shareholder return of 59.94% and 5-year total shareholder return of 90.97% point to momentum that investors are now reassessing in light of the revised earnings and dividend outlook.
Scan how Kaneka’s latest forecast rethink compares with other material stocks that are under fresh earnings pressure by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Kaneka appears to be a solid chemicals and materials platform, and the recent share price surge underlines that reputation. After this run and the revised forecasts, is that strength already fully reflected in the valuation?
Price-to-Earnings of 11.4x: Is it justified for Kaneka?
Kaneka trades on a P/E of 11.4x. With the last close at ¥6,533, that earnings multiple points to a valuation that looks restrained compared with peers despite the strong recent share price run.
The P/E ratio compares what investors pay for each unit of current earnings. For a diversified chemicals and materials group like Kaneka, which spans PVC, advanced polymers, healthcare products and food ingredients, this benchmark helps you gauge how the market is pricing the existing profit base rather than distant forecasts.
Kaneka has high quality earnings and profits that have grown by 4% per year over the past 5 years, with earnings growth of 32% over the last year and net profit margins at 4% compared with 3.2% previously. Against that backdrop, a P/E of 11.4x that is below both the peer average of 13.6x and the JP Chemicals industry average of 11.6x suggests the market is applying a relatively cautious tag to its earnings, even though the stock has outperformed the JP Chemicals sector and the wider JP market over the past year.
The fair P/E ratio is estimated at 12x, so the current 11.4x level is meaningfully lower than where the valuation could trend if sentiment aligned more closely with that fair value benchmark.
Explore the SWS fair ratio for Kaneka.
Result: Price-to-Earnings of 11.4x (UNDERVALUED)
Still, Kaneka faces pressure from modest annual revenue growth of 1.77% and a slight decline in net income of 0.89%, which could temper the current valuation narrative.
Find out about the key risks to this Kaneka narrative.
Another view on Kaneka’s value
The P/E makes Kaneka look modestly cheap, yet the SWS DCF model tells a different story. On that cash flow view, the shares trade above an estimated value of ¥6,017.67, which points to an overvalued reading. Which lens should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
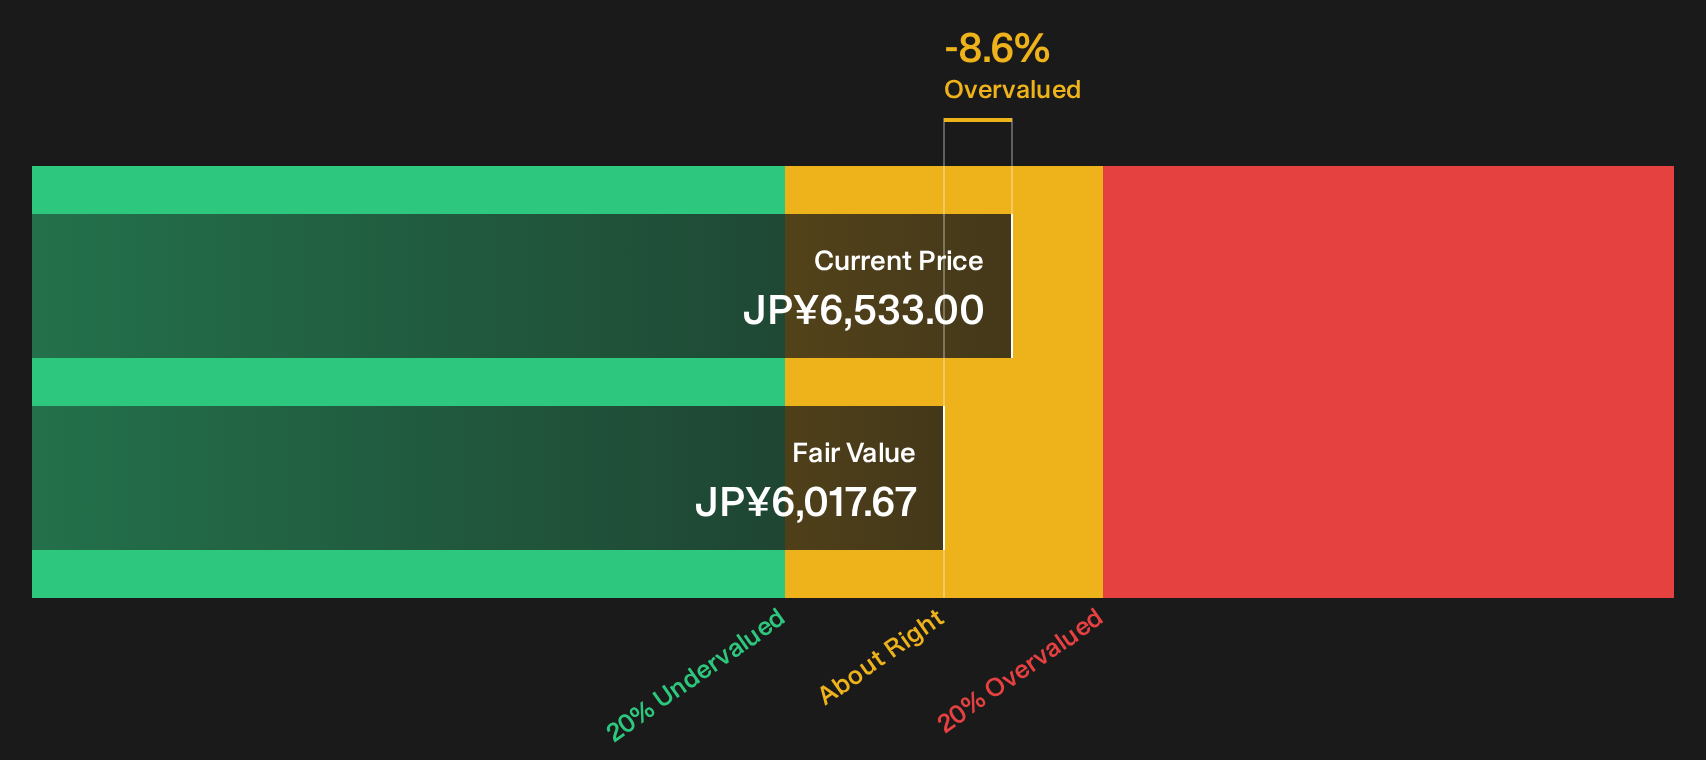
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kaneka for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kaneka’s valuation and outlook can feel confusing, so move quickly from headlines to hard facts and build your own view using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kaneka?
If Kaneka has sharpened your interest, do not stop here. The market is full of opportunities that fit different risk levels, income goals, and growth plans.
- Target long term wealth builders by scanning companies on our 19 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their strengths.
- Lock in potential income streams by reviewing a hand picked group of 28 dividend fortresses that focus on strong yields with supporting financials.
- Prioritise capital preservation first by checking out a curated 20 resilient stocks with low risk scores designed for investors who want resilience front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com