


EN
Maze Therapeutics (MAZE) Stock Looks Pricey As Phase 2 Plans Advance
Maze Therapeutics has delivered a sharp move over the past month, which puts fresh attention on whether the recent pricing lines up with what its balance sheet supports. With traders reacting to both trial progress and cash on hand, the open question is how closely the stock now tracks its underlying book value.
- The share price has climbed 35.4% over the past month, which puts more weight on whether that swing is in step with the value implied by Maze Therapeutics' net assets.
- The company recently reported cash of US$477 million that management expects to fund operations for several years, which can affect how investors weigh future capital needs against current book value.
- Your read on Maze Therapeutics is one view; the desks covering it have another. See what analysts think Maze Therapeutics's shares could be worth.
The stock's next move may depend on whether Maze Therapeutics' current market price still lines up with what investors are willing to pay relative to its book value.
If you are weighing Maze Therapeutics against what its balance sheet supports, it can help to see how that same question looks across solid balance sheet and fundamentals stocks screener (23 results).
Does Maze Therapeutics Look Pricey on Book Value?
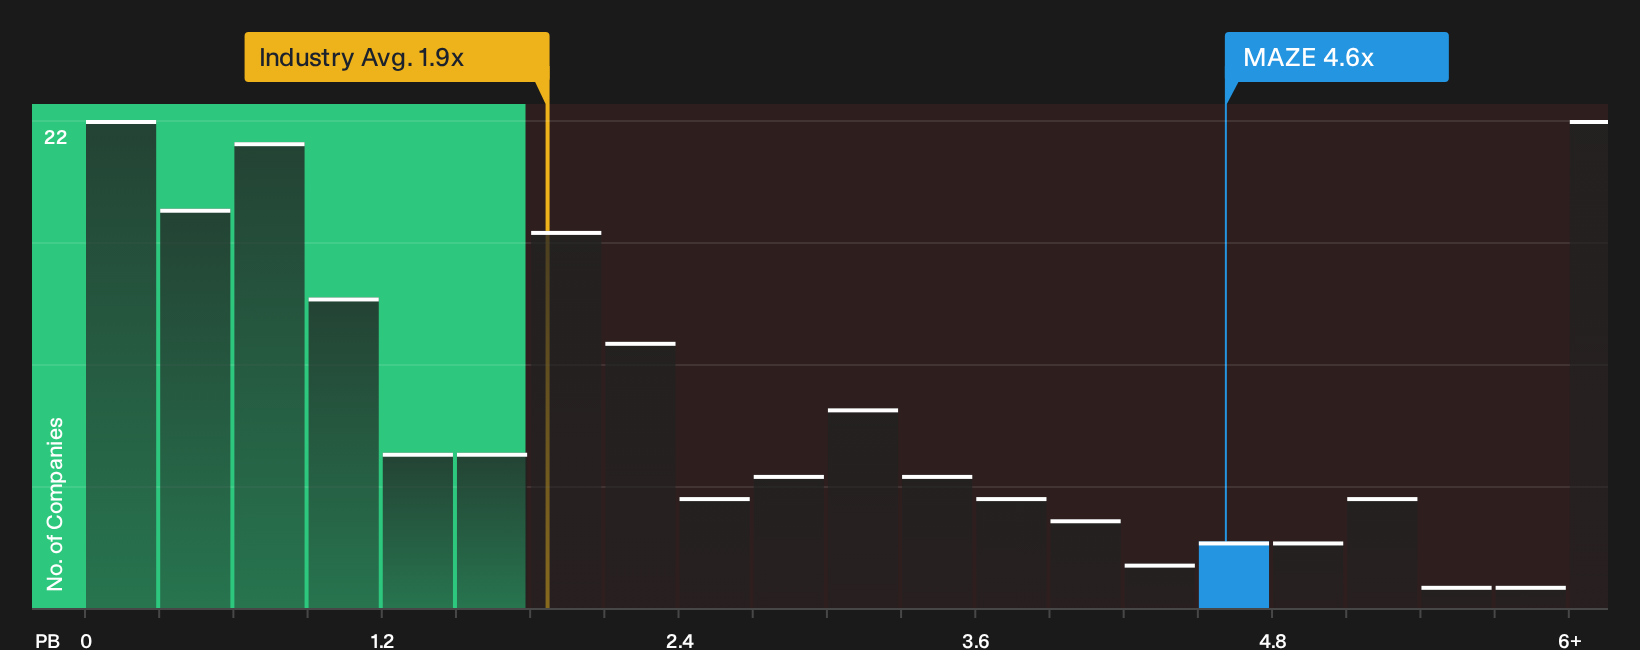
P/B fits Maze Therapeutics because investors are mainly weighing cash and research assets rather than current earnings power. The stock trades on a P/B of 4.6x, compared with a Pharmaceuticals industry average of about 1.9x and a peer group around 4.2x. That puts Maze on a premium to the sector and slightly above closer comparables that are also valued heavily on their balance sheets.
Because Phase 2 progress has put Maze’s clinical pipeline in the spotlight, the higher multiple suggests the market is already assigning extra value to future trial outcomes relative to the current equity base. Despite that momentum, the gap between 4.6x and the broader industry still screens the shares as overvalued on book value alone, so you would need to judge whether the pipeline and cash runway justify paying that sort of mark up. Explore the numbers behind Maze Therapeutics's P/B valuation.
The Maze Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Maze Therapeutics' price to book puzzle leaves off and spell out which expectations on growth, margins and future earnings would need to hold for the valuation to look much higher or lower than today. Each scenario pins its number to a clear view of how Maze Therapeutics' growth path, profitability profile and risk picture might evolve, which you can revisit as fresh information comes through.
One of the top narratives on Maze Therapeutics: 64% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The current valuation implies that the market is not fully pricing in the potential for Maze Therapeutics to reach the blockbuster revenue levels some covering banks are assuming for MZE829..."
Discover why this Narrative puts Maze Therapeutics at 64% undervalued.
The Maze Therapeutics story is not complete without its risk checks
Price and book value only tell part of the Maze Therapeutics story, because Simply Wall St's broader review has also flagged specific concerns that readers may want to weigh before making any decision. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com