


EN
Herbalife (HLF) Stock Looks Reasonable Despite Its 62% Five Year Drop
Herbalife has staged a sharp rebound over the past year, yet the longer track record tells a very different story, which puts fresh focus on whether the current share price is properly grounded in its earnings power. With that backdrop, the key issue for you is whether the latest optimism lines up with what the business is actually making per share.
- Herbalife shares are still down 62.5% over 5 years. Any assessment today has to weigh a steep long term drawdown against what the company is earning now.
- Recent reports of higher sales and an improved adjusted EBITDA margin suggest the nutrition-focused business may support different expectations for profit sustainability. That in turn feeds directly into how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Herbalife worth weighing. See what analysts think Herbalife's shares could be worth.
The issue now is whether Herbalife's current valuation can be reconciled with its earnings, given both the long slide over 5 years and the more recent share price recovery.
If you are weighing Herbalife against other earnings driven stories, it can help to compare it with companies filtered for solid balance sheets and fundamentals through the solid balance sheet and fundamentals stocks screener (23 results).
Does Herbalife Look Undervalued on Earnings?
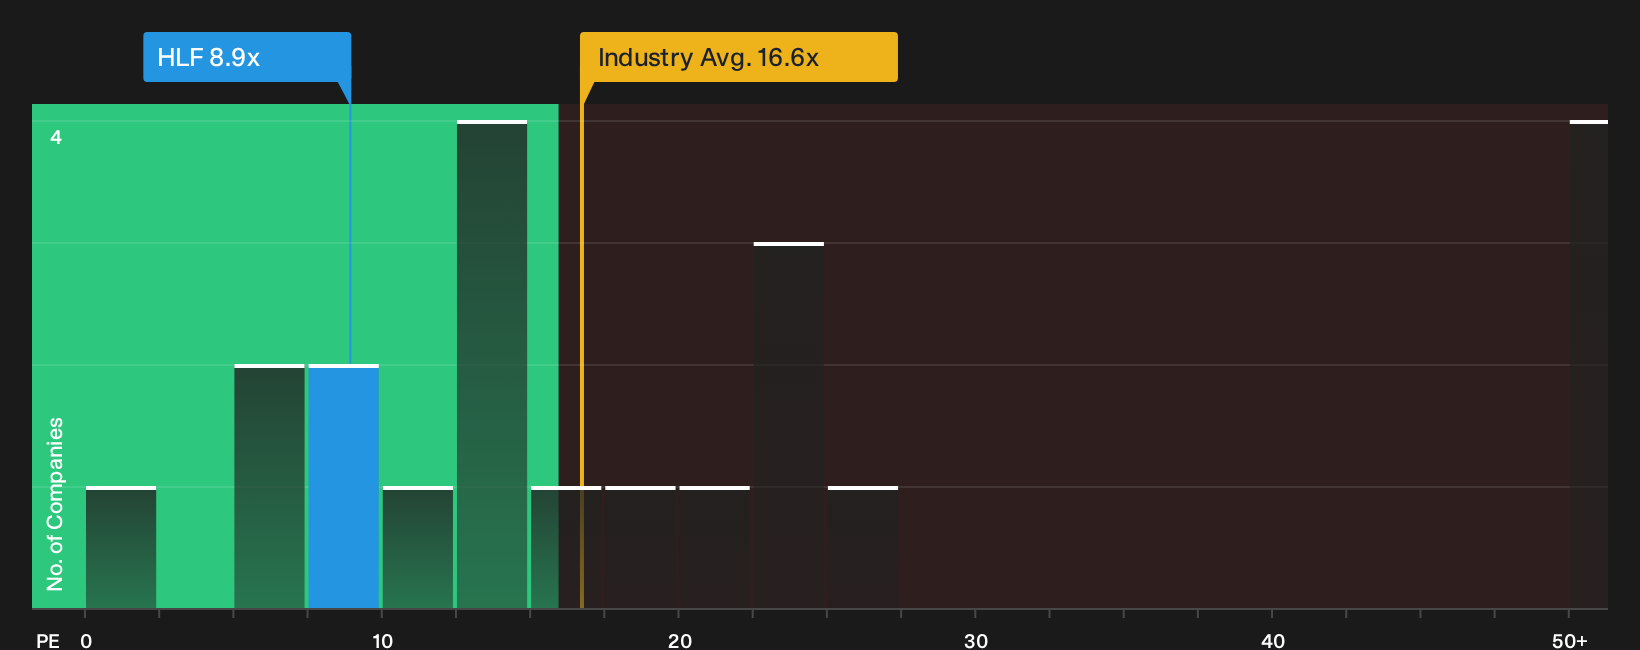
The P/E ratio is a useful lens for Herbalife because it ties the current share price directly to what the nutrition group is earning per share. Herbalife trades on a P/E of about 8.9x, which is far below the Personal Products industry average of roughly 16.6x and even further beneath a broader peer group around 32.0x. On a simple earnings multiple check, the stock changes hands at a marked discount to both its sector and similar businesses.
Because the latest modelled fair P/E, which reflects Herbalife's own mix of growth prospects, profitability and risk, sits above today’s 8.9x figure, the shares screen as undervalued on this framework. Despite Q3 2026 earnings coming in ahead of expectations and management outlining expansion plans, the current P/E still prices Herbalife below what many investors might expect to pay for those earnings. Explore the numbers behind Herbalife's P/E valuation.
The Herbalife Narrative: What Would Justify Today's Price?
Herbalife Narratives pick up where the valuation puzzle leaves off and explain what kind of future path for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on Simply Wall St's Community page. Each scenario links a fair value estimate to a specific storyline about Herbalife's potential catalysts and key risks, allowing you to track over time which version of events appears to be taking shape.
Herbalife currently sits between two very different narratives, one highlighting cautious pricing relative to improving cash generation and the other arguing that execution risk already appears fully reflected in the stock.
Bull case: 11% undervalued
This perspective comes from the analyst consensus Narrative on Simply Wall St and links potential upside to cash flow, debt reduction and subscriptions.
"Stronger free cash generation, lower leverage following approximately US$540 million of debt repayment since early 2024, interest savings of about US$45 million a year from the 2026 refinancing, and the addition of a US$250 million three year buyback program alongside planned further debt reduction can increase flexibility for capital deployment, which may support earnings per share and reduce equity risk premia embedded in Herbalife’s valuation…"
Discover why this Narrative puts Herbalife at 11% undervalued.
Bear case: 52% overvalued
The bearish analyst Narrative on Simply Wall St takes the opposite view and argues that the current Herbalife price already assumes smooth execution of a complex plan.
"The numbers in the current guidance range, balance sheet plan, and cash generation profile suggest that the share price already reflects successful execution of Herbalife’s growth, margin rebuild, and deleveraging ambitions, which this narrative views as over-optimistic and therefore bearish…"
Explore why this Narrative puts Herbalife at 52% overvalued.
Herbalife’s valuation still hinges on one unresolved issue
Price, earnings and scenarios are only part of the puzzle, because the people steering Herbalife and the way their rewards are structured can heavily influence how those plans play out. See who runs Herbalife and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com