


EN
Top 3 British Undervalued Stocks To Watch In November 2026
Global oil supply has moved back into surplus according to the IEA, and that shift puts cash front and center for UK value hunters. When energy markets stop looking scarce, investors often pay closer attention to what each pound of free cash flow is worth. This article highlights three United Kingdom listed stocks where current cash flow potential screens as attractive relative to estimated fair value based on discounted cash flow analysis.
The three stocks below are just a starting sample, since the full DCF based screen surfaced 20 more UK listed companies with equally cash rich stories that are not covered in this article.
Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the cash flow opportunities that best match your own value checklist.
Premier Foods (LSE:PFD)
Premier Foods is a packaged-foods group whose long established ambient Grocery and Sweet Treats brands generate the kind of steady cash flows that matter for this DCF focused screener.
Premier Foods manufactures mainly branded ambient food products, with Grocery generating about £860 million of revenue and Sweet Treats adding roughly £315 million. The business, valued at around £1.68b by market cap, sells through supermarkets, convenience outlets, wholesale channels and online.
The analyst consensus Narrative on Simply Wall St argues that one key project set could be central to how Premier Foods turns its cash generative brands into stronger long term economics.
"Planned step up in annual CapEx to a range of £55 to £60m in FY27, directed at automated cake lines, insourced sauce capacity, new process plants and energy projects such as efficient boilers and solar arrays, is intended to lower unit costs and improve factory recovery which can support gross margin and trading profit progression."
What happens if a single assumption about future pricing power proves either too cautious or too generous will be critical for investors.
If that pricing power question is front of mind, read the full narrative for Premier Foods to see how Premier Foods' cash engine could accelerate or stall from here.
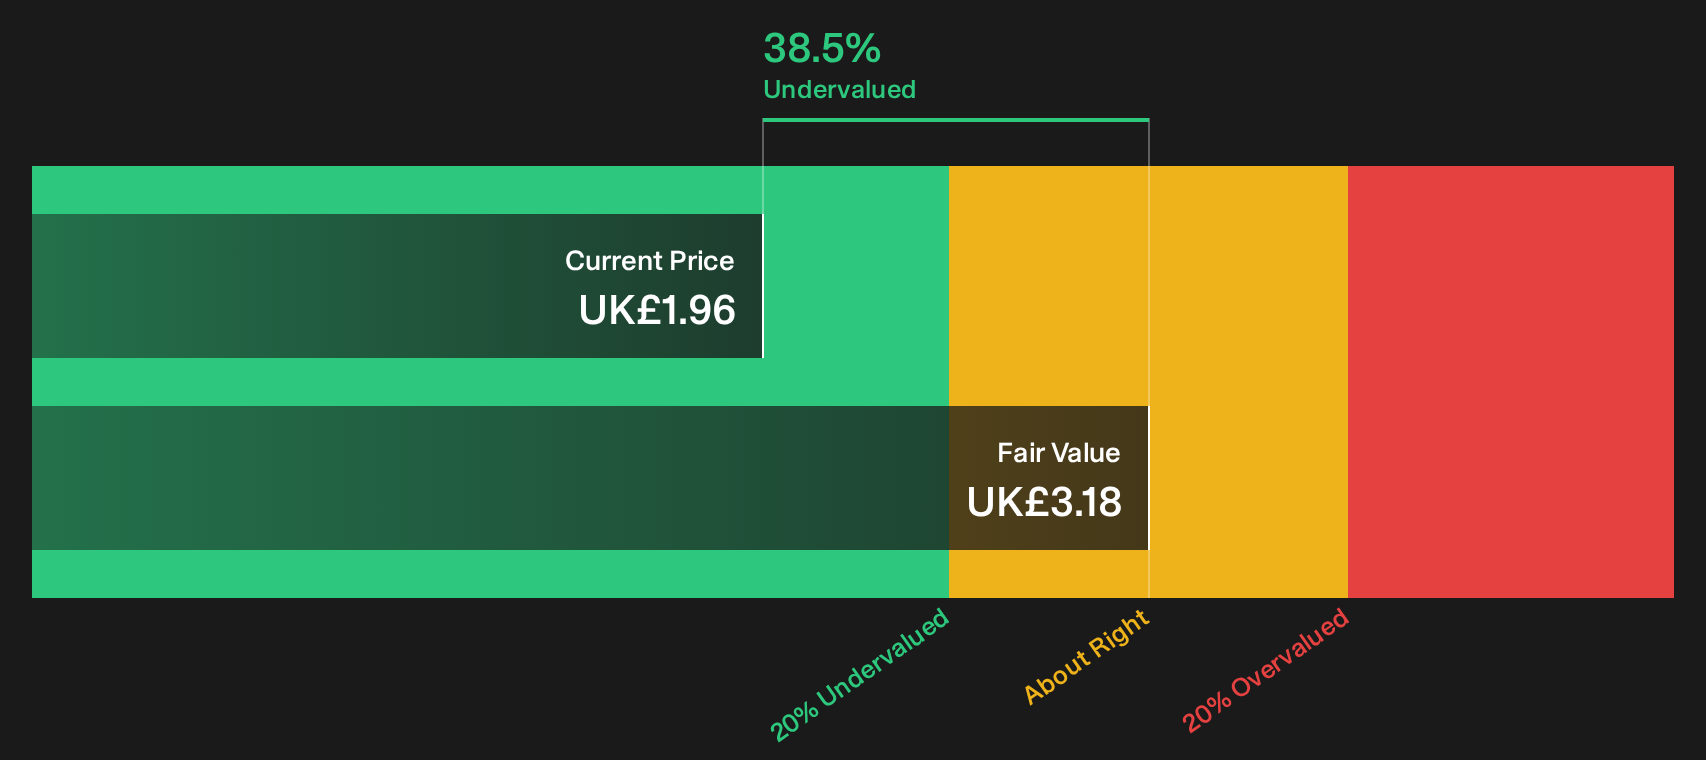
BAE Systems (LSE:BA.)
BAE Systems is a defence and aerospace group whose long term contracts in high margin electronics, vehicles and munitions align closely with this cash flow focused screen, and the analyst consensus Narrative on Simply Wall St highlights why that forward visibility matters for value driven investors.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and points to multi year support for revenue and earnings."
The real swing factor is how one large capacity and mix shift filters through into margins and free cash generation over time.
BAE Systems is a global defence, aerospace and security group, with sizeable revenue from Electronic Systems of about £7.8b and Platforms & Services at roughly £5.3b, plus similar scale Air and Maritime activities, and the business currently carries a market value close to £53.6b.
That free cash flow question is the crux, and the full narrative for BAE Systems shows how BAE Systems' backlog, capital needs and payout ambitions could be decoupling under the surface.

Genus (LSE:GNS)
Genus is a specialist in animal genetics where the Genus PIC and Genus ABS units sell breeding pigs, dairy and bull semen, and embryos that create repeat, high margin cash flows. These segments generate about £355.8 million and £299.8 million of revenue respectively, with the group valued around £1.48b.
Genus slots into this cash flow focused list because the analyst consensus Narrative on Simply Wall St points to a genetics franchise that turns recurring royalty and semen sales into meaningful free cash generation, which is exactly the sort of engine this screener is looking for.
"The build out of Genus’ high margin, recurring PIC royalty model, including more than 50% royalty revenue growth in China on top of 6% group royalty growth in H1 FY26, points to further expansion of royalty driven revenue and operating profit as contracts mature and penetrate a larger share of global pig herds."
What really matters now is how one evolving pressure on future earnings shapes the value investors ultimately ascribe to those royalties.
As that earnings pressure builds, read the full narrative for Genus to see whether Genus' royalty engine is quietly setting up an accelerating, higher quality cash story.

Seeking Fresh Alternatives Before They Fly
New ideas move first, prices move next. Consider potential breakout stories while they are still under the radar for now and before momentum becomes widespread.
- Scan for income workhorses that aim to keep paying investors while prices swing, using the curated 5 dividend fortresses before yield opportunities start dropping.
- Explore infrastructure players involved in AI data centers and networking capacity, with the hand picked 53 AI infrastructure stocks while they are still building quiet momentum.
- Look for potential early stage names in robotics automation where demand trends can develop over time, starting with the focused 86 robotics and automation stocks while it still appears early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com