


EN
Is Keisei Electric Railway (TSE:9009) Fairly Valued Following Earnings And Fare Review Plans?
Earnings lift and fare review put Keisei Electric Railway in focus
Keisei Electric Railway (TSE:9009) moved into the spotlight after half year results showed higher sales and net income, and the board scheduled a November 6 meeting to consider revising passenger fares.
The recent earnings release and fare review plans landed after a strong run in Keisei Electric Railway’s shares. A 7 day share price return of 9.24% and a 30 day move of 14.33% have added to a 19.93% year to date gain. The 1 year total shareholder return of 26.26% contrasts with a 3 year total shareholder return that declined 23.79% and a 5 year total shareholder return of 35.50%, suggesting momentum has picked up again after a weaker stretch.
Scan how Keisei Electric Railway compares with other transport and infrastructure plays gaining fresh attention through our hand picked list of solid balance sheet and fundamentals (24 results)
Keisei Electric Railway now combines a long established network, growing half year earnings and a sharp share price jump. The key issue is whether that stronger story is already fully reflected in today’s valuation.
Price-to-earnings of 14.7x: Is it justified for Keisei Electric Railway?
On simple earnings maths, Keisei Electric Railway trades on a P/E of 14.7x, which is richer than several yardsticks investors often watch. The JP Transportation industry average sits at 12.2x and a peer group average is 12.4x. A fair value P/E derived from regression analysis is 15.3x, so the current tag is close to that implied level.
The P/E multiple compares the share price with earnings per share. For a business such as Keisei Electric Railway, with exposure to rail, buses and related services, this ratio is a quick way to see how much investors are paying for each unit of profit. A higher P/E can line up with expectations of steadier earnings or reduced risk. A lower figure can signal either caution or a lack of interest.
In this case, the market is valuing Keisei Electric Railway more highly than the wider transportation group. That higher rating is paired with a description of high quality earnings and a track record of the company becoming profitable over the past 5 years. At the same time, recent margins are lower than last year, earnings over the past year declined 31.4%, and analyst forecasts point to earnings growth of 4.4% per year that is slower than the broader JP market. The fair value P/E of 15.3x suggests the current 14.7x level is not far from where the market could tilt if those inputs hold.
Explore the SWS fair ratio for Keisei Electric Railway.
Result: Price-to-earnings of 14.7x (ABOUT RIGHT)
Still, a planned fare revision and a share price that already trades near a fair value P/E estimate both leave limited room if expectations slip.
Find out about the key risks to this Keisei Electric Railway narrative.
Another view on Keisei Electric Railway’s value
The P/E of 14.7x paints Keisei Electric Railway as roughly in line with its fair ratio of 15.3x, but the SWS DCF model tells a different story. On that measure, the current share price of around ¥1,531 sits well above an estimated future cash flow value of ¥525.07. That gap raises a simple question for investors: Which signal should carry more weight, earnings today or cash flows projected over time?
Look into how the SWS DCF model arrives at its fair value.
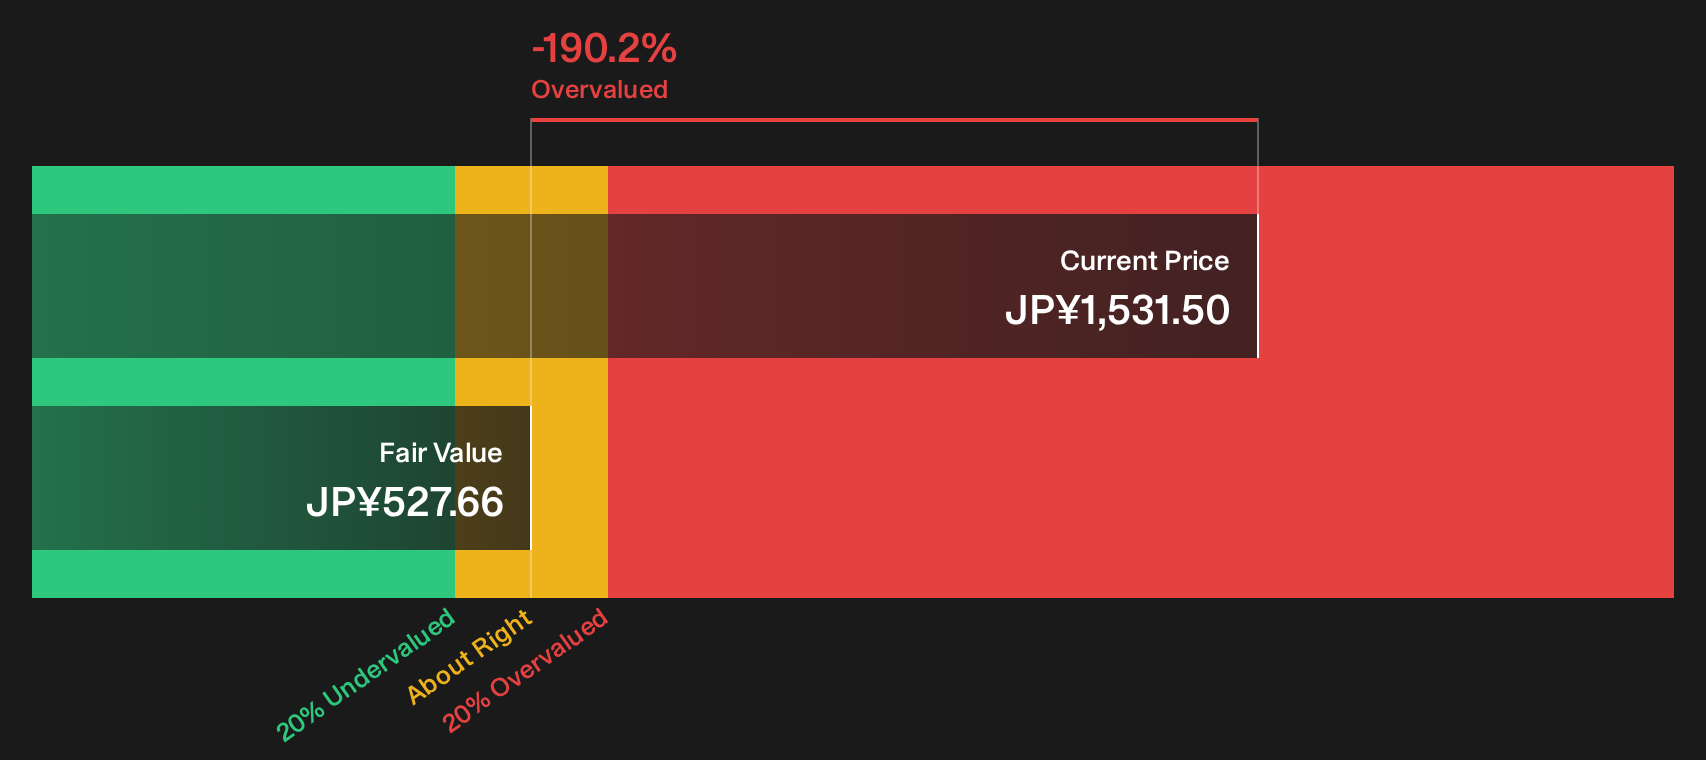
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Keisei Electric Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Keisei Electric Railway’s valuation and outlook can leave the picture feeling blurred. Move quickly, review the full data set yourself, and weigh both sides of the story by checking the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Keisei Electric Railway?
Do not stop your research with Keisei Electric Railway. Broaden your watchlist with focused stock ideas that match different goals and risk levels using the Simply Wall Street Screener.
- Target dependable income streams by scanning companies described as dividend fortresses through the 28 dividend fortresses.
- Hunt for quality businesses that trade below their assessed worth with the 19 high quality undervalued stocks.
- Prioritise capital resilience by filtering for companies flagged as 20 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com