


EN
3 Undervalued Stocks With Up To 50% DCF Upside
AI driven goods now dominate global trade growth, pulling more capital into headline tech plays and away from quieter cash generators. That leaves a pocket of companies where cash flows look promising while share prices lag behind what discounted cash flow work suggests. If you are worried about overpaying for hype, the next section walks through three stocks the screener flags as potentially mispriced on their cash fundamentals.
The three examples below are only a small sample, as the full screen surfaced 434 more companies that share similar cash flow appeal and valuation gaps but are not covered here. To go straight to the source and identify, compare, and analyze the highest conviction ideas, head into the Undervalued Stocks Based On Cash Flows screener
MINEBEA MITSUMI (TSE:6479)
Overview: MINEBEA MITSUMI manufactures precision bearings, motors, sensors, electronics and access hardware used across automotive, industrial, aerospace and home security applications.
Operations: Revenue is primarily generated from Semiconductors & Electronics of ¥624b, Motor, Lighting & Sensing of ¥510b, and Precision Technologies of ¥320b.
Market Cap: ¥1.2t
For this cash flow focused screen, MINEBEA MITSUMI matters because the analyst consensus Narrative on Simply Wall St highlights how its precision motors and sensors link long-term industrial and automotive demand to a concrete capacity build, with the potential to reshape profitability if that extra volume fills effectively.
"MinebeaMitsumi is expanding monthly ball bearing capacity from roughly 404 million units to over 460 million by late 2028 to serve AI server and data center demand, which could lift group revenue and support operating margin leverage as higher value bearings scale."
What really moves the needle for Minebea Mitsumi is how one unresolved margin pressure plays out against that future high value volume.
That margin tug of war is exactly what the full narrative for MINEBEA MITSUMI unpacks, including how capital intensity, pricing power and cash conversion might interact if demand continues to accelerate.

NSK (TSE:6471)
Overview: NSK is a global manufacturer of industrial bearings, automotive components and precision machinery that anchors the screener through its cash-flow-friendly bearings and motion-control products.
Market Cap: ¥496b
NSK fits this cash flow screen because its industrial bearings and precision components can create repeat orders that suit discounted cash flow analysis, and the bullish analyst Narrative on Simply Wall St argues that a key focus is how far management can push that profitability improvement.
"Faster than planned progress on operational improvements, with around ¥10b of the targeted ¥15b already realized over FY2024 to FY2025, gives NSK extra room to extend its structural reform program beyond the current plan and potentially convert recurring cost savings into higher operating margins than currently assumed in many models."
What matters for NSK now is whether one evolving pressure on pricing power quietly caps how much of those cost savings reach long term margins.
That pricing tension is exactly what the full narrative for NSK unpacks. It reveals where accelerating reforms, cash generation and long term risks could be getting misread by the market.

Netflix (NFLX)
Overview: Netflix runs a global subscription streaming service for TV, films, games and live programming, turning recurring memberships into substantial cash flows.
Operations: Virtually all revenue comes from the Streaming Entertainment Service, which generated about US$49.7b, supported by a broad international subscriber base.
Market Cap: US$265.0b
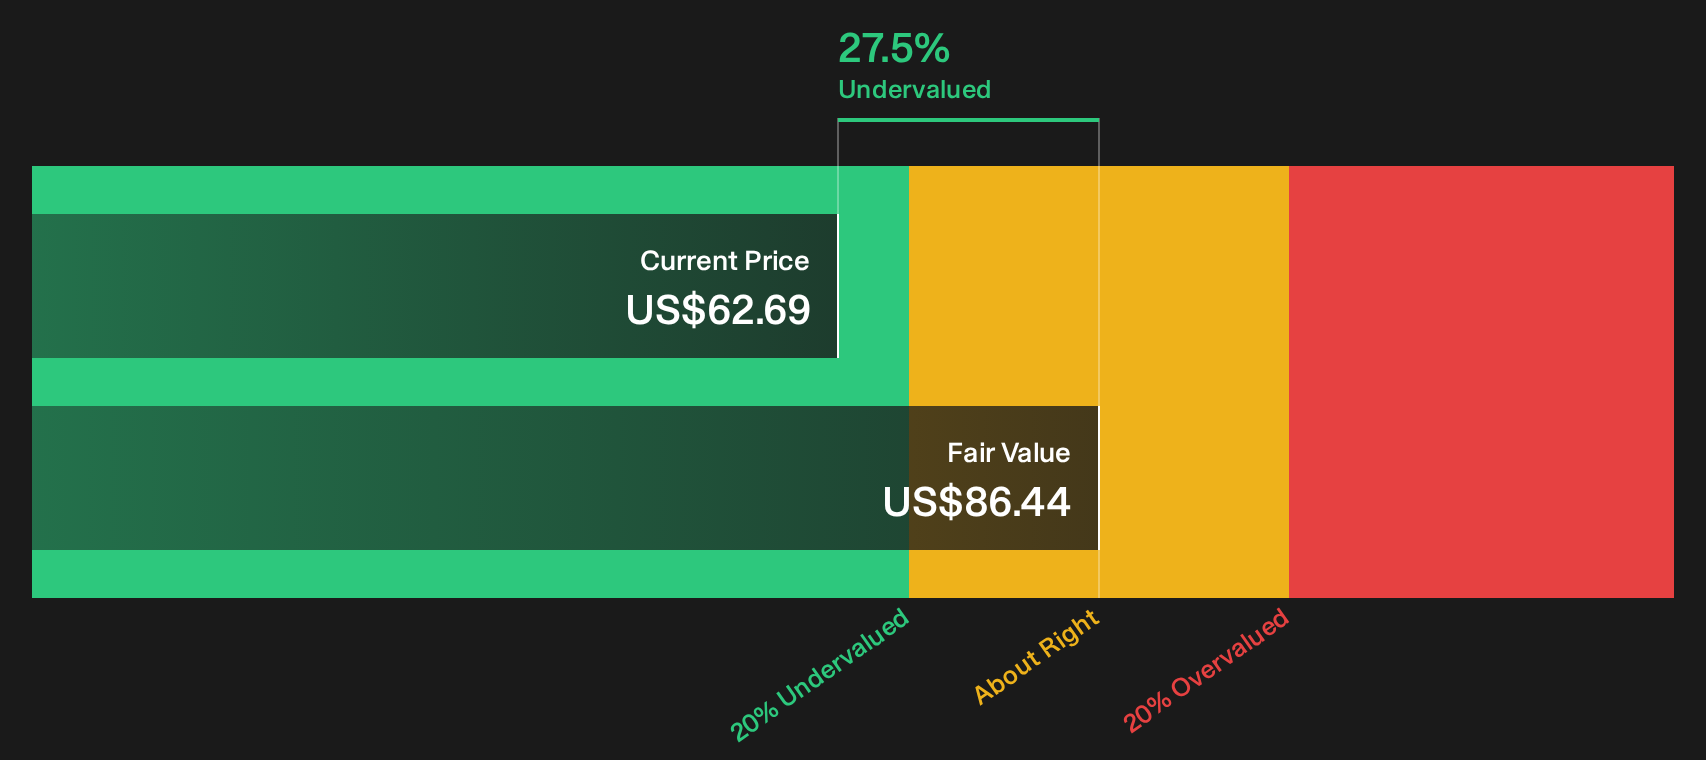
Netflix matters for this cash flow screen because its subscription engine already produces significant, repeatable cash, yet the market price still trails the DCF value that Ivoed, an investor in the Simply Wall St Community who wrote the analysis, thinks those cash streams support.
"The bull case is still very real, but it needs more than a good quarter. It needs proof that ads become economically meaningful, that pricing remains sticky, and that margin expansion can continue without damaging engagement."
What happens to that DCF gap depends heavily on how one emerging constraint shapes the balance between future pricing power and viewer loyalty.
That pricing power question is exactly what the full narrative for Netflix lays out in detail, highlighting how ads, engagement and accelerating cash generation could reshape the Netflix story.
Seeking Fresh Alternatives Beyond Today
Fresh ideas move first. By the time momentum is flying, early entry points are often gone. Scan under the radar for now, before the crowd, and get in early.
- Target resilient movers that hold up when others drop by scanning a curated pool of 20 resilient stocks with low risk scores before they get fully priced in.
- Hunt for yield that still looks supported by real cash generation by zeroing in on hand picked 27 dividend fortresses while income opportunities still look mispriced.
- Track the industrial backbone of future AI demand by focusing on carefully filtered 43 power grid technology and infrastructure stocks before grid upgrades become the headline story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com