


EN
3 Consumer Staples Stocks Offering Dividend Shelter as Rate Hike Talk Returns
Inflation is cooling on the surface, but PPI and CPI are still running hot enough to keep the Federal Reserve talking about more rate hikes. That mix has many investors rethinking how much risk they really want to carry. Higher borrowing costs can strain growth stories, yet can also refocus attention on durable cash flows and dividends. This article examines three stocks exposed to that inflation and rate backdrop that currently screen as defensive, dividend-paying value ideas.
The stocks covered below are just a sample, and the full defensive value screen surfaced 17 more U.S. companies with equally compelling income and balance-sheet stories that are not included here. To identify and analyze those additional candidates directly, head to the Defensive, Dividend-Paying Value Stocks in Non-Cyclical Sectors screener.
Dole (DOLE)
Dole is in this defensive dividend screen because fresh produce tends to be a staple in household budgets, even when inflation and rates are rising. The bearish analyst Narrative on Simply Wall St frames how that resilience meets some stubborn cost and execution questions.
"Although Dole is leaning into long term health and wellness demand for fresh produce, persistent spikes in fuel, fertilizer and shipping costs linked to climate events and geopolitical conflict are still feeding directly into higher cost of goods sold. This can keep EBITDA and net margins under pressure if pricing and surcharges lag these inputs."
What really matters now is how one quietly building pressure point ultimately shows up in Dole’s ability to turn steady demand into cash returns.
Dole is a global fruit and vegetable producer and distributor with a roughly US$1.3b market cap, supplying retailers and foodservice customers across multiple channels as part of the consumer staples universe that anchors this defensive screen. Revenue is primarily split between Fresh Fruit at about US$3.6b, Diversified Fresh Produce EMEA at roughly US$4.3b, and Diversified Fresh Produce Americas and ROW at around US$1.8b, with a small intersegment offset.
That pressure point is exactly where the full narrative for Dole picks up, mapping how Dole could turn cost headwinds into accelerating cash generation if execution tightens.

Nomad Foods (NOMD)
Nomad Foods brings everyday frozen meals, fish, vegetables and snacks into the defensive consumer staples theme, giving this screen another business where households tend to keep buying even when rates and inflation bite, which is exactly what the analyst consensus Narrative on Simply Wall St leans into.
"Broader frozen category expansion into Chicken, Meals, Potatoes, Pizza and Ice Cream, using existing brands and a pan European footprint, is expected to increase Nomad Foods’ addressable market roughly fourfold and supports a case for higher future revenue and EBITDA if the company converts current pilot successes into wider distribution."
The real swing factor is how one less visible cost and pricing trade off shapes margins as inflation and rate pressures ripple through.
Nomad Foods manufactures a broad range of branded frozen products for supermarkets and food retail chains, generating about €3 billion in Frozen Foods revenue, and its roughly US$1.6b market cap keeps it firmly mid sized within the defensive, dividend paying value screen.
That cost and pricing trade off is exactly where the full narrative for Nomad Foods accelerates the story, highlighting how Nomad Foods could turn category breadth into stronger earnings power.

John B. Sanfilippo & Son (JBSS)
John B. Sanfilippo & Son taps directly into the defensive, dividend paying consumer staples theme by selling everyday nut products and snack bars that tend to stay in household baskets even when rates and inflation bite.
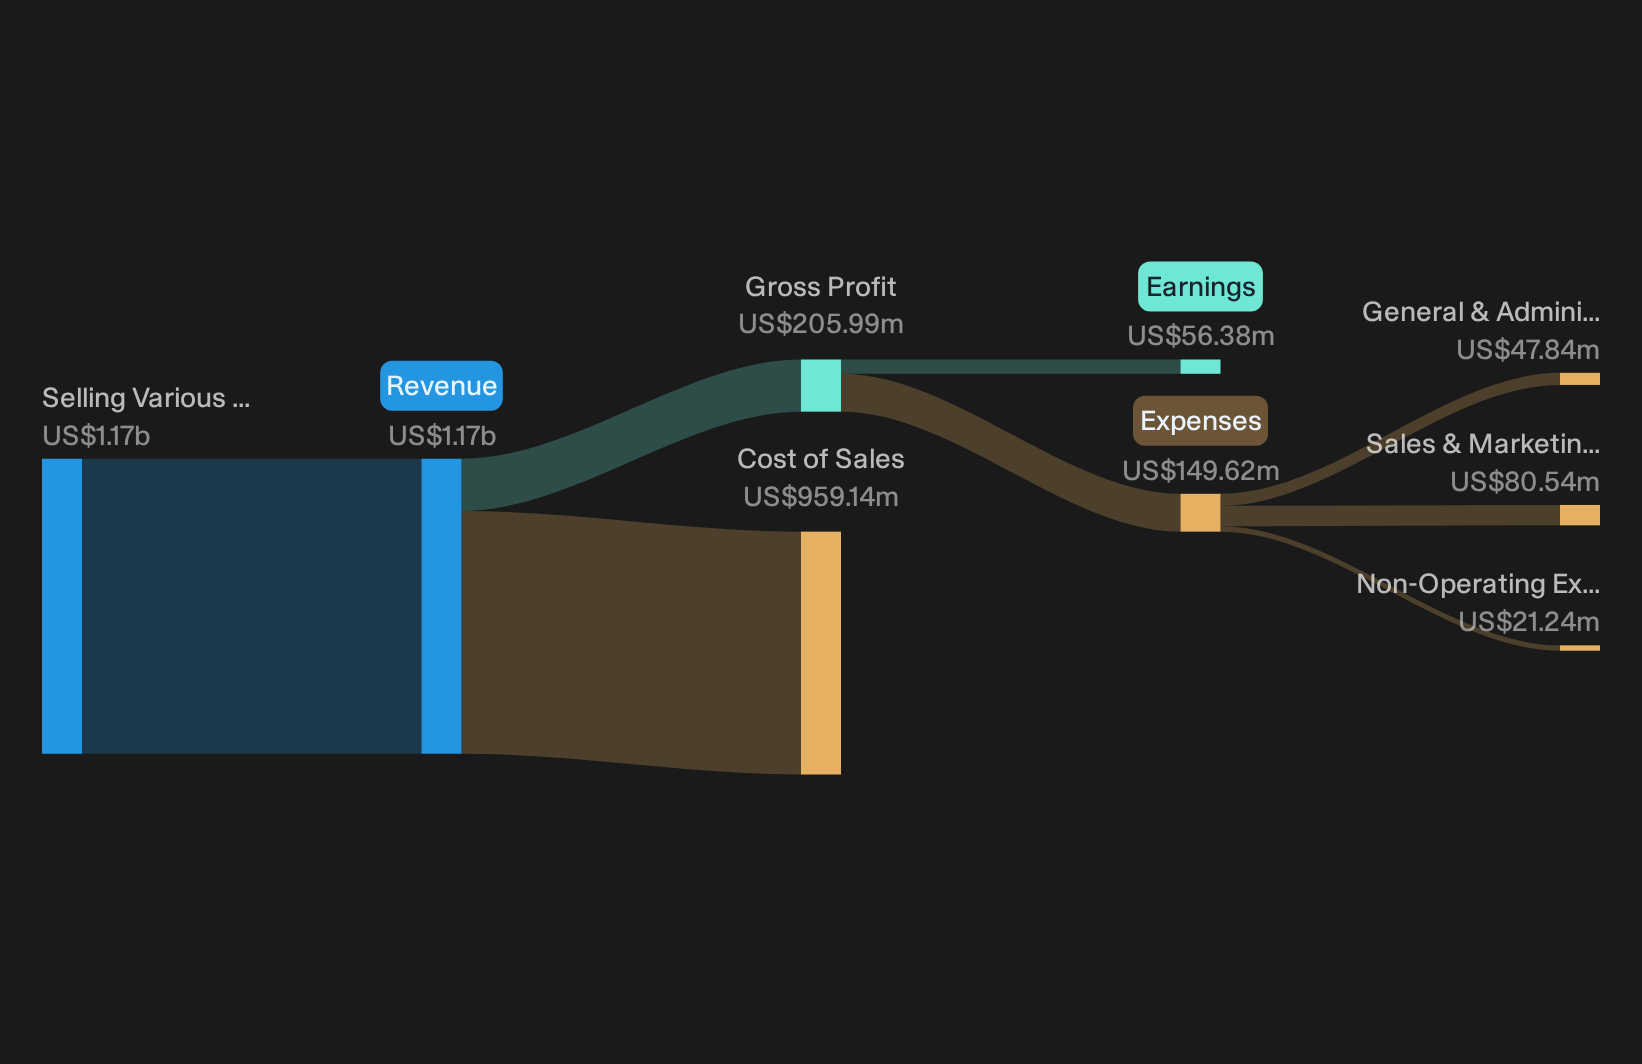
John B. Sanfilippo & Son is a US$658 million nut and snack producer, generating about US$1.2 billion in sales from various nut products and bars, mainly under Fisher, Orchard Valley Harvest and private label brands.
The bullish analyst Narrative on Simply Wall St argues that this defensive snack maker could quietly gain leverage in a higher rate world as recurring nut and bar purchases intersect with a business plan focused on cost discipline, private label growth and capital returns.
"The 20.6% year-over-year reduction in weighted average raw nut and dried fruit input cost per pound on hand, helped by lower peanut costs even as some tree nut costs rose, creates room for John B. Sanfilippo & Son to translate any future pricing actions into better gross margin capture if commodity costs and selling prices diverge further."
What happens to those margins if one less visible shift in how shoppers trade between branded and private label snacks breaks differently from the bullish script will matter a lot.
If that branded versus private label shift matters to your thesis, the full narrative for John B. Sanfilippo & Son shows how John B. Sanfilippo & Son's margin story could accelerate or stall.
Seeking Fresh Alternatives Right Now?
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Do not get caught chasing drops later, get in early.
- Spot under-the-radar quality before momentum traders arrive by scanning the 20 high quality undiscovered gems curated for strong fundamentals while it still matters.
- Target durable income while prices are still settling by reviewing the 6 dividend fortresses built for investors who want yield with resilience, not just high numbers.
- Position ahead of the next infrastructure wave by checking the 43 power grid technology and infrastructure stocks focused on businesses tied to grid upgrades while they are still dropping quietly into view.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com