


EN
Rogers (ROG) Stock May Already Reflect Its Earnings Power
Rogers has delivered a sharp share price swing over the past year, which puts fresh focus on whether the current tag lines up with what the business is actually earning. With the stock price now well above where it traded a year ago, the key issue for you is how firmly those earnings underpin that move.
- The stock has returned 63.9% over the past year, which puts real weight on the question of whether investors are paying a sensible price for Rogers' profit stream.
- The business still relies heavily on turning its specialty materials portfolio into consistent profits, so the sustainability of margins and cash generation can be pivotal for how supportive current earnings are of the valuation.
- The analysts covering Rogers have run their own numbers. See what analysts think Rogers's shares could be worth.
The issue now is whether the current share price of Rogers is adequately backed by its earnings power when judged against the Fair Ratio benchmark.
If you want to test the same earnings question that Rogers faces across a wider set of ideas, scan through 32 high quality undervalued stocks.
Does Rogers Look Pricey on Earnings?
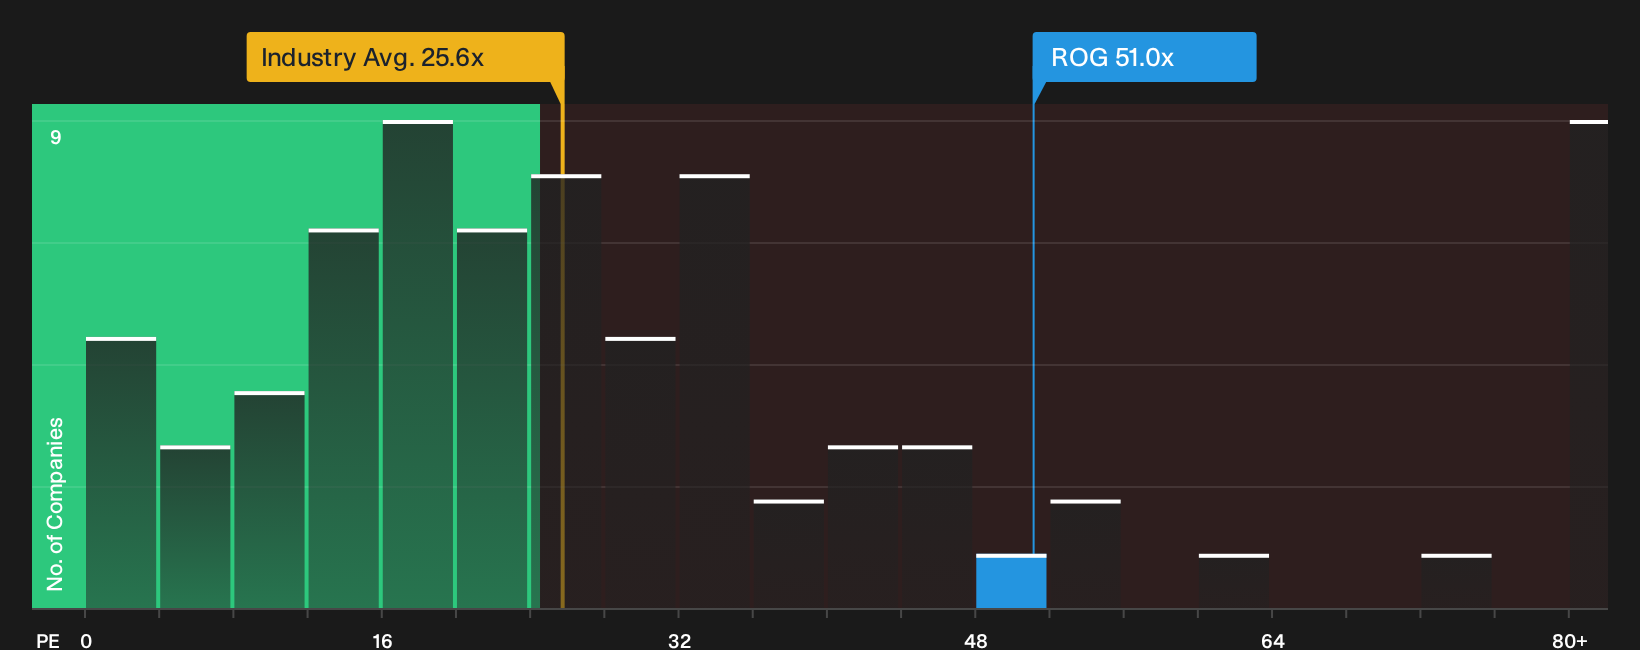
The P/E ratio fits Rogers well because earnings are a key lens for a materials manufacturer that still leans on converting its portfolio into steady profit. On that score, the stock trades on about 51.0x earnings, which is richer than the Electronic industry average of roughly 25.6x and also above the peer group near 37.8x. That kind of mark up implies investors are placing a high value on each dollar of current profit.
The Fair Ratio, which reflects what a more tailored P/E might look like once growth profile, profitability, size and risk are factored in, sits below where Rogers currently trades. The present multiple therefore runs above what that framework would suggest, so the shares screen as overvalued on earnings against this yardstick. For you as a shareholder or potential buyer, the key question is whether Rogers can keep justifying that richer tag with the cash flows and margins that matter most. Explore the numbers behind Rogers's P/E valuation.
The Rogers Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Rogers tackle the question left hanging by that high P/E multiple by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than it is today. Each narrative ties its number to a clear view on how Rogers' growth, margins and risks might evolve, which gives you something specific to revisit as fresh information comes through.
One of the top narratives on Rogers: 38% undervalued
This is the bullish analyst Narrative on Simply Wall St, built from the most optimistic analyst price target and supporting forecasts, not one person's view.
"The main thing that has to go right is that customer sampling in AI server connectivity and cooling, EV battery systems and EMI shielding converts into sustained design wins and revenue ramps..."
Discover why this Narrative puts Rogers at 38% undervalued.
One more Rogers factor to check before making your move
Price and earnings only tell part of the story for Rogers, because the people setting priorities and the way they are rewarded can strongly influence how that story plays out for you. See who runs Rogers and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com