


EN
Are Third Quarter Earnings Altering The Investment Case For LP Louisiana Pacific Stock
- Louisiana-Pacific reported third quarter 2026 sales of US$691 million and net income of US$23 million, with basic EPS from continuing operations of US$0.33.
- The quarterly earnings contrast with weaker nine month results, which showed lower sales and net income than the prior year, giving investors fresh data on how the operating mix is evolving.
- Next, the focus turns to how Louisiana-Pacific's latest quarterly earnings profile, especially the higher Q3 profit, fits into the existing investment narrative.
Scan how Louisiana-Pacific pairs earnings with a consistent cash payout, then widen your radar to a curated set of income ideas through 6 dividend fortresses.
Louisiana-Pacific Investment Narrative Recap
Owning Louisiana-Pacific means buying into a story where higher margin siding keeps taking a larger share of the business, while OSB volatility and housing cycles remain the key swing factors. The analyst consensus narrative on Simply Wall St leans on that siding tilt and on earnings growth forecasts, while recent Q3 profit and EPS show the earnings base still moving around.
Right now, the most important near term catalyst is execution on SmartSide and ExpertFinish capacity and demand, because that is where analysts see better margins. The biggest risk is that weak housing activity or low OSB pricing keep overall profitability thin, so this quarter alone does not materially change the risk balance.
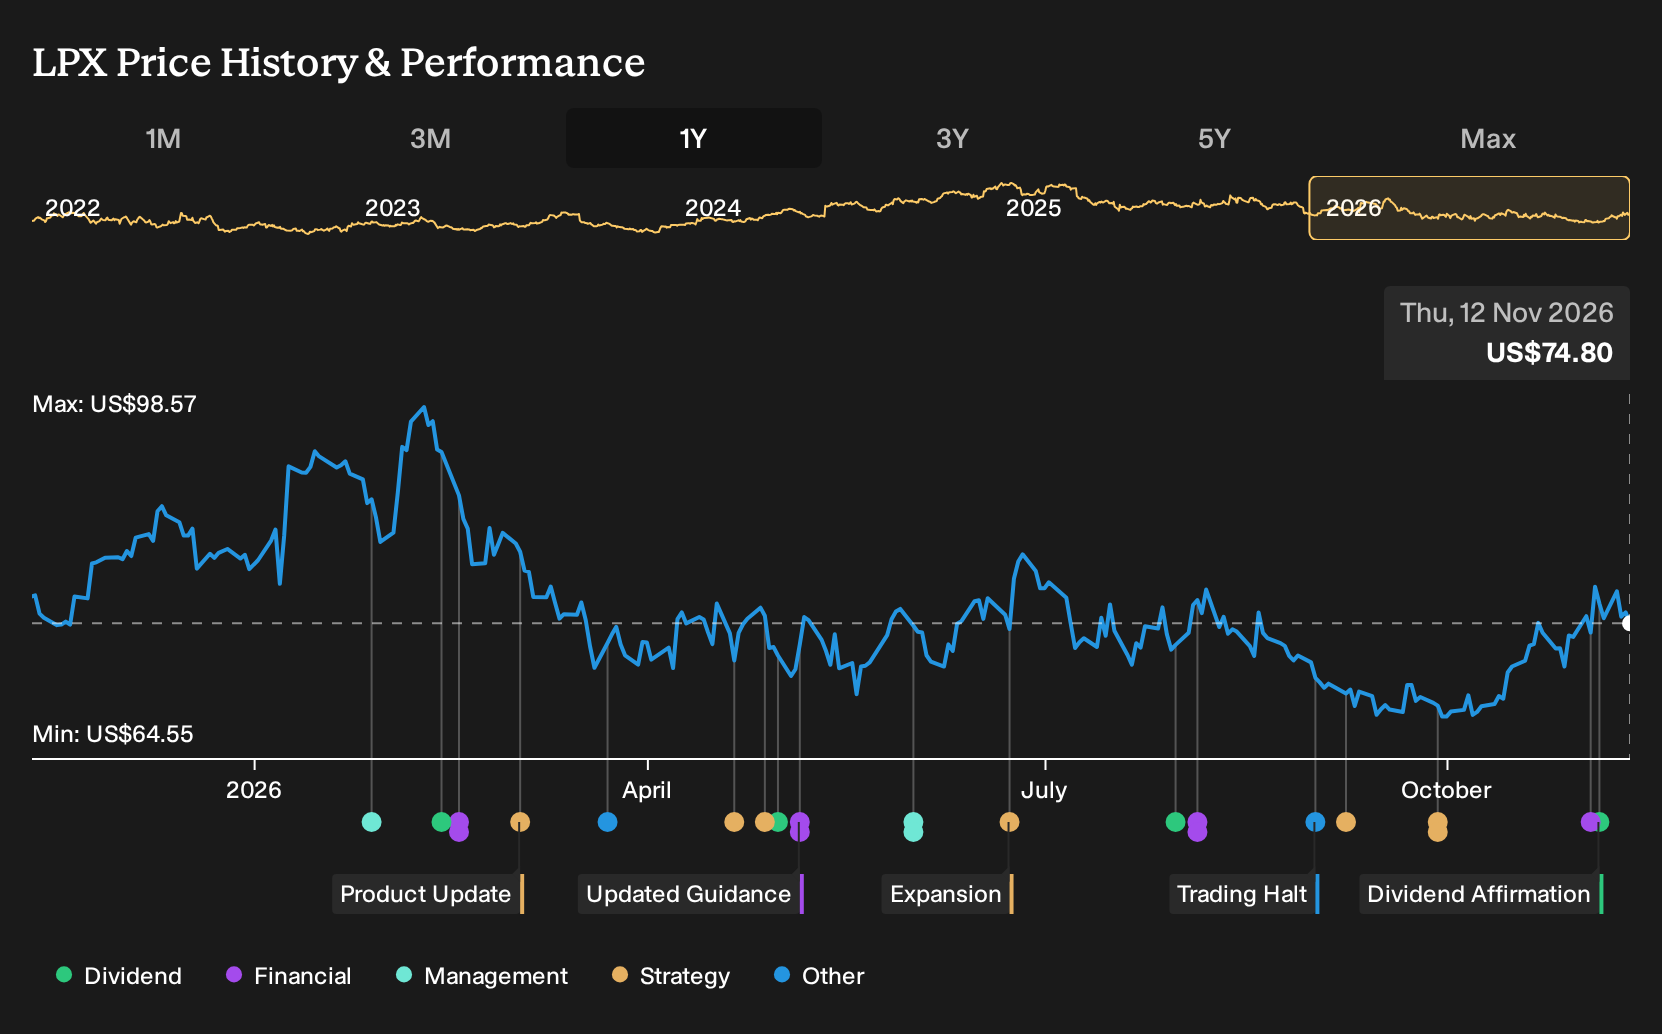
The fresh dividend affirmation of US$0.30 per share is the announcement that ties most directly to these results. It signals that Louisiana-Pacific is maintaining its cash return framework at the same time as nine month earnings remain below the prior year and profit margins have compressed from 7.7% to 2.7%.
For you as a shareholder, the key question is whether that payout is well supported by future siding driven cash flows, given analysts flag the 1.6% yield as not well covered by current earnings or free cash flow. That tension between capital returns and reinvestment needs sits alongside OSB pricing, housing demand and execution on siding expansion as the main catalysts to track.
What The Current Analyst Assumptions Mean For Louisiana-Pacific
Louisiana-Pacific's narrative projects US$3.0b revenue and US$422.6 million earnings by 2029. That profile rests on analysts using 6.9% yearly revenue growth and an earnings increase of about US$368.6 million from US$54.0 million today.
Uncover why Louisiana-Pacific's fair value signals a 17% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view puts crude oil at the center of the Louisiana-Pacific debate. The most pessimistic analysts worry that higher oil linked input and freight costs could squeeze siding cash generation, even with the dividend held at US$0.30. They were only modeling about US$2.9b revenue and US$366.6 million earnings by 2029 before this update, which shows how sharply opinions can differ. Use that spread as a prompt to explore several forecast sets rather than relying solely on the consensus.
Explore 2 other Louisiana-Pacific fair value estimates, including one that suggests as much as 100% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Louisiana-Pacific research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Louisiana-Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Louisiana-Pacific's overall financial health at a glance.
Looking For More Investment Ideas Beyond Louisiana-Pacific?
If this Louisiana-Pacific update has sharpened your view on siding, OSB and dividends, use that same playbook to look for other opportunities where the numbers and story align clearly.
- If you want potential mispricing backed by solid fundamentals, start with a curated set of companies that screen as 32 high quality undervalued stocks.
- If capital preservation matters just as much as upside, widen your watchlist to businesses that appear in our 29 resilient stocks with low risk scores.
- If you are looking for underfollowed stories with strong balance sheets and earnings quality, review the 20 high quality undiscovered gems and see which ones belong on your shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com