


EN
Will Bigger Buyback Change COMSYS Holdings Stock Narrative
- COMSYS Holdings reported half year results to 30 September 2026 with sales of ¥294,767 million and net income of ¥17,347 million, alongside basic earnings per share from continuing operations of ¥150.72.
- The board also raised the existing equity buyback authorization to a total of 3,250,000 shares for up to ¥13,000 million. This move indicates how management currently prioritizes capital returns versus other uses of cash.
- The focus now turns to how this larger COMSYS Holdings repurchase plan could influence the company’s investment narrative for long term holders.
Compare COMSYS Holdings’ buyback driven story with other businesses returning cash to shareholders by scanning our curated list of 27 dividend fortresses as potential income ideas alongside this stock.
What Is COMSYS Holdings' Investment Narrative?
Being a shareholder in COMSYS Holdings really comes down to believing in a steady, infrastructure heavy contractor that leans on telecom, power and public works demand rather than rapid expansion. The latest half year figures, with ¥294,767 million in sales and ¥17,347 million in net income, support a story of incremental progress instead of big swings. The increased buyback, now up to 3,250,000 shares, points to management treating cash returns as a key near term priority instead of aggressive reinvestment.
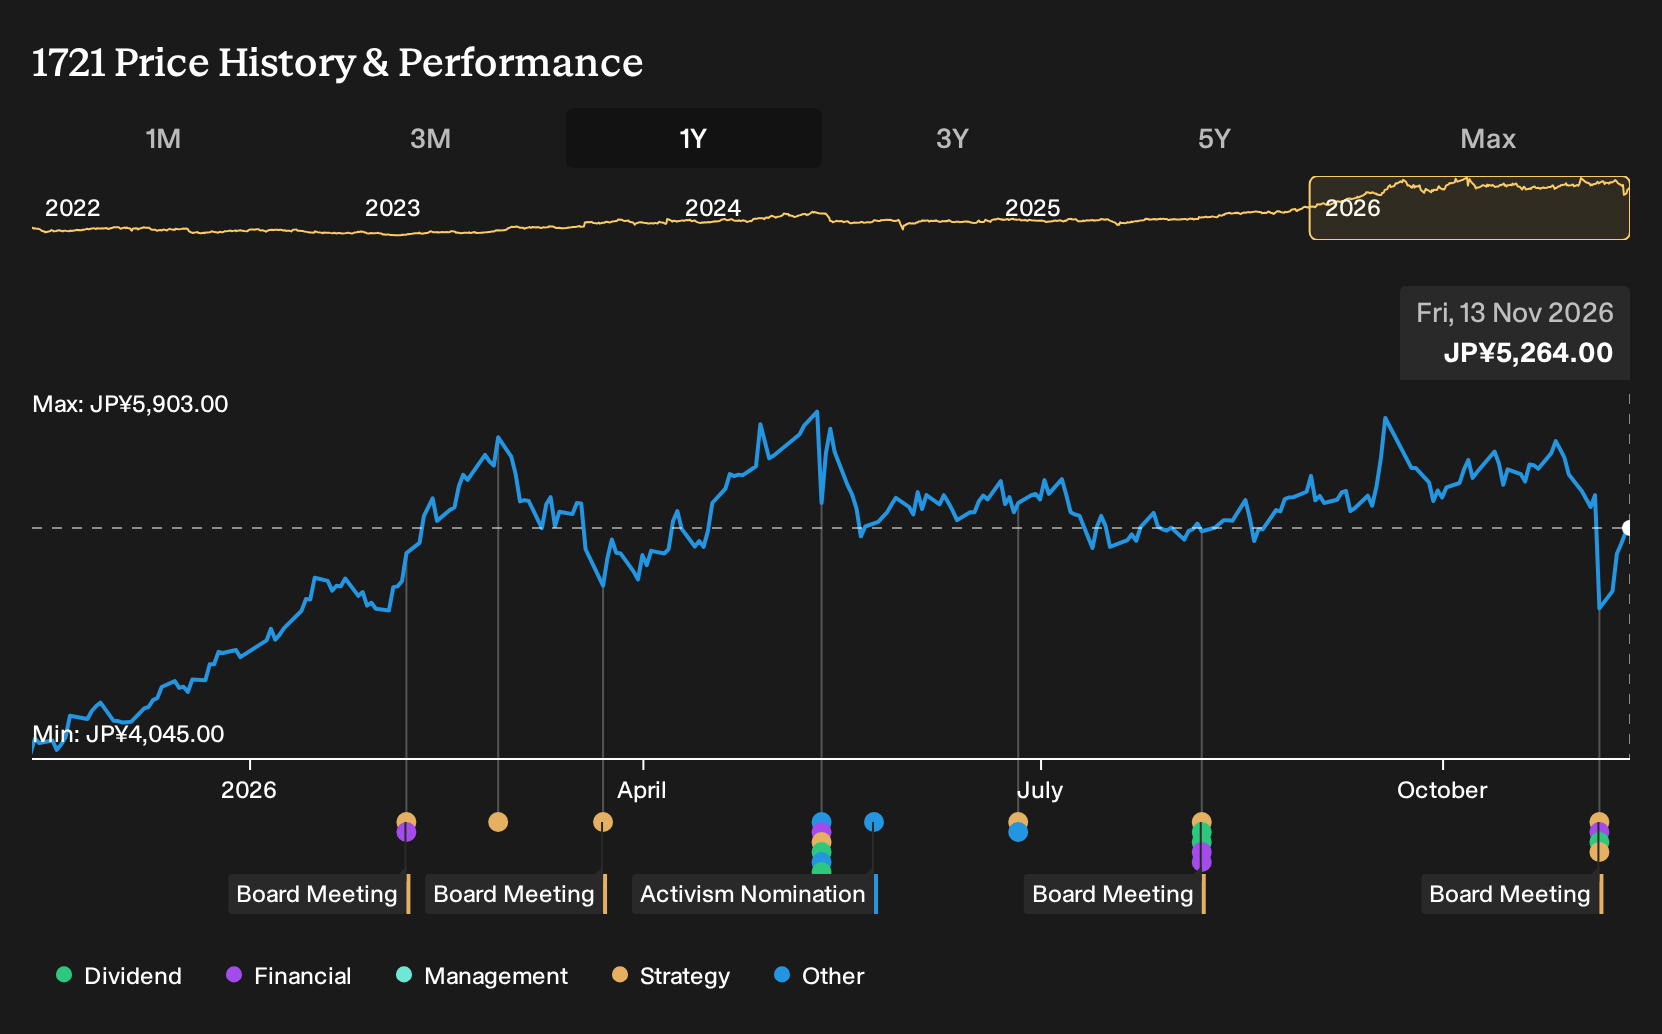
In the short term, the larger repurchase plan can tighten the float and partly offset weaker price action, with the share price down 7.8% over the past month while still ahead 12.8% year to date. What really matters is whether COMSYS Holdings can keep executing profitably on capital intensive projects, as forecasts indicate more modest earnings and revenue growth than the wider JP market, while the company carries a P/E of 14.6x against lower industry and peer averages.
Yet there is a pressure point in this story that only really shows up once you look closely at how future growth, returns on equity and capital allocation intersect...
There's only one way to know the right time to buy, sell or hold COMSYS Holdings. Head to Simply Wall St's company report for the latest analysis of COMSYS Holdings's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your COMSYS Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for COMSYS Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COMSYS Holdings' overall financial health at a glance.
Looking for more COMSYS Holdings style investment ideas?
If the COMSYS Holdings story has you thinking about where else disciplined capital returns and solid fundamentals might show up, you can widen the lens using the Simply Wall St Screener.
- For readers who care most about valuation and quality together, scan a curated mix of companies trading on what may be attractive terms through the 18 high quality undervalued stocks.
- If your focus is on financial resilience first, sort for businesses with robust balance sheets and cleaner fundamentals via the list of solid balance sheet and fundamentals (25 results).
- To keep an eye on potential future leaders before they hit the mainstream, track a hand picked set of quieter opportunities using the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com