


EN
Intuitive Machines (LUNR) Stock Could Be Overvalued As NASA Moon Base Win Lands
Intuitive Machines has delivered very large gains over the past three years, which puts fresh attention on whether the current share price can be explained by its sales base. With the stock now at US$13.03, the key issue for you is how much of that move is backed by revenue versus excitement around recent contract wins.
- The share price is up about 3.4x over 3 years, so anyone looking at Intuitive Machines today is effectively being asked to pay a very different sales multiple than early holders did.
- NASA contracts for lunar delivery and Earth observation work signal a growing pipeline, which can support expectations for higher future sales and potentially reshape what feels like a reasonable revenue multiple.
- There is a second opinion on Intuitive Machines worth weighing. See what analysts think Intuitive Machines's shares could be worth.
For investors, the debate is whether Intuitive Machines' current market value is properly grounded in its sales, given both the sharp multi-year share move and its expanding space contract backlog.
If you like what Intuitive Machines is doing but want a broader starting point for research, apply the same sales-focused lens to our screener containing 20 high quality undiscovered gems.
Is Intuitive Machines Getting Expensive on Sales?
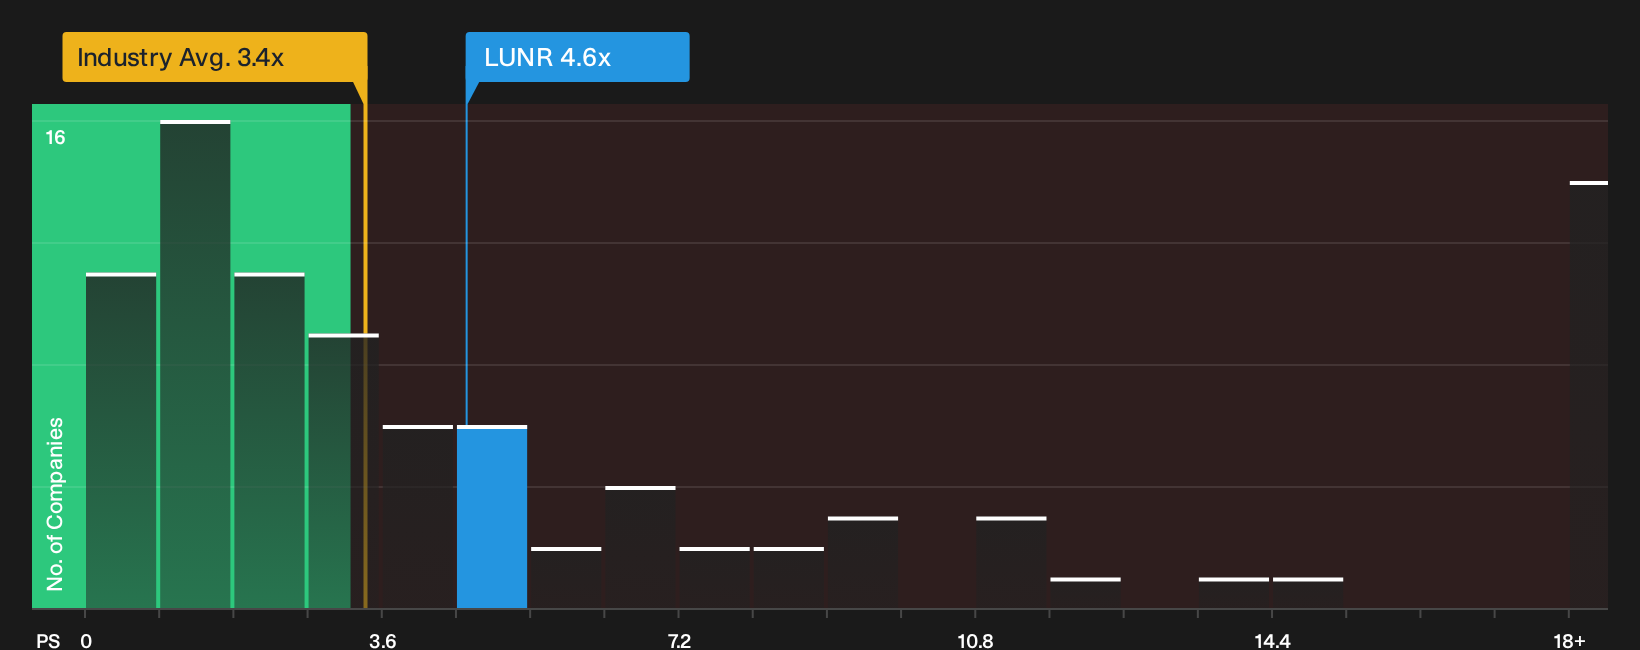
P/S is usually a cleaner lens for Intuitive Machines because the business is still working through losses and cash burn. On this metric, the stock trades on a P/S of about 4.6x, compared with an Aerospace & Defense sector average of roughly 3.4x and a peer group around 3.2x. That points to investors paying a clear premium for each dollar of current revenue.
After the recent NASA contract wins and record quarterly revenue, that richer tag has not closed the gap to what the in house model views as a fairer P/S level. The tailored benchmark, which blends Intuitive Machines' growth profile, margins, risk and size, sits well below today’s multiple. The model heavily penalises the current loss making profile and execution risk. Because of that, the signal is less an exact target and more a warning that the shares screen as overvalued on sales against this framework. Explore the numbers behind Intuitive Machines's P/S valuation.
The Intuitive Machines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S discussion leaves off by explaining what would need to happen to Intuitive Machines' growth, profitability and earnings for the stock to be worth meaningfully more or less than today’s valuation. Each scenario connects a fair value estimate to a particular mix of potential catalysts and pressure points so you can track over time which storyline about Intuitive Machines' business actually matches reality.
Bulls in Intuitive Machines focus on the long runway from lunar services, while bears worry the backlog and guidance do not fully translate into firm, profitable work.
Bull case: 43% undervalued
According to sorkdhkddlek, an investor in the Simply Wall St Community, the opportunity starts with how Intuitive Machines has repositioned its business model.
"Intuitive Machines (LUNR) has successfully shifted from a high-risk startup to a Lunar Infrastructure Prime, backed by a $943M backlog and a strategic pivot toward high-margin data services via the Lanteris acquisition..."
Discover why this Narrative puts Intuitive Machines at 43% undervalued.
Bear case: 31% overvalued
DanielOliveira, a Simply Wall St Community investor who wrote the bearish view, zeroes in on how much of Intuitive Machines' pipeline is already locked in.
"By the 10-Q's own schedule, firm fixed-price orders cover only $244 million to $285 million of that..."
Explore why this Narrative puts Intuitive Machines at 31% overvalued.
For Intuitive Machines, the share price is only one piece of the decision
Valuation only tells part of the Intuitive Machines story, because Simply Wall St’s broader checks have also flagged specific concerns that investors may want to weigh before committing fresh capital. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com