


EN
The Bet Twist Bioscience Holders Made Before A 282% Jump
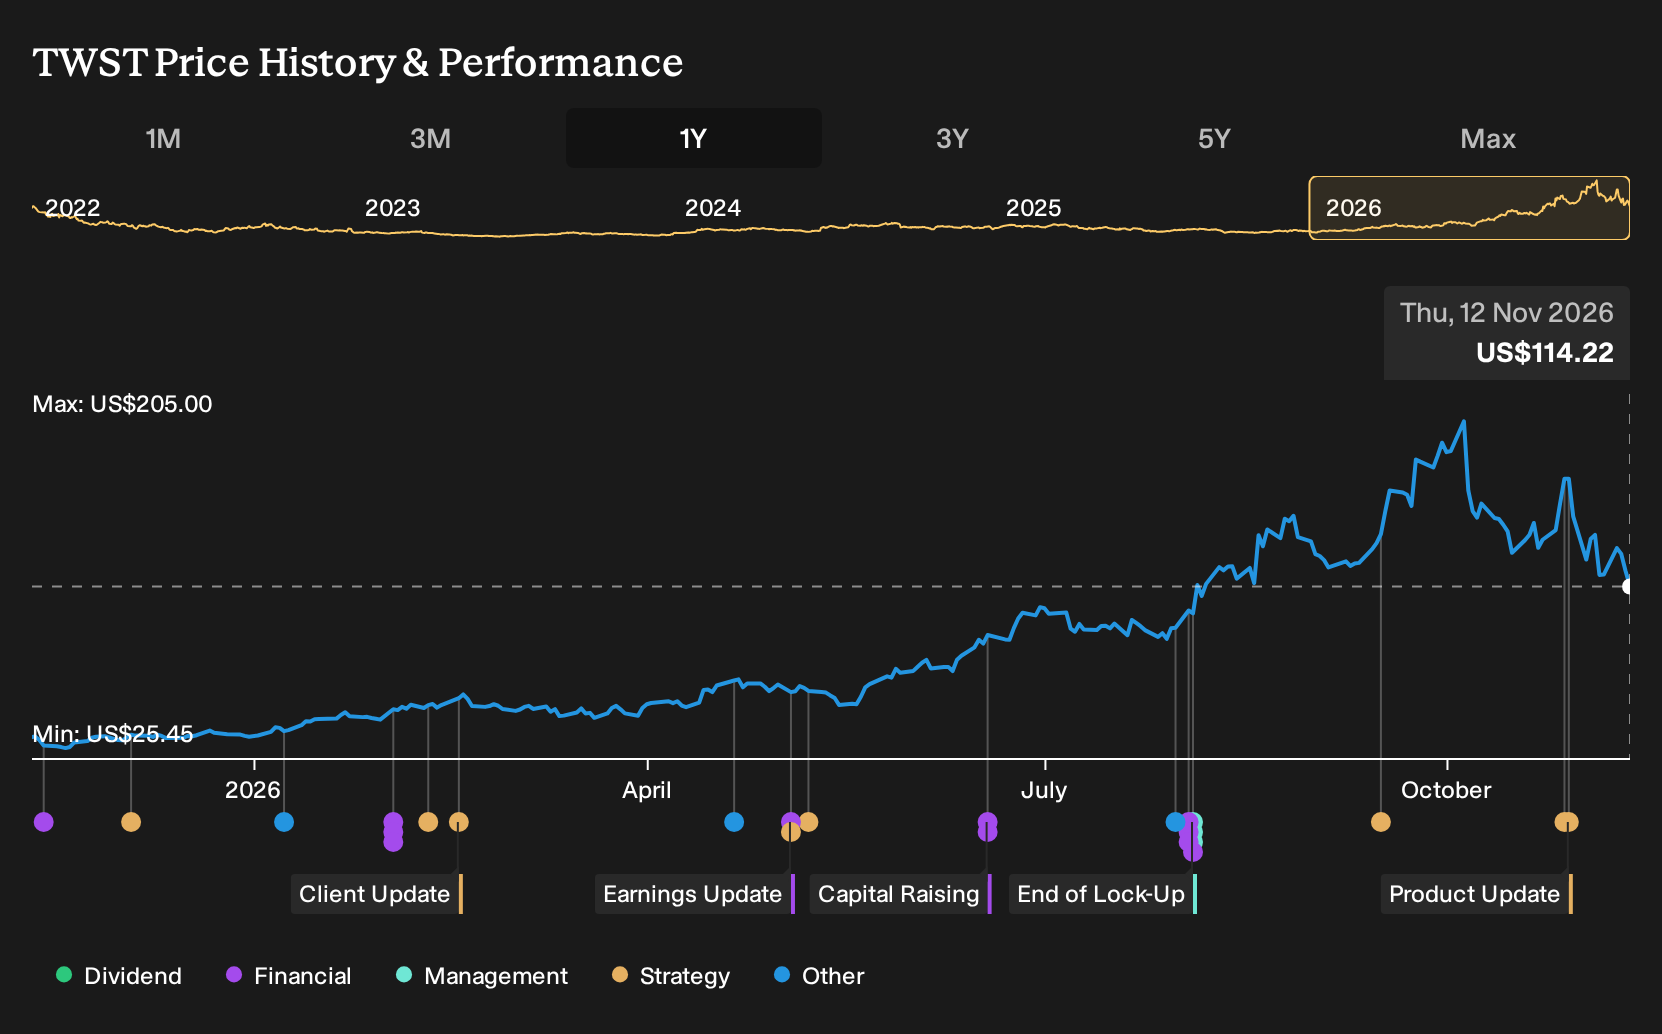
If you had looked at Twist Bioscience in late 2025, the headlines were about ongoing losses, customer concentration risk, and concerns that DNA synthesis was becoming a commodity. For Twist Bioscience shareholders, the return over the past year was 282.0%, including dividends. If you had bought with those worries front and center, how should you now think about a business that still reports sizable losses yet produced such an extreme payoff?
This theme extends beyond Twist Bioscience. See which of 35 healthcare AI stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Twist Bioscience
The shares cost US$31.87 at the start of the period, and Twist Bioscience sat between two very different stories about what might happen next.
The bullish narrative saw a broadening customer base and new SynBio lines feeding into assumed revenue growth of 16.7%. That view pointed to a Fair Value of US$42.14, a price that reflected what those assumptions implied rather than an observed trading level.
The bearish script focused on DNA synthesis commoditization and customer concentration risk, with assumed revenue growth of 15.4%. On that side, the implied Fair Value was US$25, tied to concerns that rising competition and regulation could keep margins under pressure.
What The Twist Bioscience Evidence Actually Showed
Twist Bioscience reported record Q2 2026 revenue of US$110.7 million and Q3 revenue of US$118.4 million, with both quarters still producing sizeable net losses of US$44 million and US$35.1 million. That outcome backed the bullish focus on demand and gross margin above 52%, while leaving the profitability and cash self-sufficiency parts of the optimistic case unproven.
The hinge assumption here was not abstract growth but whether rising sales would translate into cleaner economics. When you assess another high-growth lab tools stock, track the mix of revenue, gross margin and adjusted EBITDA in each report rather than just the top line.
What Twist Bioscience’s Run Has Priced In
Twist Bioscience now trades at US$114 after a very large 282.0% gain over the past year, and the bearish analyst Narrative on Simply Wall St places its Fair Value below that level. That view leans on the idea that strong gross margins and AI related demand still have to work much harder on the bottom line.
A buyer at today’s price is effectively assuming that rapid AI enabled orders, high capacity and NGS demand will keep converting into rising cash earnings. The question is how ongoing GAAP net loss risk in this Narrative affects that path toward sustained profitability.
"The main requirement for improvement is that Twist Bioscience converts its higher gross margins, expanding DNA synthesis capacity, and growing therapeutics and NGS revenues into sustained adjusted EBITDA breakeven and progress toward profitability."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 34% below our estimate - uses shared AI and cloud infrastructure to connect subscription and usage-based services.
- Company 2 - 24% below our estimate - expands high value photonics packaging capacity to address AI data center and optics demand.
- Company 3 - 38% below our estimate - pushes 1P retail, AI automation and trade in programs to deepen pre owned device commerce.
Those are three of them. See the full list of 32 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com