


EN
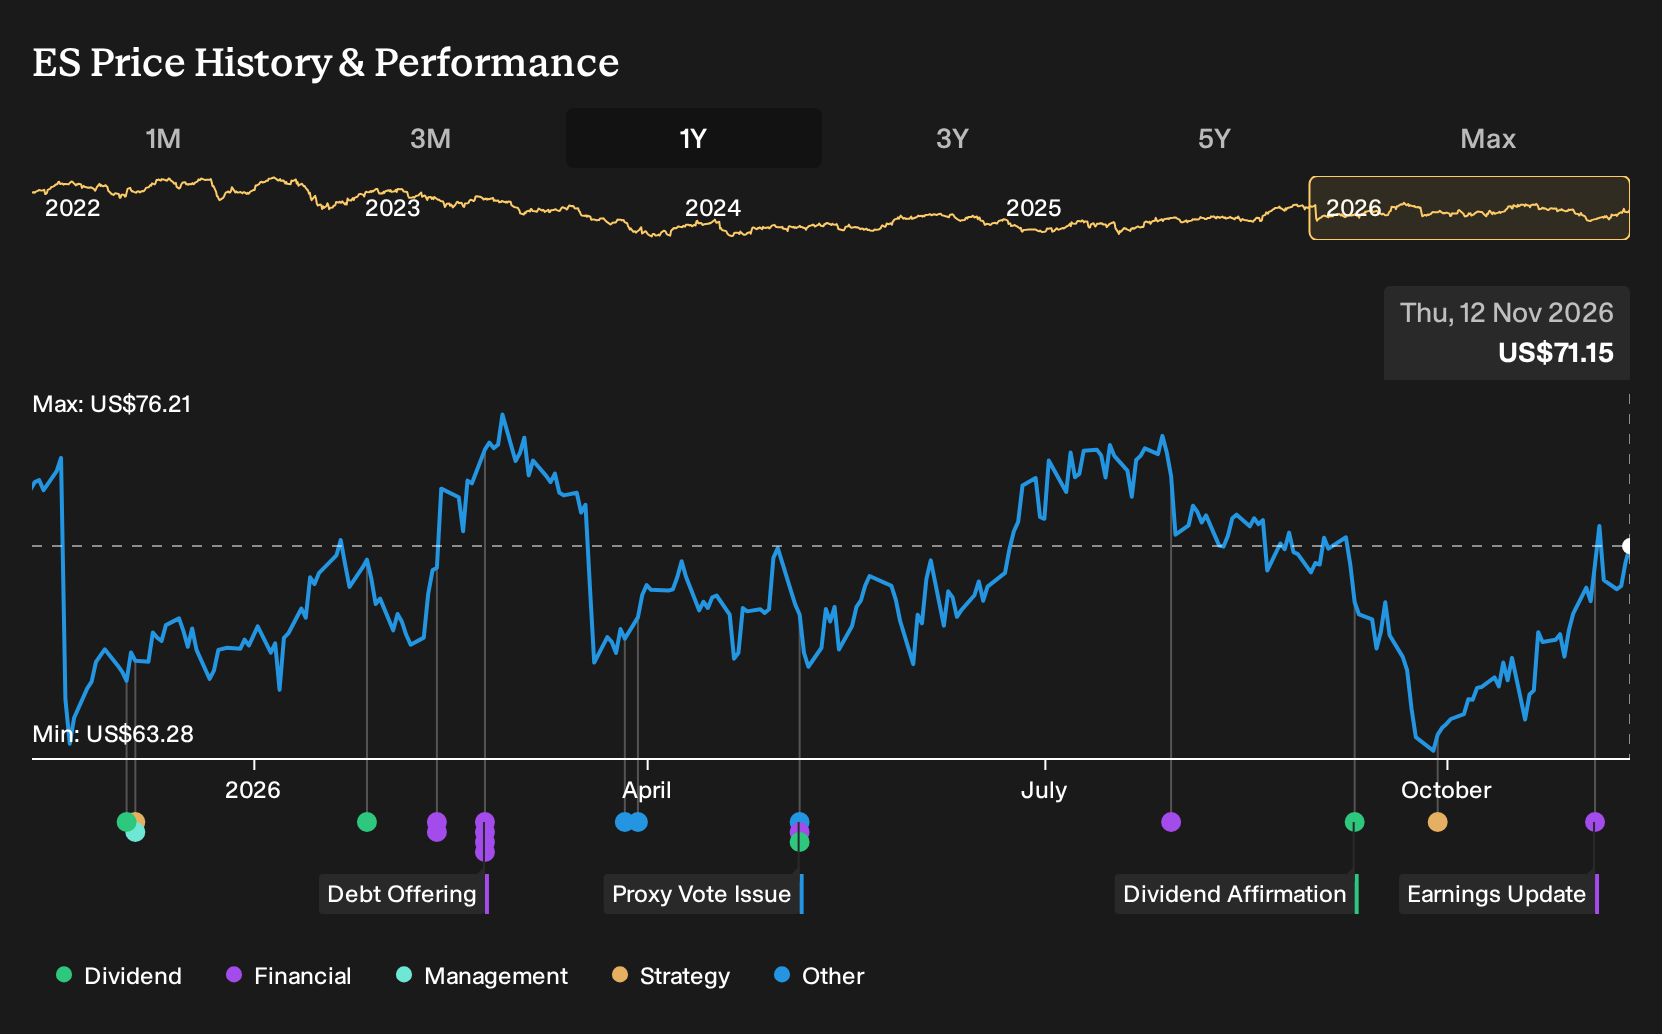
How Softer Earnings At Eversource Energy (ES) Has Changed Its Investment Story
- Eversource Energy reported third quarter 2026 sales of US$2,978.89m and net income of US$346.01m, with basic and diluted EPS from continuing operations of US$0.92, alongside nine month sales of US$10,386.44m and net income of US$1,006.54m.
- The nine month gap between higher sales and lower earnings suggests rising costs or mix pressures within Eversource Energy's regulated utility operations that investors may wish to examine in more detail.
- This raises questions about how Eversource Energy's investment narrative aligns with lower year on year net income and earnings per share.
Eversource Energy Investment Narrative Recap
Eversource Energy still appeals to investors who believe in long term, regulated grid and gas infrastructure backed by a multi year US$26.5b capital plan. To stay comfortable as a shareholder, you need confidence that regulators will support timely recovery of those investments and that cost discipline can offset pressures on allowed returns.
The latest quarter shows sales and earnings that are a bit softer than last year, which keeps the short term focus on regulatory decisions and project execution. The biggest near term risk remains tighter rate outcomes or cost overruns, especially on large projects, rather than anything in this earnings print alone.
The analyst consensus Narrative on Simply Wall St points to grid modernization and electrification as the key operational drivers for Eversource Energy over the next few years. That view leans heavily on the planned US$26.5b of regulated utility spending and nearly US$1b of advanced metering infrastructure in Connecticut as long term earnings drivers.
Against that backdrop, the recent earnings update matters mainly because it arrives while regulators scrutinize bills and returns. Any further pressure on allowed transmission return on equity, cost recovery for storms, or offshore wind related charges would feed directly into the main risk flagged in that Narrative, which is earnings sitting below what the current story assumes.
Eversource Energy's current earnings sit at US$1.4b, with analysts projecting revenue growth of 3.3% a year and targeting US$15.4b of revenue and US$2.1b of earnings by 2029. That outlook implies an earnings increase of about US$700m from today to the 2029 consensus forecast.
Uncover why Eversource Energy's fair value indicates it is roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts framed the TIDE transmission project as the key upside for Eversource Energy, expecting revenue to reach about US$17.3b and earnings of roughly US$2.2b by 2029. Those projections came before this softer quarter, so if you lean bullish, you may want to test whether that grid buildout story still feels intact.
Explore 2 other Eversource Energy fair value estimates, including one that suggests it could be worth as much as $72.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Eversource Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eversource Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eversource Energy's overall financial health at a glance.
Looking for more investment ideas beyond Eversource Energy?
If the Eversource Energy story has sharpened your thinking, cast the net wider and stress test your thesis against other businesses using the Simply Wall St Screener.
- For investors who want potential upside without ignoring financial strength, scan a curated set of 20 high quality undiscovered gems that pair solid fundamentals with relatively low attention.
- If capital preservation sits high on your list, focus on stability first by reviewing 29 resilient stocks with low risk scores that score well on resilience and balance sheet quality.
- Income focused readers can zero in on consistency by checking out 6 dividend fortresses that combine higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com