


EN
How New Water Filtration And AI R&D Tools Will Impact DuPont (DD) Investors
- DuPont de Nemours recently launched four high flow Electrodeionization modules for industrial and microelectronics water treatment and announced a collaboration with Microsoft and NobleAI to apply advanced AI tools across its R&D efforts.
- The combination of expanded EDI capacity and AI supported experimentation strengthens the link between DuPont de Nemours' water franchise, cost discipline, and faster product development cycles in core industrial and semiconductor end markets.
- Next, the focus will be on how DuPont de Nemours' AI powered R&D initiatives could influence the existing investment narrative around cost productivity.
DuPont de Nemours Investment Narrative Recap
To own DuPont de Nemours, you need to believe the refocused portfolio in Healthcare & Water Technologies and Diversified Industrials can convert steady demand into better margins and cash generation. The analyst consensus Narrative on Simply Wall St leans on ongoing productivity programs, AI enabled R&D and disciplined capital returns as the core drivers. The near term operational swing factor is execution on cost and quality targets while managing input cost inflation.
The biggest risk still sits with environmental and legal PFAS exposure and any extra cash calls that could chip away at free cash flow. Current water demand is solid but exposed to timing issues in the Middle East, so extended project delays or pricing pushback would work against the cost productivity story. Recent AI and water product announcements support the thesis but do not remove these constraints.
The collaboration with Microsoft and NobleAI appears closely tied to the existing catalyst around cost and productivity programs. Management already targets 3% net productivity of COGS each year, and AI supported modeling and experimentation may tighten that loop inside labs and process engineering. Faster evaluation of materials and process conditions could help DuPont de Nemours sustain margin work without relying solely on pricing.
There is still execution risk. AI tools need to integrate into real workflows, not stay as pilots, and any benefits have to show up despite oil and gas related cost pressure and PFAS related cash requirements. For you as a shareholder, the practical question is whether this R&D collaboration, together with the new EDI modules, keeps the Healthcare & Water focus translating into tangible improvements in earnings quality and resilience over the next few years.
DuPont de Nemours' current analyst narrative points to forecast revenue of US$8.1b and earnings of US$985.6m by 2029, based on an assumed 4.6% yearly revenue growth rate and a move in profit margins from 5.5% today to 12.2%. That earnings path implies an increase of about US$597.6m from current earnings of US$388.0m.
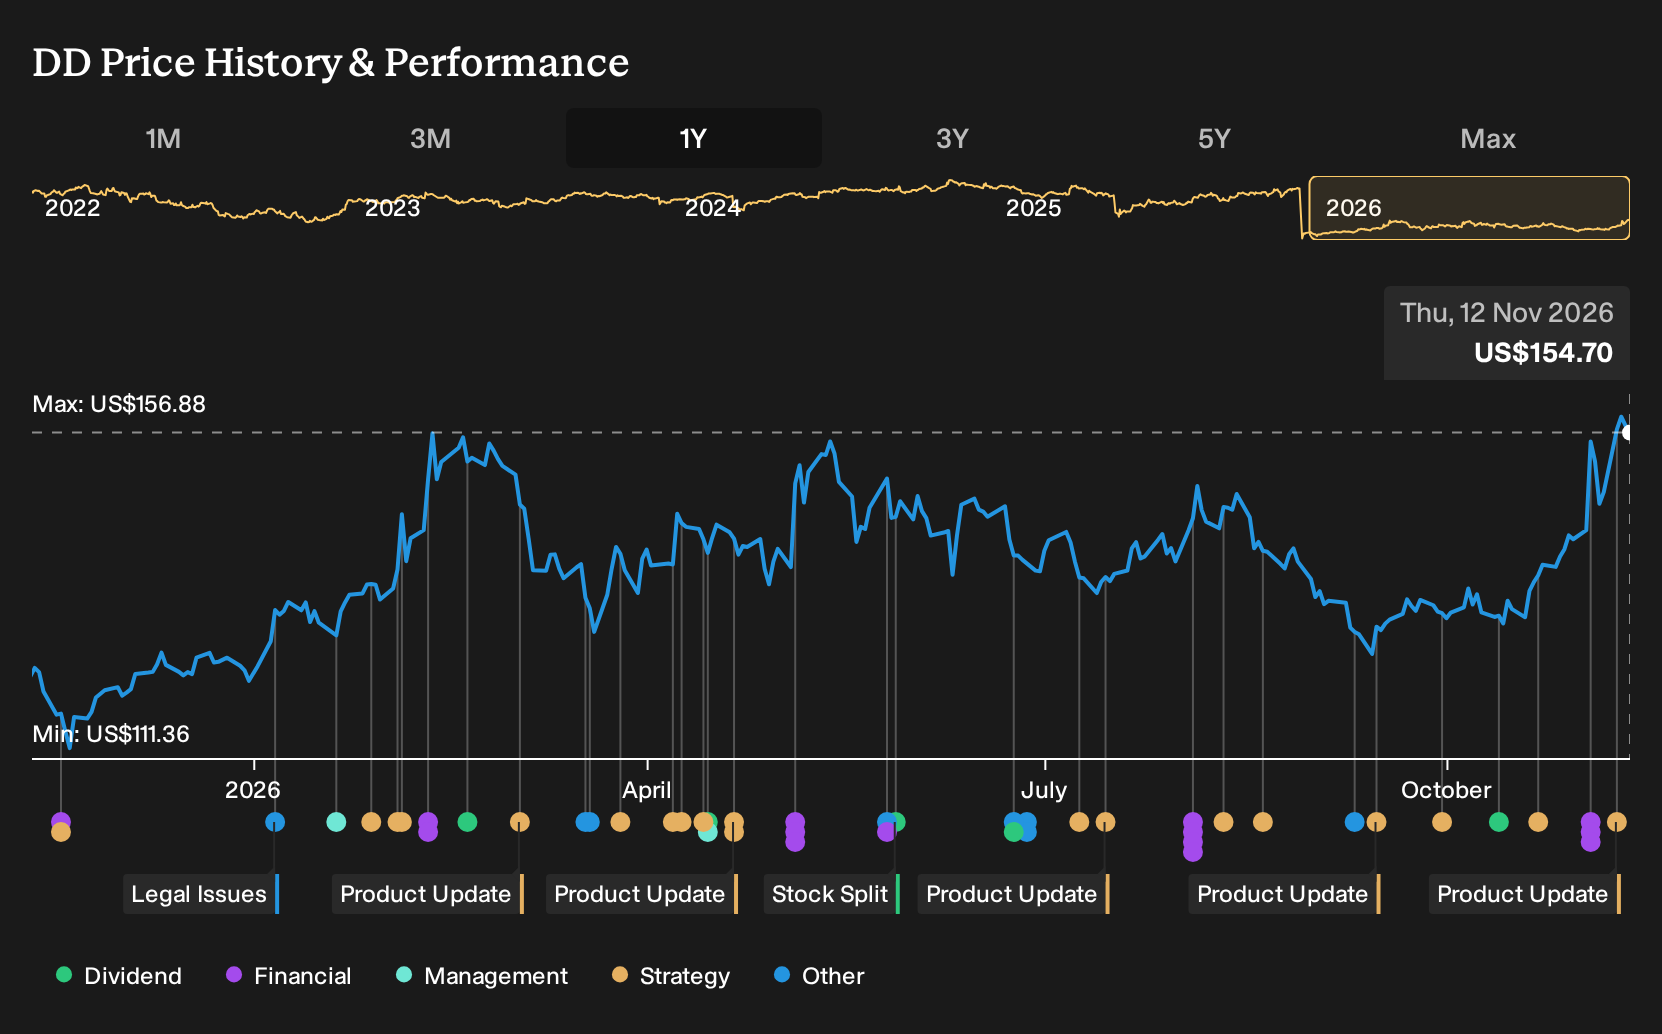
Uncover why DuPont de Nemours' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on DuPont de Nemours leans heavily on slower Water growth as the key concern. The most cautious analysts were only modeling about 3.6% annual revenue growth and roughly US$964.0m of earnings by 2029 before this AI and EDI news. That gap shows how widely opinions can differ, so it may be useful to explore several narratives before deciding.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests it could be worth just $152.54.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking for more investment ideas beyond DuPont de Nemours?
If DuPont de Nemours has sharpened your focus on quality, you can use that same filter across the market with the Simply Wall St Screener to build a wider watchlist that fits your risk and income goals.
- If you want potential mispricing combined with solid business quality, scan a curated set of 32 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and steadier profiles matter more to you, filter for 29 resilient stocks with low risk scores that may align better with a cautious approach.
- If you prefer strong balance sheets as your starting point, focus on a list of solid balance sheet and fundamentals (23 results) to anchor your next round of ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com