


EN
SK Hynix (KOSE:A000660) Draws Focus As Senators Push Curbs On Chinese Memory Rival
- SK hynix (KOSE:A000660) is in focus as U.S. senators push for tighter curbs on Chinese memory producer CXMT.
- Lawmakers are urging restrictions on CXMT’s access to U.S. chip tools and software used for advanced DRAM and high bandwidth memory.
- The move targets CXMT’s role in global AI and data center supply chains where DRAM and HBM chips are critical components.
- The Senate drive to limit CXMT’s access to U.S. technology could reshape SK hynix’s DRAM and HBM competitive position, but the SK hynix story runs wider than this CXMT export control push. We have also spotted 2 warning signs (1 major) worth knowing about at SK hynix.
To understand how this kind of policy pressure intersects with broader AI build outs, it is worth scanning the wider infrastructure trend too through 53 AI infrastructure stocks.
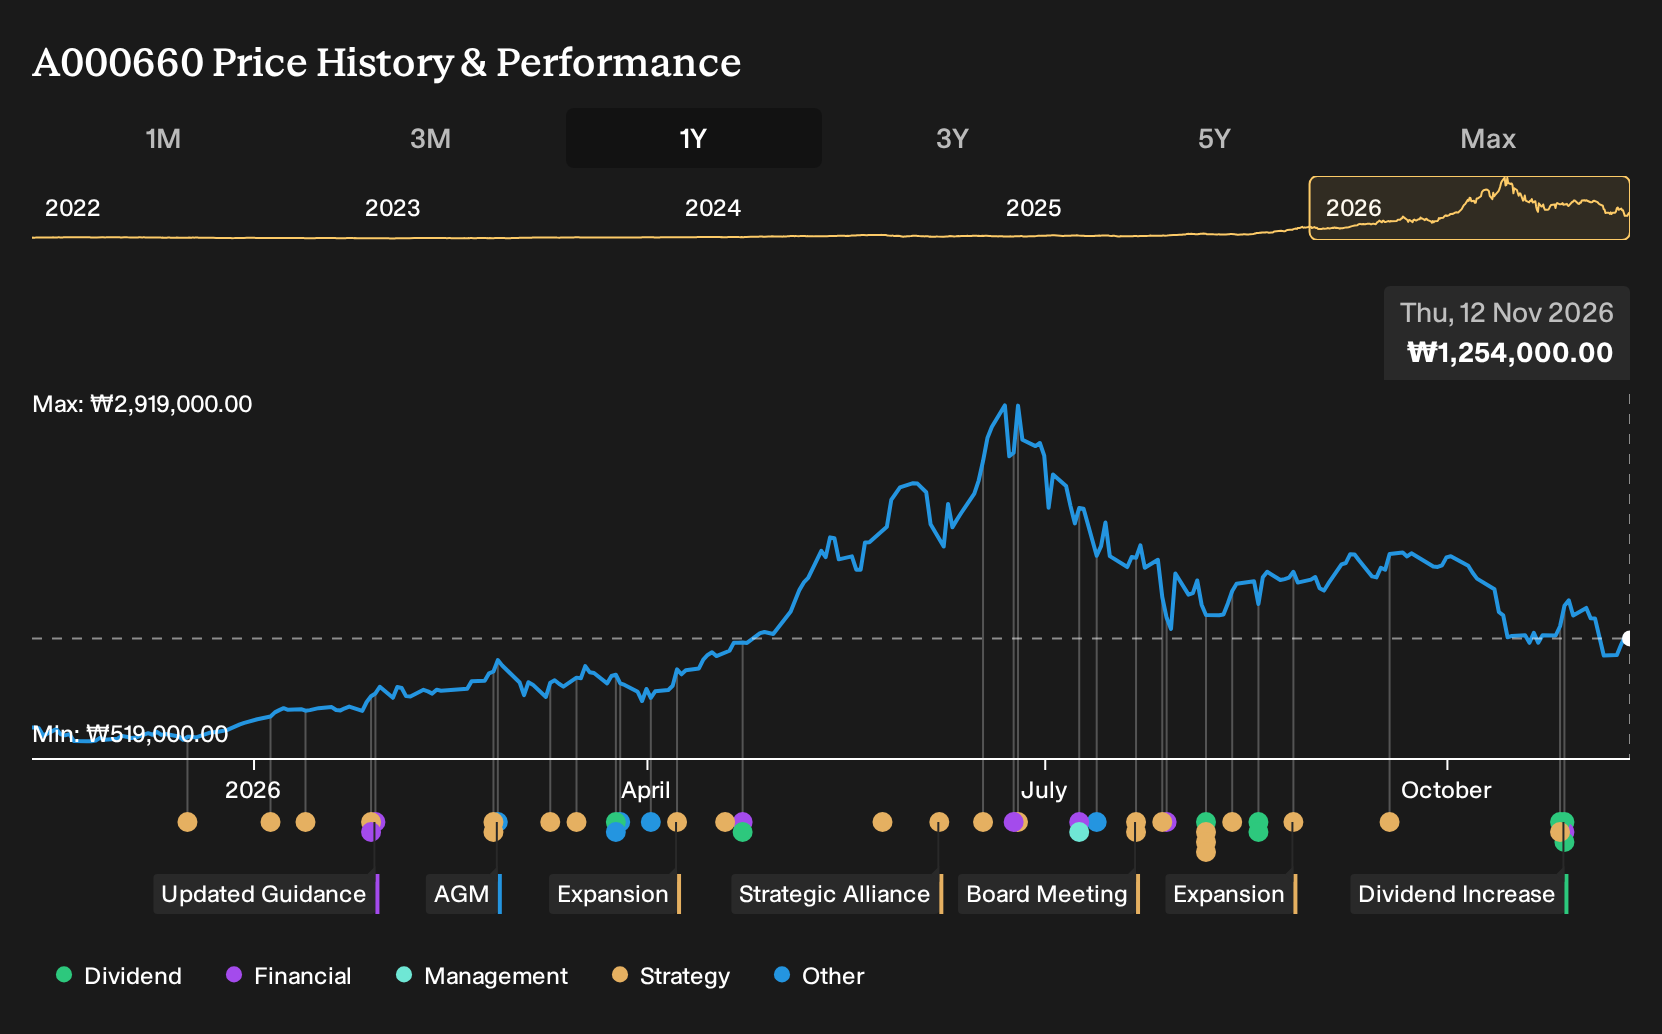
SK hynix is a Korean semiconductor producer that designs and manufactures memory chips used in AI, data centers, consumer electronics, and enterprise hardware across Asia, the United States, Europe, and other regions. This positions the company in direct competition with CXMT in DRAM and high bandwidth memory supply chains.
See how SK hynix's balance sheet measures up.
How could CXMT export restrictions affect SK hynix’s DRAM and HBM position?
If CXMT’s access to U.S. tools and software is curbed, a rival in DRAM and emerging HBM is likely to face more difficulty advancing its technology. That would leave SK hynix competing against a constrained Chinese peer rather than a fully tooled one, which could matter most in AI server and data center contracts where reliability and long term support carry weight.
Does this CXMT move change the SK hynix Narrative investors have been using?
The Simply Wall St Narrative leans heavily on SK hynix’s HBM leadership, close work with NVIDIA and large 2026 CapEx aimed at AI focused memory capacity. CXMT pressure lines up with the geopolitical risk side of that story, highlighting how export rules can both shield SK hynix from some competitors and still keep policy risk front and center for its own supply chain.
See how these catalysts shape SK hynix's path to a ₩3,141,025 fair value.
What should SK hynix holders watch next to see if this policy push matters financially?
The key marker is whether CXMT is formally added to the U.S. Entity List and what specific tools and software are restricted, since that would directly shape CXMT’s ability to ramp DRAM and HBM output. Any SK hynix commentary on contract wins or order visibility linked to this shift in coming quarterly reports will show how much of that flows through to its own operations.
Add SK hynix to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com