


EN
Why DICK'S Sporting Goods Fell Even As Sales Rose
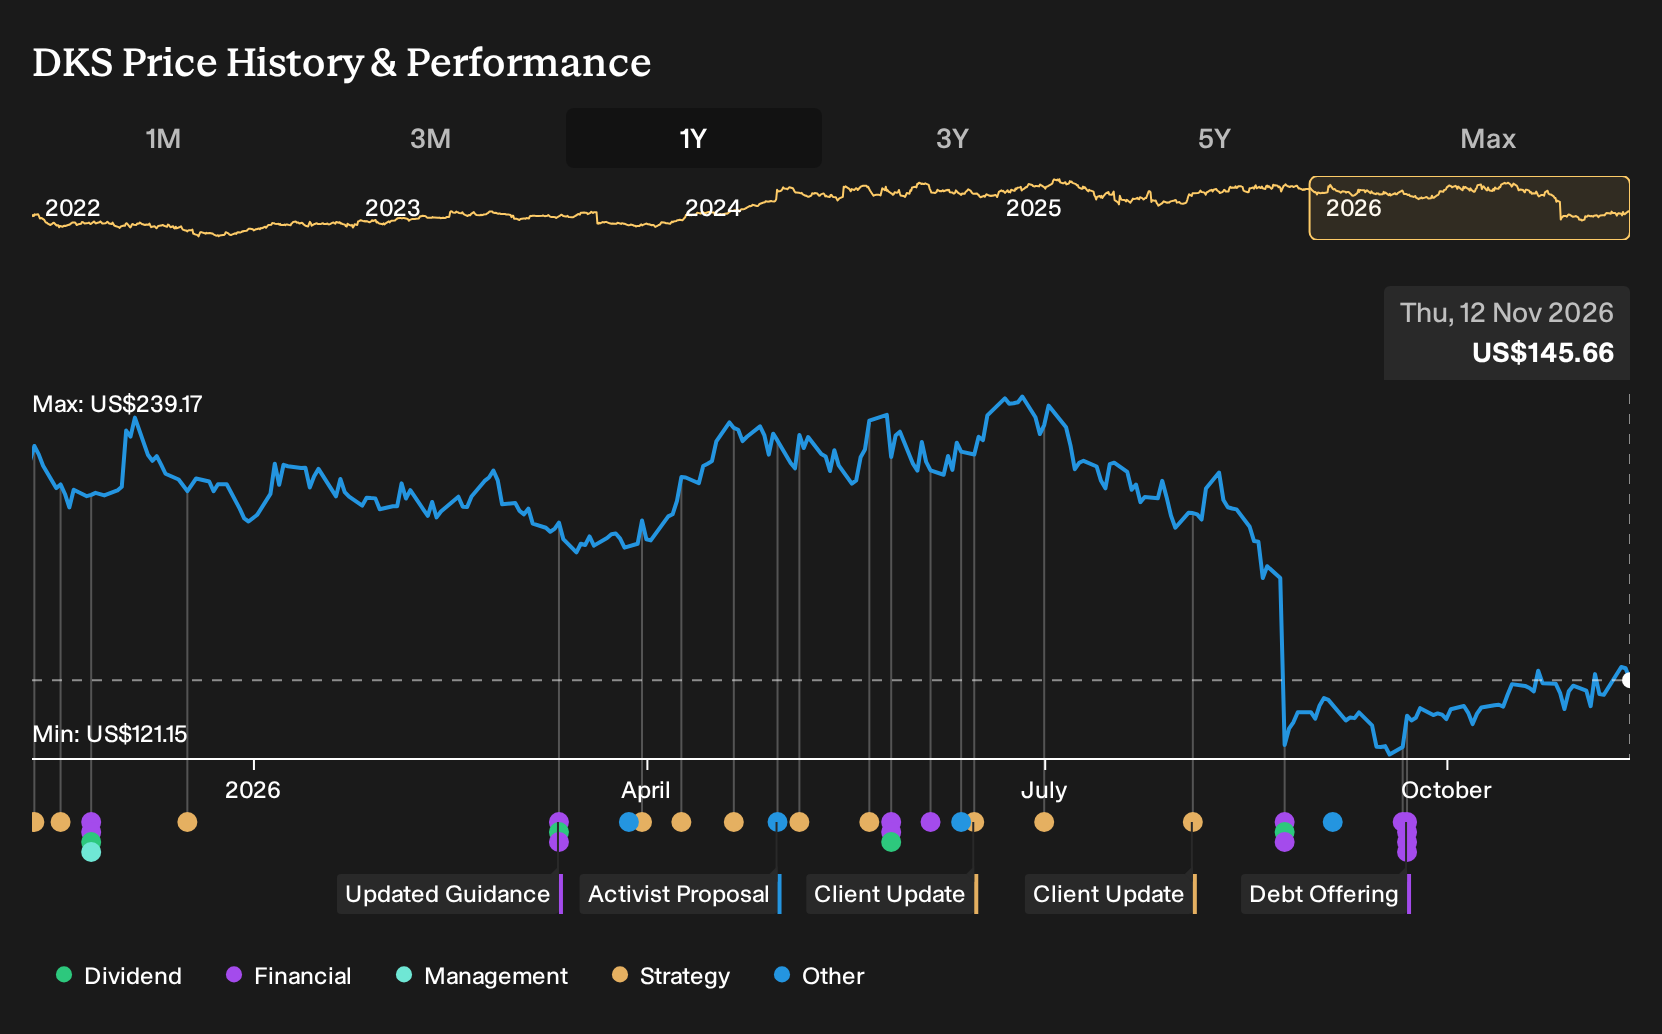
DICK'S Sporting Goods looked busy on the surface, with recent Q2 2027 figures showing higher revenue but a sharply thinner net margin compared with Q2 2026. Investors who held DICK'S Sporting Goods over the past year are down 30.8%, including dividends. If you had been weighing a position back in November 2025, the big question now is whether the warning signs around Foot Locker and spending plans were already visible in the public record.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind DICK'S Sporting Goods. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Two DICK'S Sporting Goods Stories Investors Were Weighing
The shares cost US$223 at the start of the period, which forced anyone looking at DICK'S Sporting Goods to decide which story felt more realistic.
On the optimistic side, the GameChanger and omnichannel Narrative saw Fair Value at US$240, or 8% above the start price, based on assumptions like 7.8% revenue growth and a 7.8% profit margin over three years.
The more cautious House of Sport Narrative put Fair Value at US$199, or 11% below the start price, and stressed risks such as heavy capital spending and inventory commitments if expected sales did not materialise.
What The Results Changed In The DICK'S Sporting Goods Story
The key development was the Foot Locker acquisition running into trouble. Q2 2026 results came with weaker Foot Locker comparable sales, operating losses and lower full year guidance, and were followed by securities lawsuits alleging overstated projections and inventory misstatements. Against that, overall DICK'S Sporting Goods revenue in Q2 2027 reached US$5,586.8m, but net income slipped to US$315.5m and margin compressed to 5.6%, so the period clearly supported the cautious case.
The hinge assumption was that acquired footwear demand and inventory quality would support healthy profitability. When you assess another retailer making a big purchase, track whether post deal guidance, segment level comps and net margin move in the same direction as the upbeat acquisition story.
What You Are Really Paying For In DICK'S Sporting Goods Today
DICK'S Sporting Goods now trades at US$146 after the share price fell 30.8% over the past year from US$223. The bullish analyst narrative on Simply Wall St sees fair value above that level, based on its own assumptions rather than hard fact.
Its thesis leans on experiential formats, youth-sports data and media, and footwear mix doing more work in future earnings. For that higher figure to be reached, a buyer today would need confidence that these newer revenue streams can more than offset ongoing Foot Locker pressure.
"The current valuation implies the share price already reflects Foot Locker's earnings drag, promotional footwear pressure, and litigation risk more than the potential cash flow contribution from experiential stores, higher-margin digital and media businesses, and a broader, higher-priced footwear mix."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond DICK'S Sporting Goods
DICK'S Sporting Goods ties your thesis to physical stores, in person service and managed inventory. Step one move away and a different engine appears.
Instead of selling gear, this other business builds digital rails for commerce. It helps merchants run online storefronts, payments and logistics more efficiently.
Its platform work also supports media, entertainment and content creators. Those customers rely on cloud tools to store data and run software.
AI services sit on that shared foundation, handling tasks from training models to serving recommendations. The open question is how this digital backbone might compound value differently.
One Narrative has already put a figure on it. → Uncover the company trading 41% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com