


EN
Interim Dividend Hike Altering The Investment Case For HOYA Stock (TSE:7741)?
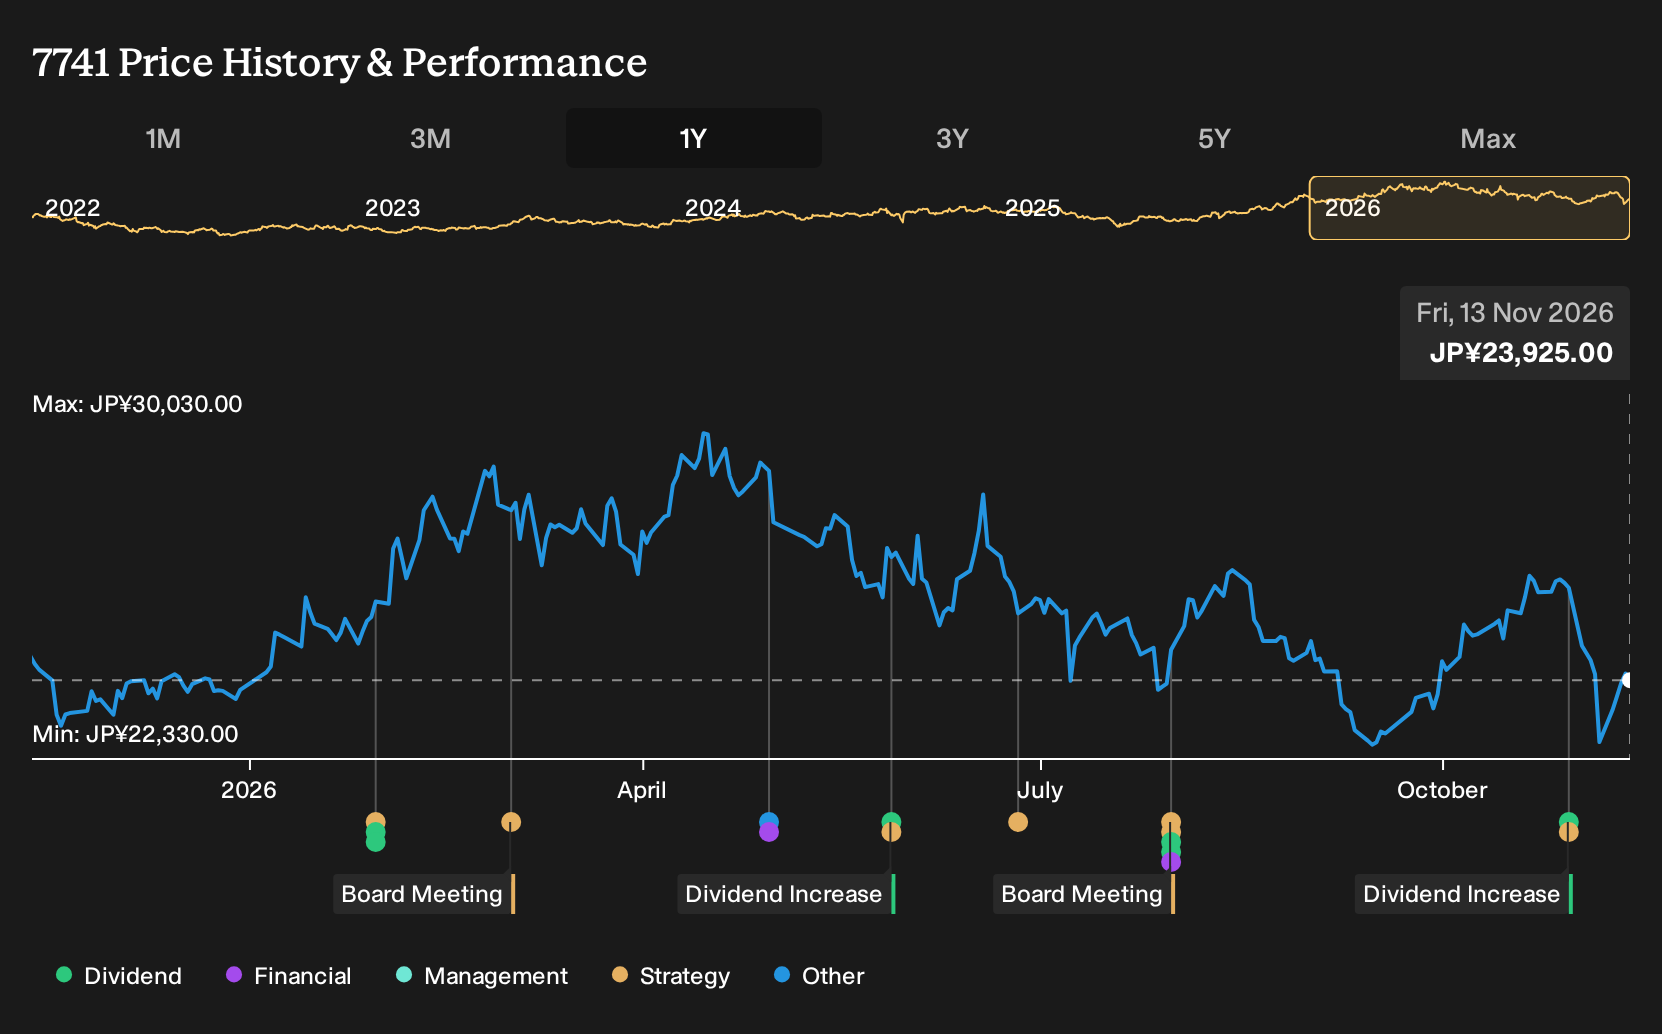
- At its board meeting on October 30, 2026, HOYA Corporation approved an interim dividend of ¥160.00 per share, up from ¥125.00 a year earlier. The dividend will be funded from retained earnings, with total payouts of ¥53,207 million to shareholders of record on September 30, 2026, and payment scheduled for November 30, 2026.
- The higher interim dividend is in line with HOYA's progressive policy that targets a 40% payout ratio and aims to balance growth investments, internal reserves, and cash returns through both dividends and share buybacks.
- Attention now turns to how HOYA's higher interim dividend fits into the broader investment narrative around capital allocation.
What Is HOYA's Investment Narrative?
To own HOYA, you need to be comfortable with a med-tech and optical components group that leans heavily on execution in technically demanding niches. The appeal rests on high quality earnings, strong return on equity at 27.4%, and profit growth that has recently run ahead of both its own 5 year pace and the wider Medical Equipment industry. Recent share performance has been soft over 30 and 90 days, yet the board is still committing to a progressive dividend framework and a 40% payout ratio target.
The higher interim dividend fits that story as a signal about confidence in cash generation rather than a new growth catalyst on its own. The bigger near term drivers remain demand for eyecare products and semiconductor related components, pricing discipline, and capital intensity in those lines. Investors also have to weigh valuation, with HOYA trading on a 28.3x P/E that sits above peers, at the same time as analysts see upside to their price targets and forecast earnings and revenue growth that is positive but not explosive.
That said, set against the healthy profitability and shareholder returns, there is a quieter issue in the background that could matter over time...
There's only one way to know the right time to buy, sell or hold HOYA. Head to Simply Wall St's company report for the latest analysis of HOYA's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket HOYA between ¥27,420.93 and ¥30,561.11 per share, which already shows how far private investors can disagree. Those views were set before the October 30 dividend decision, so you are weighing them against a fresh signal on how management treats surplus cash.
Explore another HOYA fair value estimate, including one that suggests as much as 27% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HOYA research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for HOYA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HOYA's overall financial health at a glance.
Looking For More Ideas Beyond HOYA?
If you want to set HOYA alongside other potential opportunities, the Simply Wall St Screener lets you quickly filter for businesses that match your preferred mix of quality, income, and resilience.
- For investors who care most about durable balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can handle setbacks without breaking stride.
- If you are hunting for mispriced quality, put today’s market to the test with a 18 high quality undervalued stocks that already scores well on both financial strength and cash generation.
- Those who prefer quieter portfolios can refine their watchlist using a 20 resilient stocks with low risk scores that screens for businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com