


EN
Reply (BIT:REY) Earnings And AI Push Put Fair Value Back In Focus
Reply (BIT:REY) just released third quarter and nine month 2026 results, with the Board signing off on a report that shows higher sales, rising net income and continued spending on artificial intelligence.
Reply shares have reacted to the earnings update, with the stock gaining 5.54% on the day and sitting at €139.1. The 30 day share price return of 8.16% and year to date gain of 25.43% point to building momentum.
Scan how Reply's momentum and AI push compare with other tech-focused businesses by reviewing the hand-picked 41 profitable AI stocks that aren't just burning cash in the sector.
Reply has just added a sharp move on the back of fresh earnings, which puts a timing question in front of you. Should you pay up after this jump, or wait and hope for a cheaper shot later in the valuation work.
Preferred P/E of 19.7x: Is it justified?
Reply is trading on a P/E of 19.7x, which puts a clear price tag on each euro of current earnings and sets a high bar against peers.
The P/E ratio compares the share price to earnings per share. For a software and digital services group like Reply, it often reflects what the market is willing to pay for current profitability in areas such as consulting, AI platforms and recurring digital services.
Reply currently screens as expensive when lined up against both the European IT industry average P/E of 17.8x and the peer average of 12.3x. That means investors are accepting a materially richer multiple than comparable businesses. Our fair P/E estimate of 35.5x indicates that the market valuation differs from this internal estimate based on current earnings quality and growth trends.
Explore the SWS fair ratio for Reply.
Result: Price-to-earnings of 19.7x (ABOUT RIGHT)
Still, Reply's premium P/E rests on the AI story holding up, and any slowdown in client tech budgets or weaker returns on these platforms could quickly test sentiment.
Find out about the key risks to this Reply narrative.
Another View: Reply Through A Cash Flow Lens
The P/E suggests Reply is carrying a premium, yet the SWS DCF model points the other way. On that approach, the shares at €139.1 sit above an estimated future cash flow value of €111.48, which frames the stock as overvalued rather than comfortably priced.
This gap matters. It hints that investors are paying up for earnings today compared with what projected cash flows support. Investors therefore need to judge whether Reply's AI and software pipeline justifies that extra outlay or calls for more caution.
Look into how the SWS DCF model arrives at its fair value.
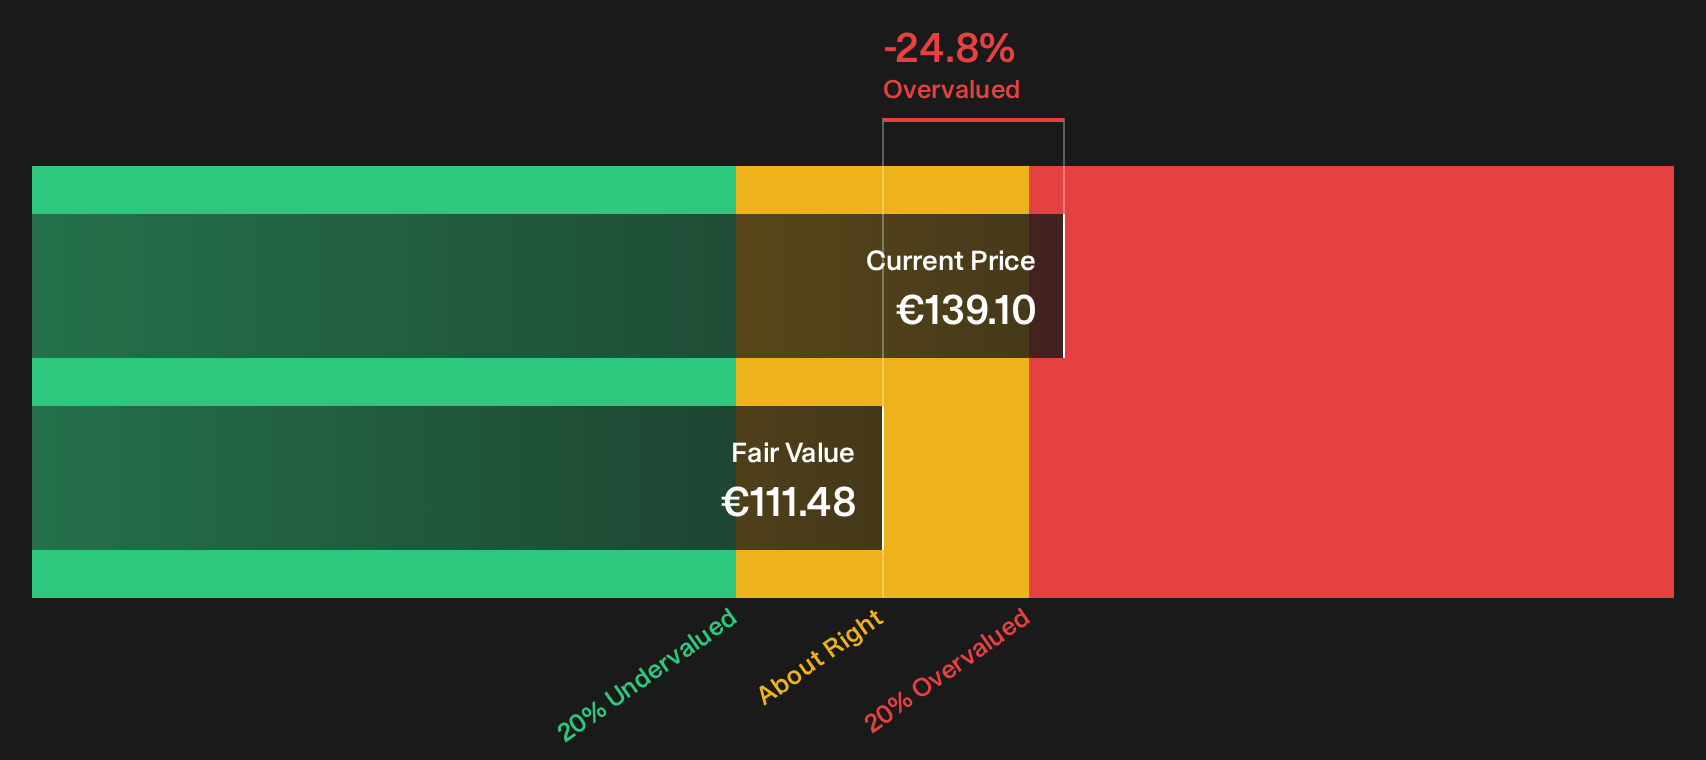
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Reply for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Reply is clearly mixed, so treat this as a prompt to dig into the numbers yourself and pressure test the narrative before it moves on without you. To see what the market currently views as the bright spots, take a closer look at the 2 key rewards
Looking for more Reply investment ideas?
If Reply has your attention, do not stop here. Broaden your watchlist with other focused opportunities that could sharpen your overall portfolio decisions.
- Target undervalued potential by scanning our hand picked 193 high quality undervalued stocks that combine solid fundamentals with prices the market may not fully appreciate.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (199 results) that can help cushion shocks when conditions turn against you.
- Hunt for future standouts with a 566 high quality undiscovered gems before they attract wider market attention and price in the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com