


EN
Top 3 Japanese Growth Stocks With Earnings Growth Up To 40%
AI related goods now drive most of global trade growth, with East Asia at the center of that supply chain. That places fast growing Japanese companies with high insider ownership in a prominent position, as management and major shareholders are directly exposed to both potential benefits and risks. This article walks through three such stocks and explains how their growth profiles and insider alignment may be relevant to long term investors today.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the absolute best, these 30 high growth high conviction stocks are the cream of the crop.
Sansan (TSE:4443)
Overview: Sansan is a Tokyo based SaaS provider whose core cloud contact and business card platform helps enterprises centralize sales relationships and related data.
Operations: Sansan generates about ¥48.9b from its Sansan and Bill One segment, ¥7.1b from Eight, and ¥446m from Others, almost entirely in Japan at ¥56.2b total.
Market Cap: ¥273.9b
Sansan lines up cleanly with the screener theme, because its core contact management platform and adjacent tools produce recurring SaaS income that tracks enterprise adoption. Forecast earnings growth of about 23.39% a year, alongside guidance for rising net sales and profit to 2027, gives that potential real weight, although everything depends on how one unseen pressure shapes customer expansion and pricing power.
That hidden pressure on customer expansion is exactly what the 3 key rewards and 1 important warning sign may clarify for Sansan, before growth expectations and pricing power decouple.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops semiconductor probe cards, wafer probers, and test equipment that help chip makers inspect and measure advanced devices worldwide.
Operations: Micronics Japan generates about ¥84.9b from its Probe Card Business and ¥1.4b from TE Business, with South Korea and Taiwan key markets.
Market Cap: ¥391.6b
Micronics Japan lines up with the screener because earnings increased by 89.4% last year and analysts expect about 24.88% annual profit growth, tied directly to demand for semiconductor test equipment. The valuation at a 20.9x P/E reflects that sentiment, while potential returns depend on how changes in chip industry investment affect probe card orders and margins.
Those order swings are exactly what the 2 key rewards and 1 important major warning sign unpacks for Micronics Japan, before probe card demand and profitability move out of sync.

freee K.K (TSE:4478)
Overview: freee K.K provides cloud-based accounting, HR, tax and related software in Japan, aiming for scalable subscription revenue from small businesses.
Market Cap: ¥244.2b
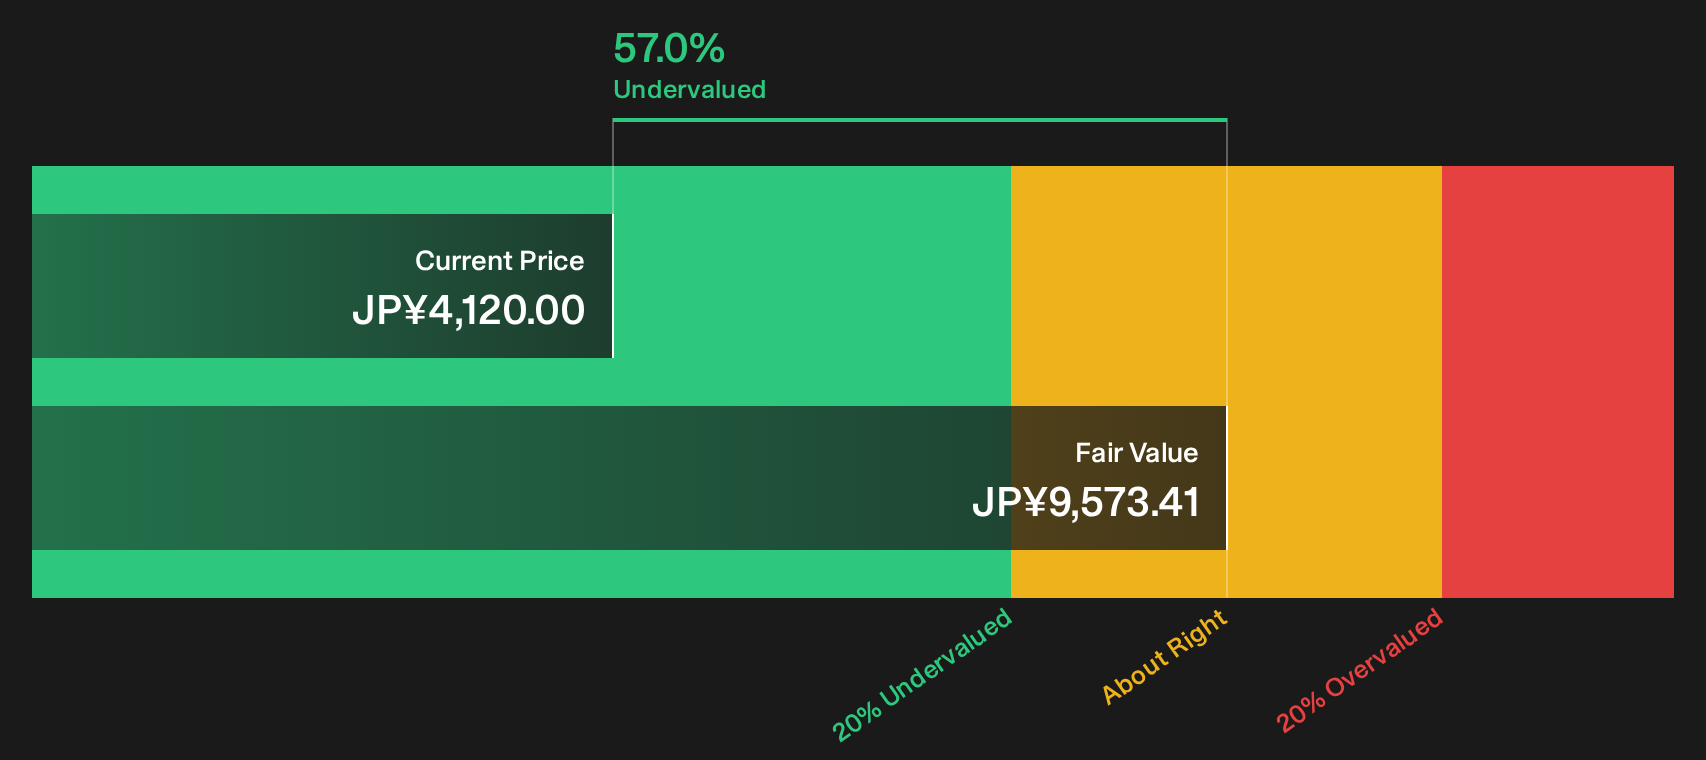
freee K.K lines up neatly with the screener theme because its accounting and HR SaaS tools support recurring subscriptions, 17.6% forecast revenue growth and earnings expected to rise about 39.78% a year. The stock trades around 57% below estimated future cash flow value, so much depends on how efficiently margins respond to that growth ambition.
That margin question is exactly what the DCF valuation analysis for freee K.K helps you size up, before freee K.K’s growth ambitions and cash generation potentially pull apart.
Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout momentum, flying under the radar for now, tends to get caught late by the crowd. Scan these while it matters and get in early.
- Target durable cash generators by running the list of solid balance sheet and fundamentals (25 results) so you focus on businesses where strong finances back every growth story.
- Hunt for mispriced quality with the 18 high quality undervalued stocks and spot companies where cash flows and balance sheets do more talking than short term sentiment.
- Ride long term income momentum through the 27 dividend fortresses and zero in on higher yielding businesses that keep regular payouts front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com