


EN
Has Capri Holdings (CPRI) Fallen Far Enough To Be A Bargain?
Capri Holdings has had a bruising few years in the market, and the stock now sits at US$20.38 with a long record of share price losses behind it. After that kind of drawdown, the key issue for you is whether the current price still lines up with what the business is earning.
- Capri has declined about 68.4% over 5 years, which puts the focus squarely on whether investors have been too harsh or simply catching up with the company’s earnings power.
- Recent leadership changes at Capri, along with efforts to sharpen margins at brands like Michael Kors and Jimmy Choo, can influence how durable its profits look and how much of those earnings might reasonably be capitalized into the share price.
- Your read on Capri Holdings is one view; the desks covering it have another. See what analysts think Capri Holdings's shares could be worth.
The issue now is whether Capri Holdings' current valuation can be explained by the level and quality of the earnings it is generating today.
If you want to cross check whether Capri Holdings' earnings based valuation question shows up elsewhere, run the same filter across 32 high quality undervalued stocks.
Does Capri Holdings Look Undervalued on Earnings?
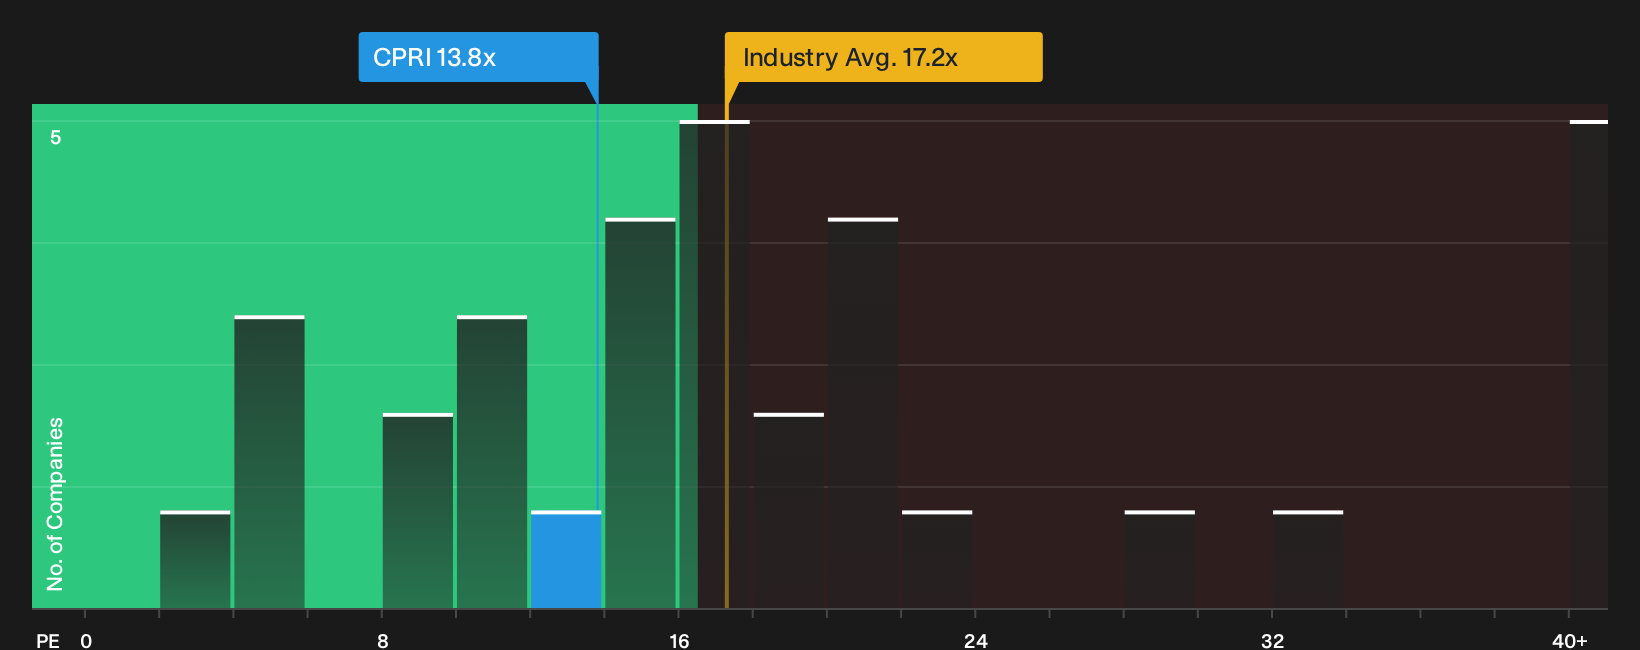
The P/E ratio is a useful lens for Capri Holdings because earnings quality and brand strength tend to drive how investors price luxury groups. Capri trades on a P/E of about 13.8x, which sits below both the Luxury industry average of roughly 17.2x and the broader peer group near 18.2x. On this framework, Capri looks undervalued relative to what investors are currently willing to pay for comparable businesses.
Because of that gap, the Fair Ratio model, which looks at factors like Capri’s profitability profile, risk and market size, points to a higher P/E than where the shares change hands today. Despite the recent jump in Capri’s share price after stronger earnings and updated guidance, the current multiple still prices the stock at a discount to what this tailored yardstick implies. That leaves the question of whether the earnings power behind that P/E is durable enough for the discount to matter to you. Explore the numbers behind Capri Holdings's P/E valuation.
The Capri Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Capri Holdings take the P/E puzzle above and translate it into explicit views on what kind of future growth, profitability and earnings profile would need to play out for the stock to be worth materially more or less than today’s price. Each one ties its number to a clear view on where growth, margins and business risk could head next, giving you a reference point you can revisit as fresh information comes in on the Community page.
The bullish and bearish Narratives on Capri Holdings both hinge on margins, yet they disagree on how secure those profits really are.
Bull case: 12% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on improving mix and brand monetisation.
"Planned investment in Michael Kors store renovations and selective new store openings, including around 50 stores already refreshed with higher traffic and revenue…"
Discover why this Narrative puts Capri Holdings at 12% undervalued.
Bear case: 13% overvalued
This angle comes from the bearish analyst Narrative on Simply Wall St, which focuses on execution risks and regional softness.
"Capri is leaning into digital channels, larger customer databases and social platforms to target younger consumers, yet the cut to FY27 revenue guidance…"
Explore why this Narrative puts Capri Holdings at 13% overvalued.
One more angle on Capri Holdings that deserves your attention
Before you focus only on Capri Holdings' earnings and valuation, it is worth knowing that Simply Wall St's broader checks have flagged specific issues that could change how you view the risk profile. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com